

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Intelligent TCM Diagnosis System Market to Surge from USD 679.19 Million in 2025 to USD 1,750.26 Million by 2032 — 14.48% CAGR Forecast (2026–2032)

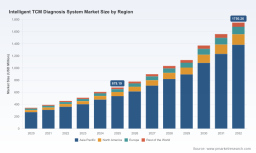
Worldwide Intelligent TCM Diagnosis System Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study — the Worldwide Intelligent Traditional Chinese Medicine (TCM) Diagnosis System Market Report (base year 2025; historical window 2020–2025; forecast 2026–2032) — is published to serve as a strategic compass for healthcare executives, medtech investors, and policy teams preparing decisions in 2026. In this preview we surface the study’s high‑conviction findings, practical frameworks and competitive implications while intentionally withholding the granular segment-level datapoints that are reserved for subscribers to the full report.
Worldwide Intelligent TCM Diagnosis System Market
Macro context: scale, growth and what it means for 2026
The intelligent TCM diagnosis systems market has moved from a niche research activity into a commercially material sector. Our model — anchored on rigorous historical reconciliation and scenario-based forecasting — shows a continued step-change in 2026 growth, following several strong years of adoption and product maturation. The market’s compound annual growth rate (CAGR) through the forecast horizon is 14.48%, and the preponderance of growth drivers (digital transformation in TCM clinical settings, sensor and AI advances, and reimbursement pathway evolution) coalesce to make 2026 a pivotal year for scaling pilots into enterprise-grade deployments.
Worldwide Intelligent TCM Diagnosis System Market
For buyers, suppliers and capital allocators, the headline implication is simple: capability investments and commercial commitments made in 2026 will compound significantly over the next several years. This report positions readers to convert that macro tailwind into defensible, executable strategies without exposing the customer‑sensitive segment breakdowns that premium subscribers will access in the full deliverable.
Worldwide Intelligent TCM Diagnosis System Market
What the report delivers — actionable, playbook‑oriented content
- Validated market sizing and growth scenarios: Reconciled historical performance (2020–2025) and three forward-looking cases for 2026–2032 to stress-test investment and product roadmaps.
- Commercial segmentation frameworks: Demand archetypes by end-user profiles, care settings, and product archetypes (multimodal platforms, pulse devices, tongue systems, acupoint systems) — designed as go/no-go decision matrices for product managers.
- Regulatory & reimbursement playbook: Matrixed pathways that map evidentiary requirements, approval routes and likely reimbursement outcomes across priority markets, including DRG integration scenarios and subsidy levers.
- Clinical adoption and validation protocols: Protocol templates for rapid clinical pilots, KPIs for diagnostic concordance, and statistical power calculators tuned for TCM endpoints.
- Commercial go-to-market blueprints: Channel mixes, pricing models, and partner archetypes (hospital systems, TCM chain networks, health screening centers, and home healthcare ecosystems) with tactical timelines.
- M&A and partnership playbook: A shortlist of capability gaps, diligence checklists, and earn‑out constructs that reflect the capital markets’ appetite for medtech–AI adjacencies.
- Risk & mitigation matrix: Technical, regulatory, clinical and commercial risks prioritized by impact and likelihood, with ready-to-implement mitigations.
Market dynamics shaping 2026 choices
Three structural forces will determine winners and losers in 2026:
- Policy & reimbursement evolution: China’s nationwide rollout of CHS-DRG-like payment systems, and the ongoing use of DRG-based reforms in TCM hospitals, are not only compressing length-of-stay and cost variability but also changing clinical incentives. Where reimbursement recognizes objective diagnostic data and TCM-specific bundles, adoption accelerates. Our study models alternative reimbursement pathways to quantify the commercial returns under each scenario.
- Technology convergence: Advances in high‑fidelity sensors, multimodal fusion (tongue, pulse, facial imaging, inquiry data), and boutique clinical AI models are improving diagnostic consistency — a prerequisite for institutional adoption in hospitals and screening centers. However, implementation complexity rises with system scope; pragmatic modularization strategies surface as the dominant near-term commercial approach.
- Evidence and trust-building: Objective, peer-reviewed clinical validation and alignment with hospital workflows are the gating items for scale. The report provides a stepwise evidence-generation playbook that connects pilot endpoints to procurement KPIs and to DRG reimbursement levers.
Competitive landscape — profiles, positioning and strategic moves
The marketplace is characterized by vibrant specialist players and strong academic–industry collaborations. Market concentration is meaningful but far from monopolistic: the top three competitors together account for a material but not dominant share, and the top five capture roughly half of market revenues. This structure produces space for both scale players and focused innovators.
- Established medtech and device specialists: Several incumbent manufacturers have converted traditional diagnostic instrumentation expertise into intelligent systems, emphasizing robustness, serviceability and channel relationships with hospitals and clinic networks.
- AI-first clinical software companies: Startups and mid‑sized firms focused on model accuracy and cloud-enabled analytics are competing to own the interpretive layer — the “diagnostic OS” that translates sensor outputs into actionable clinical guidance.
- Academic and institutional collaboratives: University centers and research hospitals (notably teams that have recently deployed AI-assisted diagnostic instruments) are proving grounds for clinical validation and supply‑side credibility; their technology transfer and commercialization choices will set standards for the whole market.
Representative organizations profiled in the report (selected examples) include manufacturers and AI integrators across China’s TCM innovation ecosystem — from Beijing- and Shanghai-headquartered device pioneers to provincial medtech firms and university research centers that are moving into clinical deployment. Their strategic postures range from vertical integration (device + AI + services) to focused component supply and validation partnerships.
Case highlight: academic deployment turning into commercial acceleration
Recent clinical deployments of university‑developed intelligent diagnostic instruments have catalyzed ecosystem confidence. These deployments demonstrate how rigorous sensor design coupled with hospital-led validation can reduce procurement friction and inform DRG-based reimbursement conversations. In our strategic scenarios, such academic-to-commercial transitions materially shorten time-to-adoption for partners that secure early validation agreements.
What this means for executive decisions in 2026
We translate the study’s insights into four practical decision playbooks:
- For suppliers & product teams: Prioritize modular, upgradeable architectures — begin with core diagnostic modules that map tightly to hospital workflows and DRG-sensitive endpoints. Invest in one or two high‑quality clinical pilots with measurable economic endpoints (length-of-stay, procedure substitution, screening yield).
- For health system purchasers: Structure procurement trials around interoperability and total cost of ownership. Use staged adoption agreements that allow technology swaps based on pre-specified clinical and economic KPIs.
- For investors & corporate development: Focus on targets that combine validated clinical outcomes with defensible data assets (annotated multimodal datasets and model lineage). Consider earn-out structures tied to deployment milestones and reimbursement confirmations.
- For policy & reimbursement teams: Align subsidy and DRG policies to reward objective diagnostic outputs that demonstrably improve care quality and cost efficiency — pilot bundled payments that incorporate validated intelligent diagnosis modules.
Why the full report is essential for operational planning
This preview explains the strategic contours and decision levers. The full PW Consulting report contains the granular tools and numbers needed to operationalize strategy in 2026: detailed market sizing by product and end-user, regional demand models, pricing decks, channel economics, and an annotated list of acquisition targets and partnership candidates. These are the elements that convert a directional strategy into executable plans and procurement contracts.
We intentionally withhold granular segment breakouts and per-region/application figures from this public summary to preserve the competitive value of the full dataset and to ensure clients obtain the comprehensive playbooks that make 2026 actions confidently executable.
Next steps — how to use this preview
- Use our high‑level conclusions to align 2026 budgets around modular product development, evidence generation and key pilot partnerships.
- Adopt the reimbursement and pilot KPIs described here as gating criteria for procurement and investment approvals.
- Contact PW Consulting to access the full report and the bespoke consulting options: the full deliverable includes downloadable templates, dataset access, and a tailored workshop to adapt the playbooks to your organization’s priorities.
PW Consulting’s Worldwide Intelligent TCM Diagnosis System Market Report offers the strategic scaffolding that health systems, medtech companies, and investors need in 2026. For teams that must convert market momentum into measurable outcomes, the full report and client workshops provide the operational confidence to move from pilot to scale.
For detailed analysis of this topic, please visit the official page: Worldwide Intelligent TCM Diagnosis System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com