

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide ESD Packing Market Hits USD 5,035 Million in 2025, Set for Continued Growth

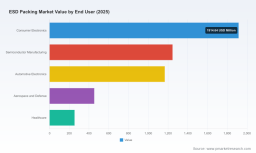
Worldwide ESD Packing Market — Strategic Preview for 2026: A PW Consulting Industry Brief
Executive snapshot
The global market for electrostatic discharge (ESD) packing is entering a phase of sustained expansion and structural evolution. Our new report, anchored on a 2025 base year and covering historical performance from 2020–2025 with a forward-looking forecast through 2032, quantifies a clear trajectory: total market revenue rose from the low thousands (USD Million) in 2020 to roughly USD 5,035.0 Million in 2025, and is projected to continue rising through the forecast window — driven by an 8.1% compound annual growth rate (CAGR) in the 2026–2032 period. By 2032, the industry is expected to surpass current mid‑single‑digit billions, reflecting accelerating demand across electronics, semiconductors, automotive and adjacent sectors.
Worldwide ESD Packing Market
Why this matters for corporate decision-makers in 2026
- Timing of strategic moves: The coming two-to-three years represent a window to lock in supply, accelerate sustainable product development, and capture pricing power before a new maturity phase of the market.
- Capital allocation: Suppliers and end users should re-weight capex and R&D to account for higher-margin specialty polymers, patented conductive additives, and recyclable-material solutions that command premium positioning.
- Regulatory alignment: Emerging producer responsibility and recycled-content regulations in major jurisdictions will materially affect packaging design choices and supply contracts. Proactive compliance is now a competitive advantage, not merely a cost.
Market trajectory — what the headline numbers tell us
The ESD packing market has demonstrated robust recovery and expansion since 2020. Total industry revenue expanded materially through 2025 and, on the projection path we model, will continue to grow at an annualized rate of 8.1% during the 2026–2032 forecast window. This pace implies both underlying volume growth in electronics and semiconductor supply chains and a product mix shift toward higher-value, sustainability-oriented packaging solutions.
Worldwide ESD Packing Market
Equally important is the market structure: concentration metrics reflect a moderately fragmented supply base. The top three players account for approximately 32.4% of the market, while the top five together control roughly 45.85%. That level of concentration suggests meaningful room for regional specialists, innovative entrants, and sustainability-focused incumbents to secure differentiated positions through product, service, or cost leadership.
Worldwide ESD Packing Market
Forces shaping demand and margin dynamics
- End-market growth and technology cycles: The waves of investment in semiconductors, advanced consumer electronics, electric and autonomous vehicles, and aerospace avionics amplify demand for ESD-safe packing across multiple nodes of global supply chains.
- Materials economics: Polyethylene (PE) remains the dominant raw material on a cost and availability basis. At the same time, specialized polymers and conductive fillers (for example, carbon black blends and proprietary conductive layers) are driving up the cost base for high-performance ESD products — and creating product tiers with different margin profiles.
- Sustainability and regulation: Producer responsibility legislation and ambitious recyclability mandates — such as major state-level EPR frameworks adopted in North America — are shifting buyer preferences toward recyclable or compostable ESD alternatives and increasing the premium for verified recycled content and circular‑design solutions.
- Innovation and hybrid solutions: Recent introductions that pair ESD protection with corrosion inhibition or paper-based substrates indicate that multi-functional, eco-conscious materials will capture growing adoption among cautious OEMs and tier suppliers.
Competitive landscape — strategic positions and intent
The market is populated by a mix of global materials and packaging conglomerates, regionally focused specialists, and techno‑packaging innovators. Key players we assess include multi-sector giants and dedicated ESD specialists:
- DESCO Industries Inc. (United States) — well‑established in static dissipative and shielding bags and trays, with deep penetration in electronics and semiconductor protection.
- Nefab Group (Sweden) — known for reusable and sustainable ESD packaging systems serving automotive and aerospace logistics; represents an example of an industrial-packaging player leaning into circularity.
- 3M Company (United States) — leverages broad materials science capabilities to supply films and protective materials focused on static control for sensitive components.
- Smurfit Kappa Group and DS Smith plc (Ireland and UK) — illustrate how corrugated and paper-based ESD solutions are being developed by major packaging incumbents to address recycling and lighter-weight distribution requirements.
- Specialist manufacturers such as Teknis Limited (UK), Dou Yee Enterprises (Singapore), Cortec Corporation (US), and Sealed Air Corporation (US) — each pursuing differentiated propositions, including recyclable pouches, corrosion-inhibiting films, and ESD paper products.
Recent industry activity validates two strategic themes: (1) diversification into lower-carbon or recyclable ESD materials (for example, recyclable ESD pouches and paper-based ESD products); and (2) hybrid functionality that combines ESD control with corrosion inhibitors or permanent static-dissipative characteristics. Notable product launches and enhancements across 2024–2025 underscore this orientation, as do announcements from both material innovators and traditional packaging groups.
Strategic implications and recommended actions for 2026
We distill the path to competitive advantage into five interlocking strategic priorities for companies that want to lead or survive in the next phase of ESD packing market evolution.
- Embed sustainability into product and procurement decisions: Align product roadmaps with recyclability and recycled‑content mandates. For OEMs this means qualifying alternative ESD substrates now and establishing dual-sourcing to mitigate transitional risks.
- Differentiate on multi-functionality: Invest in R&D to combine ESD control with corrosion protection, moisture barriers, or returnable-system designs. These composite offerings command higher ASPs and deepen customer stickiness.
- Reassess cost‑to-serve and supplier economics: Model the margin impact of specialty polymers and conductive fillers. Negotiate long-term raw‑material hedges and collaborative innovation agreements with resin suppliers to stabilize costs.
- Prepare for regulatory compliance as strategic risk: Build compliance roadmaps for emerging EPR schemes and recycled-content requirements. Early adapters will gain procurement preference and reduce potential supply-chain disruption.
- Pursue targeted M&A and partnerships: The market’s moderate concentration offers acquisition opportunities for scale, geographic reach, and access to patented materials. Partnerships with material science firms can accelerate time-to-market for sustainable ESD solutions.
Tactical playbook — practical moves for 12–24 months
- Initiate a supplier scorecard that weights sustainability credentials, technical validation throughput, and total landed cost.
- Run pilot programs for paper-based or corrosion-inhibiting ESD solutions across a representative set of SKUs and geographies to gather empirical performance and logistics data.
- Establish a cross-functional regulatory task force to map EPR timelines to product redesign milestones and procurement contracts.
- Lock in selective long-term resin and conductive additive agreements to protect margins for higher-performance lines.
- Develop a customer-facing sustainability narrative and verified claims framework (third-party certification where possible) to support tender wins in regulated markets.
What PW Consulting’s full report delivers
Our report is explicitly designed to be immediately operational for executive leadership and strategy teams. It contains:
- A detailed demand and supply model (historical 2020–2025 and forecast 2026–2032) with scenario analyses and sensitivity testing to help quantify upside and downside cases;
- Vendor benchmarking and a supplier matrix covering capabilities, geographic strength, product portfolios, and strategic intent;
- Cost-to-serve and margin impact models that incorporate raw-material pricing scenarios, conductive additive costs, and recycling/processing economics;
- Regulatory impact mapping and compliance playbooks tailored to North America, Europe and Asia regulatory realities;
- Roadmaps for product innovation, commercialization, and channel strategies, together with an M&A target shortlist filtered for strategic fit;
- Implementation templates: RFP language for sustainable ESD procurement, pilot program outlines, and a packaging circularity checklist.
Importantly, while this preview highlights strategic insights and the macro market trajectory, the full report contains the granular segmentation intelligence, supplier-level metrics, and modeled financial outcomes that underpin board-level decisions. That detailed data is intentionally gated to ensure our clients receive actionable proprietary analysis.
Closing — the strategic vantage point for 2026
2026 will be a decisive year in which buyers and suppliers of ESD packing either adapt to a new regulatory and materials landscape or face margin and access pressure. The macro path is clear: sustained growth at an 8.1% CAGR through the late 2020s, rising adoption of higher-value and sustainable solutions, and a competitive field where both global conglomerates and niche innovators will jockey for position. For executives preparing capital plans, supplier strategies, or innovation roadmaps, the tradeoffs between near-term cost management and long-term positioning are already real.
PW Consulting’s Worldwide ESD Packing Market report equips decision-makers with both the quantitative models and the tactical playbooks required to act with confidence in 2026. For access to the full suite of data, granular segmentation, and supplier-level insights that support executable plans, please consult the report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide ESD Packing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com