

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smartphone Panel Market Forecast to Reach USD 64.91 Billion by 2032

Worldwide Smartphone Panel Market 2026: Strategic Imperatives from PW Consulting
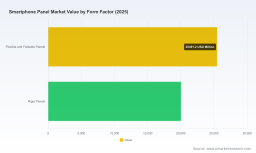
PW Consulting’s latest Worldwide Smartphone Panel Market report (base year 2025, forecast 2026–2032) synthesizes macro forecasts, technology pathways, supply‑chain stress‑points and competitive trajectories into an actionable playbook for executives making 2026 decisions. Our top‑line modeling shows the global smartphone panel market continuing steady growth from a 2025 base of USD 45,520.0 Million, expanding at a compound annual growth rate (CAGR) of 5.19% through 2032, and reaching a projected USD 64,910.12 Million by 2032. These headline figures matter — but the strategic value of the report lies in how they translate into procurement timing, capex cadence, partnership choices and risk mitigation for the coming 18–36 months.
Worldwide Smartphone Panel Market
Why this report matters for 2026 decision cycles
-
Actionable foresight for capital allocation: With positive but measured growth, device OEMs and panel suppliers must prioritize targeted capacity additions and technology investments rather than broad-based expansion. The report maps where incremental capacity is most likely to generate differentiated returns and where it risks adding chronic overcapacity.
Worldwide Smartphone Panel Market -
Supply‑chain de‑risking for procurement teams: The research identifies critical raw‑material bottlenecks and regulatory vectors that can abruptly alter cost structures or availability — information procurement teams need to rewrite supplier agreements and inventory policies in 2026.
Worldwide Smartphone Panel Market -
Technology roadmap alignment for product teams: The AMOLED transition in mid‑range devices, the maturation of flexible/foldable form‑factors, and material engineering advances (UTG, polyimide) create distinct windows of product differentiation; our scenarios quantify the timing and value capture for each.
-
M&A and partnership screening: For corporate development groups, the combination of market concentration metrics and a granular supplier matrix narrows targets for JV, minority investment, or bolt‑on acquisitions to secure access to technology or capacity.
Market trajectory and the drivers behind the numbers
The 5.19% CAGR that underpins our base forecast combines steady volume demand for mainstream smartphones with a faster shift in panel content per device. Two structural forces are decisive: first, the continued migration from legacy LCD technologies toward AMOLED, which is accelerating in mid‑range segments; second, rising content per handset driven by higher refresh rates, larger active areas (including foldables) and advanced features (privacy, low‑power LTPO variants). Independent industry tracking cited in the report corroborates rising AMOLED penetration — a trend that changes the upstream mix of materials, processes and capital intensity.
On the demand side, the market is resilient but differentiated. Mature regions show slower unit growth but rising ASPs per panel as premium features proliferate; higher‑growth regions continue to drive unit volume. This bifurcation creates simultaneous opportunities for premium players and scale‑oriented suppliers targeting value‑segment volumes.
Supply‑side dynamics: capacity, materials and regulation
The supply landscape is in active flux. Several major suppliers are re‑profiling investments toward higher‑generation OLED lines and flexible panel capacity. Recent public developments — from capacity reviews for foldable OLED programs to activations of new Gen‑8+ OLED lines — reflect that investment is taking place, but it is targeted and contingent on OEM program wins and materials availability.
Material concentration and regulatory pressure are the dominant risk amplifiers. Global processing of key display minerals and compounds (for example, indium and other ITO‑related inputs) remains concentrated geographically, and policy actions such as investigations into critical mineral imports create a credible policy tail‑risk for 2026. Near‑term tactical decisions — inventory buffers, strategic stockpiles, vendor contracts with pass‑through provisions — will be decisive for cost volatility management.
Competitive landscape: what the supplier map means for partners and rivals
The panel supplier universe remains moderately concentrated: roughly two‑thirds of global supply is controlled by the top three suppliers, and the top five account for well over four‑fifths of the market. That concentration creates both stability and leverage: leading suppliers set technology agendas and enjoy scale benefits, while nimble challengers can capture share through focused investments in niche technologies or aggressive pricing at scale.
-
Tier‑one incumbents retain premium advantages. Suppliers with advanced LTPO/LTPS process know‑how and proven flexible AMOLED production remain the default partners for flagship programs. Public signals of increased foldable OLED capacity are a direct response to OEM demand for differentiated form‑factors.
-
High‑volume Chinese players are closing the gap on process maturity. Gen‑8+ activations and targeted investments in AMOLED lines are enabling higher throughput and giving OEMs diversified sourcing options — especially for mid‑ and upper‑mid segments.
-
Specialists and Taiwanese/Japanese vendors continue to be relevant in narrow applications and legacy volumes. Their role in multi‑sourcing strategies is significant for risk mitigation and for securing specific IP or process capabilities.
For OEMs and component suppliers, the implication is clear: contractual strategies in 2026 should reflect a two‑track approach. Retain strategic relationships with premium suppliers for flagship content, while building scale relationships with high‑volume producers to control cost and capacity exposure.
What the PW Consulting report contains — practical, executable deliverables
Our report is designed to move teams from insight to action across commercial, engineering and C‑suite agendas. Key deliverables include:
-
Top‑down market sizing and bottoms‑up demand scenarios through 2032, stress‑tested against high/low AMOLED adoption and foldable penetration cases.
-
Capex and capacity tracker with project timing, technology classification and likely fill‑rates at 6‑month granularity.
-
Materials risk heatmap (indium/ITO, polyimide, UTG, specialty gases) with supplier concentration indicators and mitigations.
-
Competitive vendor dossiers and supplier scorecards that synthesize production footprints, technology strengths, customer exposures and trade‑policy risk vectors.
-
Scenario playbooks for procurement (dual‑sourcing, conditional agreements), product (AMOLED roadmap timing), and corporate development (target screens and valuation sensitivities).
-
An executable 90‑day action plan for OEMs to reset supplier contracts, prioritize sample pipelines and align product launch windows to supplier readiness.
To preserve the commercial value of our proprietary modeling, we present detailed split tables, region/technology breakdowns and supplier‑level revenue allocations exclusively in the full report and in our interactive dashboard. The executive summary available here is intentionally illustrative — it shows the strategic logic and directional sizing but not the granular, segment‑level allocations that competitive teams use for tactical decisions.
Practical recommendations for 2026
-
Reconfigure sourcing to a dual‑track model: secure guaranteed capacity with incumbent premium suppliers for core flagship needs and establish volume agreements with high‑throughput suppliers to capture mid‑segment demand.
-
Hedge material supply exposures: build conditional inventory agreements for critical inputs, qualify secondary suppliers for ITO alternatives, and evaluate vertical options for UTG/polyimide sourcing where margins justify.
-
Time capex to demand inflection points: favor modular expansions and conversion capabilities (LCD→AMOLED or rigid→flexible lines) over greenfield volume builds unless tied to confirmed OEM programs.
-
Embed regulatory scenario planning into commercial contracts: include adjustment clauses for tariffs or export controls and map alternative logistics routes for at‑risk material flows.
-
Prioritize product differentiation where value capture is highest: foldable and flexible form‑factors, privacy displays and adaptive refresh technologies offer premium ASP pathways; sequence launches to supplier readiness defined in our capacity tracker.
-
Use M&A selectively to secure IP or accelerate plant conversion capabilities — not merely to chase capacity — given the measured market growth rate implied by the 5.19% CAGR.
Closing: where PW Consulting adds unique value
In an environment where technology transitions, material constraints and policy actions all interact to reshape supplier economics, superficial forecasts are insufficient. PW Consulting’s Worldwide Smartphone Panel Market report combines a rigorously audited top‑down macro model with granular supply chain mapping, vendor intelligence and scenario playbooks that translate projections into decisions. The 5.19% CAGR and the headline market trajectory are the starting point; our report shows how that growth plays out in supplier leverage, cost exposure and product timing — and it prescribes pragmatic moves executives should make in 2026 to convert insight into durable advantage.
For the detailed region × technology splits, supplier‑level revenue allocations, the interactive capacity map and editable scenario models, please visit the full report page on PW Consulting’s website and contact our advisory team to schedule a briefing. The executive window to re‑negotiate supplier commitments and lock material hedges for 2026 is narrow — the right data, executed now, materially alters outcomes for the remainder of the forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Smartphone Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com