

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Pharma‑Grade Ibrutinib Market to Grow at a 3.88% CAGR Through 2032, Fueling New Oncology Opportunities

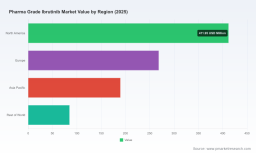
Worldwide Pharma Grade Ibrutinib Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study, Worldwide Pharma Grade Ibrutinib Market (base year 2025), delivers an actionable intelligence package designed to support board‑level and commercial teams preparing for the decisive 2026 planning cycle. Our analysis synthesizes historical performance (2020–2025) with a seven‑year forecast (2026–2032), quantifying a sector that expanded materially through 2025 and is projected to continue growing at a mid‑single digit compound annual growth rate (CAGR) of 3.88% over the forecast window.
Worldwide Pharma Grade Ibrutinib Market
Key macro checkpoints from the report include a clearly quantified market trajectory: a recovery and expansion phase through 2025, a market size that passes the USD 1 billion threshold in 2026, and a forecast that reaches just over USD 1.24 billion by 2032 under our baseline assumptions. These headline figures frame the commercial choices that matter in 2026 — pricing strategies, supply‑chain investments, regulatory positioning, and deal timing.
Worldwide Pharma Grade Ibrutinib Market
Why this matters for 2026 decisions
-
Policy and payer dynamics are shifting cost and access calculus. Under new U.S. Medicare Part D negotiation rules, the maximum fair price negotiated for a 30‑day supply will materially compress list‑price dynamics starting in 2026. This changes short‑term revenue optics for originators and alters the commercial leverage available to payers and hospital systems.
Worldwide Pharma Grade Ibrutinib Market -
The patent and exclusivity calendar is a strategic pivot: composition‑of‑matter expiry windows and staggered exclusivities across jurisdictions create distinct windows of vulnerability and opportunity. While some jurisdictions see earlier patent lapses, other patent layers extend exclusivity in key markets — resulting in asynchronous generic pressure that requires bespoke regional strategies rather than one‑size‑fits‑all responses.
-
Clinical innovation — including late‑stage data presented in 2025 — has the potential to reshape treatment duration and combination approaches. Results from major trials that compare fixed‑duration combination regimens versus continuous therapy will drive prescribing behaviour, indirectly affecting unit volume, product mix, and formulary negotiations.
-
Supplier dynamics remain a core source of commercial risk: a concentrated set of manufacturers and API suppliers dominate supply capacity, and transaction‑based API pricing exhibits wide bands depending on volume and destination market. Tactical sourcing and contractual resilience are therefore business‑critical.
What the report delivers — practical, ready‑to‑use outputs
We built the study to be operational for commercial, manufacturing, and corporate development teams. Deliverables include:
- Granular topline market model with historical and forecast volumes and revenues (company‑grade inputs and sensitivity levers).
- Scenario toolkits that stress test pricing, formulary access, and therapeutic‑strategy shifts (fixed‑duration combos versus continuous use).
- Regulatory and IP timeline maps across major jurisdictions, including early‑warning indicators for patent challenges and pediatric exclusivity implications.
- Supply‑chain heatmaps and API sourcing playbooks that identify single‑point risks, qualification hurdles, and remediation steps for capacity shortfalls.
- A competitive intelligence library with strategic profiles of innovators, large generics, and specialist API suppliers — calibrated to support M&A, licensing, and tender strategies.
- Commercial playbooks for originators, generic entrants, and contract manufacturers — covering launch sequencing, pricing governance, and payer engagement templates.
Competitive landscape: what to watch
The market structure is asymmetric: a small group of incumbent innovator partners maintains a dominant commercial presence, while a broad ecosystem of generics and API producers — largely headquartered in India and China, together with selected European suppliers — supply downstream customers and regional markets. Market concentration metrics in the report underscore this reality, with the top three and top five players capturing a meaningful majority share of the market value pool, elevating both competitive intensity and strategic fragility.
Practical takeaways on core players:
-
Janssen Pharmaceuticals (Johnson & Johnson) and Pharmacyclics (AbbVie): as co‑developers and commercializers of the branded product, they remain the reference commercial and clinical benchmark. Recent label updates expanding oral suspension use and late‑breaking Phase 3 data presented at a leading hematology meeting in 2025 are immediate inputs to medical affairs and payer engagements in 2026.
-
Large multinational generics and vertically integrated API suppliers (several headquartered in India and China): these firms are positioned to supply volume demand when and where regulatory pathways open. The market has a robust set of potential generic suppliers, some with tentative approvals in relevant jurisdictions. Their role in compressing prices and servicing non‑originator channels is a structural factor for any 2026 commercial plan.
-
Specialist API manufacturers in Europe and Asia serve both originator and generic value chains. Transaction data indicate significant variability in kilogram‑level pricing by destination and lot size; careful contractual design is required to lock in competitive input costs and continuity of supply.
Recent developments that change strategic math
-
Regulatory movement in 2025 includes a tentative approval for a generic entrant in mid‑2025, and a late‑2025 presentation of pivotal Phase 3 data comparing fixed‑duration combination therapy versus continuous treatment. Both developments have near‑term implications for formulary decisions and long‑term implications for addressable patient‑year demand.
-
Policy actions affecting reimbursement levels from 2026 materially alter price and access negotiations in the U.S., shifting net revenues and prompting payers to accelerate value‑based contracting pilots.
-
Jurisdictional disparities in patent expiry dates — with some local patents lapsing earlier than in the U.S. — mean regionally tailored generic entry is likely. Companies must therefore coordinate regulatory, commercial, and manufacturing plans by country rather than by product alone.
Strategic implications for 2026 (recommended priorities)
-
Re‑balance pricing and access playbooks to reflect negotiated payer ceilings and the prospect of staggered generic entry. Short‑term list price preservation without payer value propositions will erode net revenue more quickly than in prior cycles.
-
Prioritize supply‑chain resilience: dual‑sourcing of API, contractual capacity reservations with key manufacturers, and strategic inventory buffering are inexpensive compared with the cost of a supply disruption in high‑value oncology portfolios.
-
Invest in clinical differentiators and real‑world evidence that defend premium positioning. Evidence of reduced duration-of‑therapy, improved tolerability, or superior health‑economic outcomes materially improves negotiating leverage with payers.
-
Design regionally differentiated launch and defense strategies. Patent timelines and local regulatory landscapes require tailored market entry sequencing for generics and bespoke contracting approaches for originators.
-
Use scenario modelling to set M&A and licensing thresholds. The report’s integrated financial scenarios quantify value uplift from acquiring manufacturing capacity or securing long‑term API contracts versus pursuing late‑stage commercial rights.
Three scenarios to include in your 2026 planning
-
Baseline (PW Consulting central): Moderate growth consistent with the study’s CAGR, steady uptake driven by existing indications and incremental label/formulation improvements; conservative assumptions on generic timing in major markets.
-
Upside: Clinical data favoring fixed‑duration combination regimens accelerates patient throughput and channel uptake; originator retains pricing power through compelling HEOR; selective payers accept premium access in exchange for defined outcomes.
-
Downside: Earlier‑than‑expected regional generic entry and aggressive price competition in secondary markets compress volume value; supply overcapacity depresses API prices; payers escalate demand for rebates and outcomes guarantees.
How PW Consulting can accelerate your 2026 playbook
Clients engaging with our team receive not only the full market model and segmentation module, but also tailored execution support: rapid due‑diligence workstreams, procurement negotiation scripts, payer‑value packages, and an acquisition target short‑list with quantified synergies. The public briefing here intentionally omits the granular regional and application split tables — those are included in the full report and associated modelling files so that your commercial and corporate teams can run proprietary scenarios with confidence.
For teams preparing 2026 budgets, the imperative is clear: align clinical development, manufacturing commitments, and commercial investments around multiple plausible futures. The headlines — a market that clears USD 1 billion in 2026 and a steady mid‑single digit CAGR through 2032 — define the envelope. The real value is in the detail: the timing of patent cliffs by country, supplier concentration by dosage and purity grade, and payer rebate dynamics — all of which we map and quantify in the full study.
Next steps
Access to the full dataset, model files, and our scenario workshop calendar is available through PW Consulting’s report portal. If your 2026 plan depends on pragmatic choices around pricing, supply resilience, or M&A, the report provides the templates and the calibrated intelligence to act decisively.
For detailed analysis of this topic, please visit the official page: Worldwide Pharma Grade Ibrutinib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com