

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Chemical Industry DCS Market to Reach USD 9,469.96 Million by 2032 at a 5.5% CAGR — Asia‑Pacific Leads with USD 2,650 Million

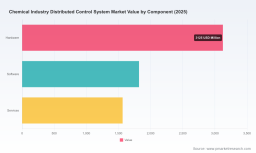
Worldwide Chemical Industry Distributed Control System Market: Strategic Imperatives for 2026
PW Consulting’s latest market research — Worldwide Chemical Industry Distributed Control System (DCS) Market — provides a practical, decision-ready intelligence package for senior executives planning capital allocation, digital transformation, and vendor strategy in 2026. Built on a base year of 2025 with historical coverage from 2020–2025 and a detailed forecast through 2032, the study projects a steadily expanding market at a compound annual growth rate (CAGR) of 5.5%. The global DCS market for chemical applications climbs from a 2025 baseline into a multi-billion USD opportunity by 2032, reflecting resilient demand for modernization, safety upgrades, and software-enabled operational transformation.
Worldwide Chemical Industry Distributed Control System Market
Why this report matters for 2026 decisions
-
Capital planning under scrutiny: With tighter capital discipline across chemicals, the report translates technology choices into multi-year CAPEX/OPEX scenarios that executives can use to prioritize retrofit vs. greenfield investments.
Worldwide Chemical Industry Distributed Control System Market -
Vendor selection informed by product roadmaps: The research evaluates how recent supplier innovations — especially the shift to software-defined DCS (SDA), AI-enabled operations, and open communications — change long-term total cost of ownership and upgrade pathways.
Worldwide Chemical Industry Distributed Control System Market -
Regulatory and compliance risk mitigation: The analysis links evolving environmental and process-regulatory drivers to control-system requirements, helping compliance, HSE and operations leaders align upgrade schedules with enforceable deadlines.
-
Service and lifecycle strategy optimization: As service revenue and long-term support emerge as strategic differentiators, procurement and aftermarket teams get actionable playbooks for contracting and service-level design.
High‑level market trajectory and what it means
After a steady recovery in the early 2020s, the DCS market for chemical industries is on an upward path. Our model records a clear step-up between 2023 and 2025 and forecasts continued growth into the 2030s. This trajectory is driven by a combination of legacy-system replacement, digitalization initiatives, and the rise of software-centric architectures that reframe control-system economics. For 2026 specifically, companies that move from exploratory pilots to scaled modernization programs will capture disproportionate operational and sustainability benefits.
Key technology and commercial trends shaping supplier strategies
-
Software‑defined automation (SDA) is the inflection point. Several leading vendors have introduced SDA-capable products in late 2025–early 2026, shifting the competitive battleground from hardware-centric upgrades to software portability, subscription models, and faster functional updates.
-
Open standards and field-device interoperability: Enhanced OPC UA support and improved field integration reduce integration risk and accelerate modernization timelines for mixed-vendor sites.
-
AI and autonomous operations: Suppliers are embedding analytics and AI for predictive maintenance, process optimization, and autonomous control loops — creating new value streams but also new governance needs.
-
Cybersecurity embedded in product lifecycles: With regulatory pressure and higher risk profiles, buyers are demanding security-by-design features, continuous patching paths, and clear incident-response commitments as part of DCS procurements.
-
Services as strategic differentiator: Lifecycle services, migration pathways, and cloud-enabled monitoring are becoming as important as the initial DCS purchase.
Competitive landscape — who’s advancing and how
The competitive map is evolving rapidly as legacy suppliers and challengers race to translate R&D into commercial SDA offerings, integrated services, and cloud-enabled operational suites. Our assessment of vendor strategies highlights how product roadmaps and go‑to‑market approaches will determine share shifts in 2026.
-
Emerson Electric Co. (United States) — Strong in batch and complex chemical reactions, the supplier’s DeltaV platform has been extended with the latest software-defined release in early 2026. The upgrade emphasizes operational intelligence, improved cybersecurity, and lower automation lifecycle costs — positioning Emerson for customers prioritizing quality control in complex processing.
-
Schneider Electric SE (France) — With a public 2026 launch of an open EcoStruxure Foxboro Software‑Defined Automation offering, Schneider is pushing into flexible, software-first DCS deployments that favor modular, upgradeable estates and faster functional innovation.
-
ABB Ltd. (Switzerland) — Incremental product upgrades emphasize extended automation functionality, OPC UA integration, and better field-device support — appeals to plants focused on modernization without wholesale platform replacement.
-
Yokogawa Electric Corporation (Japan) — The CENTUM VP line continues to target autonomous operations and long-term reliability, making it a compelling option for operators prioritizing lifecycle stability and sustained support.
-
Honeywell, Siemens, Rockwell, Mitsubishi, Azbil, Hitachi — Each vendor is pursuing a mix of modernization, AI, safety integration, and services plays, with regional strengths and differing migration strategies for legacy estate owners.
Recent product releases and upgrades across these vendors validate a market transition: 2026 is the year many roadmaps become deployable propositions. Buyers must therefore treat vendor announcements as the starting point for commercial diligence, not the end.
Regulatory and operational catalysts to watch in 2026
-
Environmental regulation is reshaping process constraints. For example, phasedowns and restrictions on certain high‑GWP process chemicals have knock‑on effects for refrigeration, thermal management, and ancillary process controls — requiring plant teams to re-evaluate equipment and control requirements in their modernization plans.
-
Process safety and HSE regimes increasingly expect integrated control-system support for safety instrumented functions, incident reporting, and compliance workflows.
-
Corporate sustainability targets are pushing operations teams to favor upgrades that enable energy optimization and fugitive-emission monitoring, raising the priority of DCS upgrades that include continuous monitoring and analytics.
What the PW Consulting report delivers — practical, executable content
-
Proprietary market model and forecast (2026–2032) with scenario sensitivity to CAPEX cycles, commodity-price shocks, and regulatory shifts.
-
Technology deep dives that map functional capabilities (SDA, AI/analytics, field integration, cybersecurity) to typical chemical plant architectures.
-
Vendor scorecards and product-positioning matrices, including roadmap assessments and commercialization timelines.
-
Commercial templates: RFP frameworks, contract clauses for lifecycle support and security, and procurement negotiation playbooks.
-
CapEx/Opex models and ROI calculators tailored for greenfield and retrofit scenarios (designed for CFO and plant‑ops dialogue).
-
Operational playbooks and 90/180/360‑day migration plans for prioritized site rollouts.
-
Regulatory impact analysis focusing on how process-related environmental measures affect control-system specifications and compliance timelines.
-
Deal screening framework and M&A playbook for technology acquirers and PE sponsors evaluating DCS-capable targets.
Practical 90‑day executive playbook for 2026
-
Immediate audit: Conduct a rapid inventory of DCS assets, versions, and end-of-support dates across the estate; identify safety‑critical and production‑critical sites.
-
Risk triage: Perform a cybersecurity and compliance gap assessment aligned to current regulatory milestones and the plant’s sustainability commitments.
-
Vendor shortlisting: Use a two-tier evaluation — (1) technical fit for critical sites, and (2) commercial fit for lifecycle cost and service delivery; prioritize vendors that demonstrate SDA roadmaps and clear migration paths.
-
Pilot and scale: Run a 3–6 month pilot to validate SDA and AI capabilities on a representative unit; use pilot outcomes to de-risk capital allocation for broader rollouts.
-
Contract architecture: Negotiate multi-year service agreements with performance KPIs, version-update commitments, and cybersecurity SLAs to lock in total cost and minimize operational disruption risk.
How PW Consulting helps
We combine market modeling with hands-on operational playbooks and vendor due diligence so that 2026 budget cycles and transformation programs are rooted in the likely, not the aspirational. Our clients use the report to accelerate vendor selection, structure financing for multi-year modernization programs, and reduce execution risk when migrating complex chemical processing assets to next‑generation control systems.
To access the complete dataset, detailed segmentation, vendor scoring matrices and downloadable capex/opex tools — or to schedule a tailored executive briefing for your leadership team — visit PW Consulting’s Worldwide Chemical Industry Distributed Control System Market report page. The public summary outlines key takeaways; the full report unlocks the proprietary inputs and step‑by‑step playbooks that can materially alter a 2026 investment decision.
For detailed analysis of this topic, please visit the official page: Worldwide Chemical Industry Distributed Control System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com