

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Aneurysm Coiling Market to Expand at a Robust 6.91% CAGR Through 2032

Worldwide Aneurysm Coiling Market 2026: Strategic Imperatives from PW Consulting’s Latest Analysis
Executive summary
PW Consulting’s new Worldwide Aneurysm Coiling Market report uses 2025 as the base year to deliver actionable strategic guidance for life‑science executives, payers, and hospital systems planning through 2032. At the consolidated market level, aneurysm coiling recorded robust expansion through 2020–2025 and reached an estimated USD 1,436.45 Million in 2025. Our proprietary forecast projects a 6.91% compound annual growth rate (CAGR) for the 2026–2032 period, with the market evolving to our long‑range estimate in 2032. This trajectory reflects a mix of technology renewal, regulatory milestones, shifting care settings, and persistent concentration among a small number of incumbent players.
Worldwide Aneurysm Coiling Market
Why this report matters for 2026 decision cycles
-
Timing for portfolio and M&A decisions: 2026 represents a critical inflection point — new product approvals and commercial launches anticipated in early‑to‑mid 2026 will reshape competitive dynamics. Our report quantifies the opportunity window and models acquisition scenarios that preserve integration upside while accounting for regulatory and reimbursement risk.
Worldwide Aneurysm Coiling Market -
Capital allocation and manufacturing scale: with a mid‑to‑high single‑digit CAGR to 2032, capital planners should balance capacity expansion against product lifecycle timing. The report provides stress‑tested volume scenarios tied to launch timing and regional adoption curves so manufacturing and supply‑chain investments can be paced to demand.
Worldwide Aneurysm Coiling Market -
Go‑to‑market optimization for new entrants: for innovators planning US market entry, our assessment translates clinical differentiation into commercial levers (pricing, evidence generation, channel strategies) that materially affect payback timelines.
-
Reimbursement and hospital economics: the report embeds current reimbursement benchmarks and models how changes to physician and DRG payments impact provider incentives for coiling vs. alternative therapies, informing contracting and value‑proposition design.
What’s in the report — practical, decision‑ready intelligence
We designed this study to be used by deal teams, product leaders, and market access strategists. The deliverables include:
-
Proprietary market model (2020–2032) with scenario functionality — baseline, conservative, and accelerated uptake pathways — enabling quick re‑runs under alternative regulatory or reimbursement outcomes.
-
Commercial playbooks detailing channel strategies, hospital contracting templates, and differentiated evidence plans (real‑world data, registry design, key opinion leader engagement) tied to time‑to‑value.
-
Competitor and pipeline tracker with strategic profiles for leading manufacturers, mapped against product attributes, regulatory status, and historical M&A activity.
-
Regulatory and reimbursement intelligence pack — jurisdictional decision trees, codification maps, and an assessment of payment levers that drive adoption in hospital and ambulatory settings.
-
Actionable M&A scorecards and valuation sensitivities calibrated to the aneurysm coiling market’s concentration and competitive dynamics.
Market structure and concentration — read the signals
The aneurysm coiling market remains highly concentrated, with the top three firms commanding the majority share and the top five accounting for nearly nine tenths of market value, according to our CR3 and CR5 metrics. High concentration creates both barriers and opportunities: incumbents benefit from scale, established hospital relationships, and integrated neurovascular portfolios, while well‑positioned challengers can win by targeting underserved procedural niches, differentiated clinical evidence, and nimble commercial models.
Competitive landscape — strategic implications for 2026
Our competitive analysis profiles the major participants and highlights how recent moves change the strategic calculus for 2026:
-
Medtronic — Leverages a broad neurovascular franchise and a deep installed base. For Medtronic, the priority is defending share while extracting margin through product line extensions and bundled clinical solutions.
-
Stryker — Competes through strong clinician relationships and product breadth. Their strategy will likely emphasize procedural efficiency and training programs to preserve OR preference.
-
Terumo Neuro (MicroVention) — Pursues a full portfolio approach with technical breadth across coil geometries. Differentiation will come from device ergonomics and physician workflow integration.
-
Penumbra — Focuses on system‑level solutions and newer coil platforms. Expect continued investment in complementary technologies that extend treatment algorithms.
-
Johnson & Johnson MedTech (Cerenovus) — Combines implant performance claims with extensive clinical support; strategic emphasis on integrated therapy suites is likely as hospitals consolidate purchasing.
-
Regional and emerging specialists (Balt Group, Phenox/Wallaby Medical, Kaneka, MicroPort, among others) — These firms target narrow, tactical opportunities: differentiated coil materials, niche geographies, or rapid regulatory routes. Their activity can accelerate localized price compression and influence adoption curves.
-
Neuravention — A near‑term disruptor to watch: the company has signaled plans for a US regulatory submission in early 2026 and potential commercialization or strategic sale within the year. For incumbents, this raises tactical decisions around defensive product roadmaps and potential pre‑emptive partnerships.
Regulatory and reimbursement dynamics shaping 2026 strategies
Recent regulatory milestones have immediate commercial consequences. For example, Kaneka’s EU MDR certification and subsequent European launch in late 2025 underscore how regulatory timing directly unlocks revenue channels and shifts regional competitive intensity. In the US, anticipated submissions and approvals in 2026 could reallocate attention and investment toward payer evidence generation.
On the reimbursement front, clinician and hospital economics continue to be critical adoption levers. Current coding and payment benchmarks — including national physician payment levels for the primary coiling CPT and hospital DRG payments for complicated ruptured aneurysm cases — produce identifiable incentives and disincentives that affect procedure mix, site‑of‑care decisions, and contracting priorities. Our report translates these payment parameters into adoption elasticity estimates and hospital margin sensitivity analyses.
Strategic playbook — five moves for 2026
-
Prioritize regulatory sequencing and evidence plans: For companies with pending filings, align clinical data milestones with commercial launch readiness to compress time‑to‑revenue.
-
Targeted M&A and alliance frameworks: Use acquisition scorecards to identify bolt‑on targets that close product gaps or accelerate market access in priority geographies without overstretching capex.
-
Value‑based contracting pilots: With predictable episode costs in neurovascular care, experiment with risk‑sharing for high‑volume centers to build durable preferred relationships.
-
Channel and site‑of‑care optimization: Reassess the ambulatory vs. hospital mix and invest selectively in OR/IR training and logistics to reduce total procedural cost and improve throughput.
-
Differentiation through evidence and experience: Beyond device performance, bundle outcome measurement, patient follow‑up, and digital support to lock in post‑procedure data flows and payer interest.
How PW Consulting supports your 2026 playbook
Our study is built as a practical decision tool, not just a market narrative. Clients receive the model with configurable levers (regulatory timing, pricing, adoption curves), a competitive heat map updated with recent launches and filings, and executable templates for payer negotiation and hospital contracting. For deal teams, we include sensitivity analyses that convert market share shifts into valuation impacts under multiple integration and cannibalization assumptions.
Next steps — where to find the full intelligence
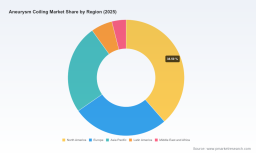
This release is a condensed strategic overview intended to demonstrate the report’s depth and practical orientation. To preserve the utility of the report as a decision engine, we have intentionally withheld core subsegment tables and granular regional and product‑type figures from this release. The full report contains detailed breakdowns by product type, region, end‑user, price and reimbursement matrices, competitor market shares, and downloadable model files that allow you to run custom scenarios aligned to your strategic questions.
For teams making capital, commercial, or regulatory decisions in 2026, PW Consulting’s Worldwide Aneurysm Coiling Market report provides the evidence base, financial modeling, and playbooks necessary to convert market trends into defensible action. Contact our client services team to arrange a model walkthrough, competitive deep‑dive, or tailored advisory engagement.
For detailed analysis of this topic, please visit the official page: Worldwide Aneurysm Coiling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com