

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
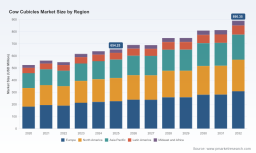
PW Consulting: Cow Cubicles Market to Reach USD 890.35 Million by 2032, Expanding at a 4.5% CAGR

Cow Cubicles Market 2026: Strategic Briefing for Corporate Decision‑Makers
PW Consulting’s latest Cow Cubicles Market report — built on a five‑year historical baseline and a seven‑year forecast horizon — delivers the practical intelligence senior leaders need to set winning 2026 strategies. The market for cow cubicles has demonstrated resilient expansion through 2020–2025, rising from roughly USD 525 million in 2020 to about USD 654 million in 2025, and our modelling shows continued momentum into the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 4.5%, reaching roughly USD 890 million by 2032. This briefing distils the report’s strategic value for capital allocation, product roadmaps, M&A screening, and procurement optimization — while reserving the full segmented datasets for the source report.
Cow Cubicles Market
Why this report matters for 2026 decisions
-
Capital discipline: With growth steady but moderate, investment decisions in 2026 must prioritize modularity and near‑term payback. Our report translates market growth into scenarioized capital requirements and payback timelines for common retrofit and greenfield projects.
Cow Cubicles Market -
Regulatory compliance as a growth driver: Emerging and active regulations on stocking density, stall design, and animal welfare are accelerating demand for retrofit and redesign services. Planning for compliance windows is now part of procurement strategy, not an afterthought.
Cow Cubicles Market -
Fragmented supplier landscape: Market concentration metrics indicate a fragmented ecosystem, with room for regional champions and differentiated OEMs. That fragmentation creates opportunities for targeted M&A, distribution partnerships, and specialized aftermarket services.
-
Margin capture through services: As commoditized product margins compress, aftermarket services (installation, optimisation, sensorisation) are where electronics, data, and consultancy can materially improve returns.
What PW Consulting’s report contains — practical and actionable
-
Financial and scenario models: Templated NPV/IRR models and sensitivity analyses that translate market growth, construction cost benchmarks, and regulation timelines into investment outcomes for retrofit vs. new builds.
-
Procurement playbook: Step‑by‑step sourcing and contracting checklist tailored to freestall and flexible cubicle projects, including procurement levers, risk allocation templates, and a supplier scorecard methodology.
-
Technical installation guidance: A practical installation roadmap covering site assessment, layout optimisation, ergonomics for major cow types, and typical labour and equipment inputs — designed to shorten deployment cycles and reduce rework.
-
Regulatory mapping and compliance calendar: A prioritized regulatory tracker and compliance-impact matrix (including national codes and influential industry guidelines) that feed directly into capital planning calendars.
-
Market access and commercialization playbook: Segmented GTM options (OEM, dealer, project integrator) with recommended margin structures and channel incentives to accelerate penetration in target geographies and farm sizes.
-
Technology and materials roadmaps: Comparative tradeoffs between metal and flexible systems, bedding and matting solutions, and sensor integration options — with procurement and lifecycle cost guidance.
Industry dynamics shaping near‑term demand
-
Regulatory deadlines are reshaping capex timelines. Examples we model include stocking‑density rules scheduled in some markets and national guidance mandating one free‑stall per animal in others; these create non‑linear bursts of retrofit demand as compliance windows approach.
-
Design standards and animal welfare guidelines are elevating technical requirements for cubicle dimensions and brisket/neck rail configurations. Benchmarks and recommendations from established advisory bodies are now default inputs to specification sheets, and must be built into procurement and QA processes.
-
Build‑cost benchmarks are a practical lever to prioritize projects: using standard construction and component cost references (for example, industry estimates for per‑stall construction and common partition costs), our TCO models show how small design choices can swing payback by multiple months.
-
Operational pressures (labour, herd productivity) are increasing demand for ergonomically designed stalls that demonstrably improve lying times and reduce soiling — outcomes that are easier to monetise in total‑cost models than simple unit price comparisons.
Competitive landscape — who matters and why
The cow cubicles market remains populated by specialist manufacturers and regional dealers. Rather than a winner‑takes‑all dynamic, we see a landscape where product differentiation, evidence‑based design claims, and strong dealer networks determine success.
-
O'Donovan Engineering (Cork, Ireland) — Known for proprietary Super Loop and Cantilever designs that emphasise cow comfort and reduced soiling. Their engineering approach makes them a compelling partner for premium retrofit programmes.
-
Wilson Agri (UK) — Developer of the C50 and Cowcoon systems, with a research-led product portfolio focused on high neck‑rail designs and hybrid stalls. Their product positioning suits technical specifications where welfare metrics are prioritized.
-
Easyfix (Ireland) — Specialist in flexible freestall systems that align with natural cow movement; recent October 2025 updates to their installation documentation improve deployability and reduce on‑site variation.
-
Kapoor Mats (India) — Cost‑competitive flexible cubicle and mat supplier, anchored in material innovation and aftermarket matting solutions for emerging and high‑volume markets.
-
Delmer Group (Italy/India) — Focused on space‑saving free‑stall systems and flexible designs for cows and buffaloes; appeals to projects where floor space optimisation and rest period extension matter.
-
CowPlan Ltd (UK) — Dealer and integrator with deep local design expertise; serves as an example of how distribution partners can scale manufacturer solutions in regional markets.
These firms illustrate the market archetypes we profile in the report: engineering‑led OEMs, research‑anchored designers, flexible‑product specialists, low‑cost mat competitors, and dealer/integrator networks. Our proprietary supplier assessment rates each archetype across design robustness, installation support, warranty terms, and aftermarket services.
Recent developments with operational implications
-
Easyfix’s updated installation manuals (Oct 2025) reduce on‑site variability for flexible designs and accelerate commissioning timelines — a small documentation change with outsized implementation benefits for large retrofit programmes.
-
Lactanet’s housing guidance (published and active) raises the bar on free‑stall layout and adaptability — this is already influencing specification language in competitive tender documents and public procurement lists.
-
Cost and design benchmarks (industry building cost estimates and component benchmarks) continue to serve as the practical inputs for capital modelling. Our report embeds these benchmarks into the financial templates to standardise decision criteria across projects.
How to use the report in 2026 — five immediate actions
-
Map compliance calendars to capex windows. Use the regulatory tracker to sequence retrofit spend so that you prioritise projects with the shortest compliance lead times and highest risk exposure.
-
Run two portfolio tests: (1) a conservative retrofit scenario targeting regulatory compliance and immediate welfare gains; (2) an aggressive growth scenario capturing productivity improvements from premium systems and sensorisation. Compare IRRs using our templates.
-
Shift procurement KPIs beyond unit price. Include installation uptime, warranty realisation rates, and sensor‑data integration capability as measurable contract KPIs.
-
Pilot one sensor‑enabled cubicle roll‑out to quantify welfare and productivity benefits. Use short pilots to create internal commercial cases for scaled investment and to validate supplier claims.
-
Screen regional M&A targets using the supplier scorecard. Identify candidates that fill distribution gaps, add material competence, or provide immediate aftermarket revenue streams.
What we intentionally withhold in this briefing
To maintain the investigative value of the full market study and to respect the “trailer” purpose of this briefing, we have provided high‑level market sizing, growth trajectory, and competitive themes, but we have not published the report’s detailed segmented revenue breakdowns, per‑region or per‑application numeric slices, or the fully scored supplier financials. Those detailed splits and scorecards are available in the source report and web portal, where subscribers can run custom filters and download the financial models.
Conclusion and next steps
The Cow Cubicles Market is maturing into a market where regulatory timing, installation capability, and service economics trump unit price. For 2026, the most consequential decisions are those that synchronise compliance needs, deployment capabilities, and after‑sales monetisation. PW Consulting’s Cow Cubicles Market report is designed to convert the market’s steady growth trajectory and regulatory inflection points into a concrete, executable agenda for OEMs, integrators, farm operators, and investors.
For the full segmented datasets, supplier scorecards, downloadable financial models, and the compliance calendar with market‑specific timelines, visit PW Consulting’s Cow Cubicles Market report page to access the complete study and supporting tools.
For detailed analysis of this topic, please visit the official page: Cow Cubicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com