

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Electric Ambulance Stretchers Market Surges to USD 560.0 Million in 2025

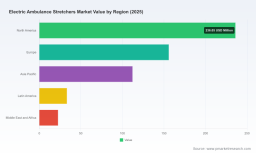
Worldwide Electric Ambulance Stretchers Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Electric Ambulance Stretchers market positions this niche as a rapidly professionalizing segment of emergency medical services (EMS) and hospital logistics. The market is valued at approximately USD 560 million in the report’s base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 8.31% through the 2026–2032 forecast period, approaching roughly USD 980 million by 2032. This trajectory reflects durable demand drivers—fleet modernization, operator ergonomics, lifecycle cost awareness, and faster adoption of electrified handling systems across pre‑hospital and in‑facility use cases.
Worldwide Electric Ambulance Stretchers Market
Why this report matters for 2026 strategy
- Timing: 2026 is a pivot year for many procurement cycles. Public agencies and private EMS operators are transitioning from pilot programs to large‑scale fleet refreshes. The report translates macro momentum into actionable timing for RFPs, pilot expansions, and phased rollouts.
- Risk mitigation: Electric stretchers intersect medical device standards, vehicle crash testing, battery safety, and procurement rules. Our analysis synthesizes regulatory nuance—both risks and fast‑tracks (e.g., exemptions relevant in Class II device pathways)—so buyers and OEMs can align compliance and go‑to‑market plans without last‑minute surprises.
- Commercial insight: The report frames where margin and service opportunities are greatest (aftermarket contracts, financing/lease models, telematics-enabled fleet services), enabling CFOs and product leaders to prioritize investments that accelerate payback.
Market dynamics driving near‑term decisions
Three structural forces converge to sustain above‑market growth through 2032:
Worldwide Electric Ambulance Stretchers Market
- Operational ergonomics and workforce health: Health systems and EMS agencies are prioritizing devices that reduce manual handling injuries. Electrified lifting systems—whether hydraulic‑electric hybrids or fully electric platforms—are now measured not only by acquisition price but by injury reduction, absenteeism savings, and ergonomic KPIs integrated into total cost of ownership (TCO) models.
- Technology maturation and connectivity: Lithium‑ion battery platforms, modular removable battery systems, and increasingly common vehicle‑to‑equipment telematics enable predictive maintenance and fleet management. Connected cots and gurneys with load‑sensing, crash detection, and remote diagnostics transform one‑time equipment purchases into recurring service revenue streams for OEMs and distributors.
- Regulatory and procurement tailwinds: Standards such as SAE J3027 for dynamic crash testing, BS EN 1789, and electrical safety norms (IEC 60601‑1) continue to define minimum acceptability. In parallel, procurement channels—public schedules, large fleet contracts, and centralized buying groups—are professionalizing requirements, favoring vendors that demonstrate both compliance and supply chain resiliency.
Competitive landscape — what to watch in 2026
The market remains supplier‑led by established OEMs that combine durable mechanical platforms with emergent electronics and service capabilities. Our qualitative and quantitative benchmarking highlights three competitive archetypes:
Worldwide Electric Ambulance Stretchers Market
- Global OEM innovators: Firms that pair robust mechanical design with advanced connectivity and service contracts. These companies command trust in heavy‑duty ambulance applications and are frequently present on public procurement schedules and large national contracts.
- Regional specialists: European and Asia‑based manufacturers that differentiate on cost, compliance with local standards, and tailored ergonomic features for specific vehicle fleets and clinical workflows.
- Volume‑oriented suppliers: Producers focused on scalable manufacturing and aftermarket parts distribution, often competing on price and rapid lead times for emerging markets and private clinic segments.
Representative companies profiled in the study include market leaders known for connected and heavy‑duty models; long‑standing U.S. manufacturers with recent large fleet awards and updated product documentation; European innovators focused on hybrid hydraulic/electric assistance; and several Asia‑based producers supplying cost‑competitive, feature‑rich platforms suitable for both pre‑hospital and in‑facility use. Recent industry developments we track—major fleet contract awards, updated product manuals, and inclusion of multiple model lines in government‑run market surveys—underscore accelerating competitive differentiation around product validation and fleet‑scale deployment.
Regulatory, standards, and procurement considerations
Electric stretchers sit at the intersection of medical device and vehicle standards. Successful 2026 strategies will incorporate:
- Standards alignment: Mandatory testing regimes (dynamic crash performance, flammability, electrical safety) directly affect product acceptance in institutional procurements. Manufacturers that document compliance and provide transparent test artifacts gain a procurement edge.
- Regulatory nuance: Certain device classes benefit from streamlined premarket paths; however, product changes (e.g., integrated telemetry, higher energy battery packs) can trigger additional scrutiny. Our compliance playbook outlines triggers that change regulatory posture.
- Procurement channels: Large public tenders and schedule contracts remain the most efficient route to scale. Suppliers should calibrate commercial terms, warranty frameworks, and spare‑parts logistics to win multi‑year fleet agreements.
What the PW Consulting report delivers — pragmatic, executable chapters
PW Consulting’s report is engineered for use by C‑suite sponsors, product managers, procurement leads, and investor diligence teams. Key deliverables include:
- Market sizing and forecast model: A bottom‑up market model with historical (2020–2025) and forecast (2026–2032) streams, enabling scenario analysis under alternative adoption and replacement cycles.
- Strategic segmentation framework: An actionable segmentation that clarifies where growth, margin, and service opportunities reside—without divulging proprietary client level splits in this brief.
- Competitive benchmarking: Vendor profiles, product feature matrices (connectivity, battery architecture, load capacity, standards compliance), and go‑to‑market playbooks that highlight differentiation levers.
- Procurement and clinical adoption playbooks: RFP templates, technical requirement checklists, evaluation scoring systems, and TCO calculators tailored for EMS fleets and hospital procurement teams.
- Aftermarket and services roadmap: Business models and KPIs for field service networks, telematics subscriptions, and parts logistics to convert one‑time sales into annuity streams.
- Risk register and mitigation strategies: Supply chain, regulatory, and warranty risks with recommended controls and contract language to protect institutional buyers and suppliers alike.
Practical implications by function
- For product leaders: Prioritize modular battery systems, remote diagnostics, and ergonomics features that demonstrably lower operator injury costs. Roadmap investments should balance incremental hardware improvement with software‑enabled services.
- For procurement and operations: Move beyond sticker price evaluation to include lifecycle costs, fleet uptime guarantees, and spare‑parts availability. Use the report’s RFP and scoring templates to shorten procurement cycles and reduce post‑deployment surprises.
- For investors and corporate development teams: Assess target value not only on unit revenue but on serviceable addressable market for aftermarket parts, telematics subscription, and multi‑year maintenance contracts—areas that magnify enterprise value.
Research methodology and confidence
The study uses a blended approach: primary interviews with EMS leaders and OEM product teams, structured procurement data, government contract disclosures, and a bottom‑up market build using unit shipments, replacement cycles, and fleet sizing assumptions anchored to a 2025 base year. Historical data spans 2020–2025 and the forecast horizon is 2026–2032. Where public disclosure is limited, conservative assumptions and sensitivity testing quantify uncertainty bands, enabling robust decision scenarios.
Closing — how to use this briefing in 30/60/90 days
- 30 days: Use the report’s procurement checklist and technical scorecard to refine current RFPs or supplier shortlists.
- 60 days: Revisit product roadmaps and supplier negotiations with lifecycle cost insights and warranty language from the report’s contract playbook.
- 90 days: Launch pilot expansions or tender packages for fleet refreshes, leveraging the report’s market timing and vendor validation matrices to de‑risk scale deployments.
Next steps
This briefing outlines the macro trajectory and strategic choices that will define winners and losers in the electric ambulance stretcher market through 2026 and beyond. PW Consulting’s full report contains the detailed tables, segment breakouts, model workbooks, and proprietary vendor scoring that support procurement decisions, M&A diligence, and product strategy — information intentionally withheld here in order to preserve the report’s role as a practical decision tool.
To access the full report, interactive models, and tailored advisory support, please visit PW Consulting’s Worldwide Electric Ambulance Stretchers Market report page or contact our strategy team to schedule a findings workshop tailored to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Electric Ambulance Stretchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com