

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Cast Iron Manhole Covers Market to Rise from USD 4,575 Million in 2025 to USD 6,143 Million by 2032 at a 4.3% CAGR — Asia Pacific, Ductile Cast Iron and Municipal Infrastructure Lead While Top‑3 Hold Just 18.4%

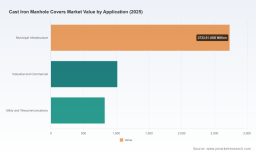
Worldwide Cast Iron Manhole Covers Market — Strategic Insights for 2026
PW Consulting today releases a strategic briefing drawn from our comprehensive market study, "Worldwide Cast Iron Manhole Covers Market (Base year: 2025)". Built for boardrooms, procurement teams, and infrastructure strategists, this release highlights the high‑value takeaways that should inform corporate decisions in 2026 — while reserving detailed segment-level figures for the full report.
Worldwide Cast Iron Manhole Covers Market
Executive snapshot: what senior leaders need to know
The global cast iron manhole covers market is on a steady growth trajectory. Our model shows the market expanding from a base of USD 4,575.0 Million in 2025 and tracking to approximately USD 6,143.02 Million by 2032, a compound annual growth rate (CAGR) of 4.3% across the 2026–2032 forecast window. This pace reflects resilient underlying demand from municipal and industrial infrastructure renewal, alongside incremental product upgrades driven by climate and load‑class considerations.
Worldwide Cast Iron Manhole Covers Market
Two structural characteristics matter for 2026 planning:
Worldwide Cast Iron Manhole Covers Market
- Fragmentation with opportunity: market concentration is low relative to many capital‑goods sectors (CR3 ~18.4%, CR5 ~26.5%), creating space for scale consolidation, regional champions and niche specialists.
- Input and regulatory pressure: raw‑material cost volatility and tightening standards are squeezing margin levers while creating differentiation opportunities for compliance‑led product offerings.
Why this report matters for your 2026 decisions
We designed the study as an actionable tool for executives who must make procurement, investment, and M&A decisions in 2026. The report translates macro projections into decision triggers across five priority agendas:
- Strategic sourcing and hedging: quantify exposure to scrap and steel price swings and evaluate localized production vs. import strategies.
- Capex and footprint optimization: identify the production-scaling inflection points where new lines or facility upgrades become economically viable.
- Product and service differentiation: prioritize investments in climate‑resilient designs, locking mechanisms and modular frames tied to regulatory compliance.
- M&A and partnership screening: apply our vendor scorecards and integration scenarios to accelerate capability acquisition with mitigated execution risk.
- Regulatory compliance and specification alignment: operationalize standards intelligence for faster bid wins on municipal and infrastructure contracts.
Key market drivers and 2026 implications
Our analysis synthesizes five dynamics that will shape winners and losers next year:
- Infrastructure renewals and urban expansion continue to underpin baseline demand. Urban drainage and heavy‑traffic applications sustain the core market.
- Regulatory frameworks: standards such as EN 124 (and national equivalents) remain binding for load classification, while jurisdictions like India enforce mandatory certifications (e.g., national BIS standards). Firms that align product portfolios and test data to these specifications shorten procurement cycles and raise tender hit rates.
- Raw material volatility: recent macro readings — for example, a US producer‑price index spike for cast iron scrap in early 2026 — underscore price and lead‑time instability. Steel mill capacity utilization trends observed through 2025 (roughly mid‑70s percent ranges) also imply intermittent supply tightness that can lift foundry costs. Buyers should anticipate short windows of purchasing advantage and build flexible sourcing clauses into contracts.
- Climate and resilience requirements are driving product innovation. Manufacturers that demonstrate storm‑resilience, tamper resistance and lifecycle cost benefits will command premium positioning in high‑value municipal contracts.
- Market fragmentation creates arbitrage for disciplined acquirers. Low CR3/CR5 values indicate a market where well‑executed roll‑ups or selective greenfield investments can quickly improve margin profiles through capacity rationalization and logistics optimization.
Competitive landscape — what we uncovered
The industry map includes a mix of long‑established foundries, regional exporters and global suppliers. Our competitive heatmap (summarized below) evaluates firms on four vectors: product breadth & certification, geographic reach, customization & engineering capability, and go‑to‑market strength.
- Established global players : Firms with multi‑region distribution and engineering depth maintain advantages on large municipal tenders and climate‑resilient product launches. These players are investing in product innovations (for example, clamp/hinge systems and storm‑resilient designs) that address extreme weather events.
- Regional specialists & exporters : Foundries with strong export networks and multiple production facilities can win on price and lead time for regional projects. Their success hinges on certification capabilities and adherence to target market standards.
- Emerging manufacturers : Nimble producers that focus on customization and rapid delivery are carving niches in industrial and specialized infrastructure segments, particularly where bespoke covers and branding are valued.
Representative firms profiled in our analysis include companies with strong municipal credentials, heavy‑traffic product portfolios and export footprints. Recent market developments we tracked signal ongoing innovation and market engagement activity — product introductions emphasizing climate resilience, targeted trade show participation to secure export pipeline, and new product updates from regional manufacturers.
What the full report contains (practical, usable deliverables)
PW Consulting’s full study is engineered as a toolkit for implementation, not just observation. Key deliverables include:
- Comprehensive demand forecast (2026–2032) with scenario‑based sensitivity testing and monthly/quarterly cadence for procurement planning.
- Complete segmentation by region, product type and application (detailed tables and interactive dashboards are included in the subscriber version — note: segment‑level values are available only in the full report).
- Supply‑chain mapping and cost‑to‑serve analysis: raw material exposure, foundry utilization scenarios, logistics costs and landed price matrices.
- Regulatory and standards matrix: side‑by‑side requirements, test standards and certification timelines for major markets.
- Competitive playbooks: vendor scorecards, SWOTs, and acquisition target shortlists with estimated synergies and integration risks.
- Go‑to‑market & product roadmaps: prioritized product enhancements (e.g., climate‑resistant clamps, locking systems, composite hybrid options), target customer segments and bid‑win strategies.
- Operational tools: procurement clauses to hedge raw‑material volatility, CAPEX decision calculators, and a ready‑to‑use M&A diligence checklist.
Actionable recommendations for 2026
Based on our analysis, PW Consulting recommends the following priorities for 2026 decision cycles:
- Lock in a dynamic sourcing strategy. Combine spot buying windows with index‑linked long‑term contracts to reduce exposure to scrap and steel price spikes.
- Invest selectively in product certification and testing labs. The ability to demonstrate EN and national standard compliance is a barrier to entry that yields measurable price premiums in tendered work.
- Pursue capability acquisitions with service‑line synergies. Look for small regional foundries with export channels and certified product lines that can be integrated into your logistics network to reduce lead times.
- Accelerate climate‑resilient product lines. Municipalities and storm‑hardening programs will prioritize solutions that reduce lifecycle costs and maintenance frequency.
- Standardize a bid‑win playbook. Embed compliance checklists, test certificates and lifecycle‑cost calculators into your sales process to reduce tender response time and improve win rates.
How to use this intelligence
For corporate leaders, procurement heads and private‑equity sponsors, the study functions as both an early warning system and an execution guide. Use the headline projections and scenarios to stress test 2026 budgets and to create rolling three‑to‑five year supply plans. Use the vendor scorecards to prioritize conversations with potential partners in the first half of 2026. And use our CAPEX decision tools to determine whether to consolidate production, expand capacity, or pursue bolt‑on acquisitions.
Next steps
To access the complete set of segment figures, supplier scorecards and executable playbooks, request the PW Consulting report package. The full report contains the granular datasets and models required to convert the insights above into measurable savings, revenue capture and risk reduction in 2026 and beyond.
PW Consulting remains available to brief executive teams and boards on customized scenarios, M&A screening and procurement optimizations derived from the report. Contact our Industrial Materials and Infrastructure practice for tailored workshops and rapid‑deployment strategic plans.
For detailed analysis of this topic, please visit the official page: Worldwide Cast Iron Manhole Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com