

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 3D Scanning Wind Lidar Market to Reach USD 246.09 Million by 2032, Growing at 7.85% CAGR (2026–2032)

Worldwide 3D Scanning Wind LiDAR Market: Strategic Insights to Inform 2026 Decisions
PW Consulting today releases an executive briefing drawn from our forthcoming Worldwide 3D Scanning Wind LiDAR Market report (base year 2025). The briefing synthesizes market direction, supplier dynamics, regulatory inflection points, and practical decision frameworks to help executives — from asset owners and OEMs to investors and technology licensors — prioritize actions in 2026. The full report contains the granular segmentation, vendor scorecards, and procurement playbooks that underpin the recommendations below.
Worldwide 3D Scanning Wind Lidar Market
Market snapshot: a clear, investable growth trajectory
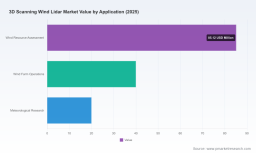
After steady expansion through the early 2020s, the 3D scanning wind LiDAR market reached an estimated USD 145.0 Million in 2025. Our modeling shows sustained growth over the coming decade, with a compound annual growth rate of 7.85% through the 2026–2032 forecast window and a projected market size above USD 240 Million by 2032. This trajectory reflects both accelerating deployment in complex offshore projects and rising penetration of scanning systems across wind farm lifecycle stages — from resource assessment to operational optimization and meteorological research.
Worldwide 3D Scanning Wind Lidar Market
Why this report matters for 2026 decision-makers
- Timing procurement and trials: With product refresh cycles shortening and independent IEC-type testing becoming a gating factor for commercial adoption, 2026 will be the year many operators decide whether to replace campaign-based lidar deployments with continuous or dual-lidar architectures. Our scenario analysis quantifies the value of earlier adoption against instrument cost, testing lag, and measurement-class risk.
- Vendor selection under uncertainty: Suppliers now differentiate on scanning modes, range, data fusion capabilities and integration with turbine control systems. We provide comparative frameworks that translate vendor specifications into operational KPIs (energy yield certainty, curtailment reduction, maintenance deferral) that CFOs can use in capex appraisals.
- Supply-chain resilience and component risk: Core optical sub-systems — notably eye-safe fiber lasers around 1550nm and advanced photodetectors — represent a concentrated set of upstream dependencies. Procurement strategies that account for lead times, second-source validation and qualification testing materially reduce deployment risk for large-scale projects.
What the PW Consulting report delivers — practical, transaction-ready content
We designed the report to be actionable rather than purely descriptive. Key deliverables include:
Worldwide 3D Scanning Wind Lidar Market
- Vendor diagnostic templates: standardized scorecards covering measurement validation, IEC-class evidence, service footprint, and software/data APIs.
- Procurement playbooks: bidding specifications, test-and-acceptance protocols, and contract clauses to protect against measurement drift and data loss.
- ROI and scenarios: multi-horizon financial models linking lidar configuration choices to IRR and levelized cost of energy (LCOE) sensitivity.
- Integration blueprints: recommended architectures for combining ground, nacelle, and floating buoy-mounted scanning data with SCADA and asset health systems.
- Risk matrices and mitigation plans: supplier concentration, component obsolescence, regulatory testing timelines, and create-ahead commissioning strategies.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three suppliers account for roughly one-third of global share while the top five approach half of the market. That structure creates space for both established vendors and focused challengers to win by specialization.
- Vaisala (Vantaa, Finland) — A mature portfolio player, Vaisala’s WindCube Scan line is positioned for large resource-assessment campaigns and offshore projects. Recent product updates announced in late 2025 indicate continued investment in performance and dual-scanner workflows that strengthen its appeal to utilities and large EPCs.
- ZX Lidars (United Kingdom) — ZX continues to push at the testing-and-classification frontier. The launch of a ground-based system in 2025 with independent IEC-class validation up to enhanced measurement heights signals their focus on compliance-driven procurement processes that many asset owners now require.
- Movelaser (Nanjing Movelaser Co., Ltd.) — A cost-competitive manufacturer offering programmable scanning modes and flexible deployment options. Its emphasis on software-driven configurability makes it a choice for developers seeking bespoke scanning strategies without heavy integration lift.
- Halo Photonics (Lumibird) — With coherent pulsed Doppler offerings, Halo (now within Lumibird’s portfolio) focuses on profiling and scanning performance for both onshore and offshore contexts, emphasizing stability in adverse conditions.
- ZATA (China) — Positioning around pulse-Doppler architectures, ZATA targets atmospheric profiling across a range of deployments, including rapid-installation campaigns for developers in emerging markets.
- Leonardo (Italy) — High-end lidar systems with roots in aviation and hazard detection, Leonardo’s SKIRON3D brings advanced capabilities for turbulence and gust monitoring that can be repurposed for high-consequence wind-energy sites.
- Windar Photonics (Denmark) — Focused on nacelle-mounted and scanning solutions integrated tightly with turbine OEM processes, Windar plays to the service and drivetrain optimization opportunity set.
Across these suppliers, differentiation is less about pure measurement range and more about validated accuracy, software maturity (data pipelines and analytics), global service networks, and demonstrable IEC-validated performance. For acquirers and partners, the practical question is which vendor reduces operational uncertainty fastest — and at what total cost of ownership.
Supply-chain, standards and technology dynamics
Three structural forces will govern competitive outcomes in 2026:
- Component concentration: Modern 3D scanning systems rely on a narrow set of high-spec fiber lasers (around 1550nm) and sophisticated photodetectors and optics. Procurement teams must assess supplier roadmaps for these sub-systems to avoid single-point failures and to secure upgrade paths.
- Standards and independent testing: Independent IEC-conformance testing has become a commercial differentiator. Buyers are increasingly requiring third-party classification to reduce measurement-risk in bankable resource assessments. Vendors securing early, documented test results gain faster adoption among risk-averse enterprise purchasers.
- Offshore and dual-lidar architectures: The growth in complex offshore projects is driving demand for 3D mapping and multi-lidar configurations that can capture spatial variability at turbine scale. Systems optimized for marine deployment, data fusion, and redundancy will command premiums.
Strategic actions for different stakeholders in 2026
- Asset owners / IPPs: Prioritize pilots that validate vendor performance against your IEC-class expectations and site-specific turbulence regimes. Use the report’s procurement templates to reduce legal and measurement risk and to build bankable datasets for financing.
- Turbine OEMs: Treat lidar vendors as technology partners rather than commodity suppliers. Co-development agreements for nacelle integration and predictive control use cases can create competitive differentiation in the OEM market.
- Investors & private equity: Look for companies with defensible positions across both hardware and data services. Businesses that combine validated instrumentation, scalable analytics, and service delivery networks are better positioned to convert recurring measurement contracts into high-margin annuities.
- Component suppliers: There is a near-term opportunity to lock in OEM and system integrator roadmaps by offering prioritized supply, qualification packages, and forward-compatibility roadmaps for fiber lasers and photonics modules.
Outlook and what to expect in 2026
We expect 2026 to be a pivotal year in which procurement moves from small-scale campaigns toward systemic integration of scanning LiDAR into asset lifecycles. Market participants who are proactive about testing, second-sourcing, and adopting data-centric procurement clauses will reduce execution risk and improve project economics. For those who delay, the cost of catch-up — both in measurement uncertainty and in missed optimization opportunities — will rise as competitors leverage richer three-dimensional datasets.
Next steps — how PW Consulting can help
Our full Worldwide 3D Scanning Wind LiDAR Market report (base year 2025) contains the granular segmentation, regional and deployment splits, end-use scenarios, vendor scorecards and downloadable procurement templates necessary to execute the actions outlined here. To preserve the strategic advantage for our subscribers, this briefing highlights the analysis without disclosing the detailed numerical splits — those are available in the complete report and online portal.
For a tailored engagement — from vendor due diligence and bid preparation to M&A target screening and test-plan development — PW Consulting’s industry practice can deploy a combination of technical audit teams, financial modelers, and procurement specialists to accelerate decision cycles in 2026.
Contact our research desk to request the full report, commission a customized vendor evaluation, or schedule an executive briefing on implications for a specific portfolio or project pipeline.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Scanning Wind Lidar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com