

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Ultrasonic Scissor Market to Reach USD 2,257.16 Million by 2032, Expanding at a 6.5% CAGR

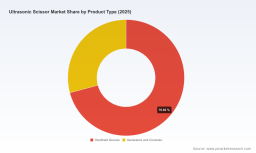
Worldwide Ultrasonic Scissor Market — Strategic Imperatives for 2026
Executive summary
PW Consulting’s latest Worldwide Ultrasonic Scissor Market report (base year 2025) synthesizes commercial, clinical, regulatory and technology intelligence to equip senior executives, product leaders, M&A teams and hospital procurement groups with a decision-ready roadmap for 2026. The ultrasonic scissor market is on a sustained growth trajectory: total industry revenues expanded from approximately USD 1,050.45 Million in 2020 to USD 1,452.5 Million in 2025 and are forecast to reach roughly USD 2,257.16 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.5% over the 2026–2032 forecast window. While headline growth is attractive, underlying forces — technological integration with robotics, platform bundling, vertical consolidation and regulatory dynamics — are reshaping competitive advantage. This release outlines the strategic takeaways; the full report contains the granular segmentation, scenario models and executable playbooks.
Worldwide Ultrasonic Scissor Market
Why this matters for 2026 decisions
For 2026, executives need fast, actionable clarity. Capital allocation, product roadmaps, go-to-market pivots and clinical evidence investments made this year will determine whether firms capture disproportionate share as the market scales toward the 2030s. The market’s mid-single-digit CAGR masks pockets of rapid adoption driven by robotic compatibility, cordless solutions and single-use economics; conversely, outsourcing/reprocessing, price pressure and reimbursement complexity compress margins in matured channels. Our analysis helps leaders prioritize where to invest, partner or divest.
Worldwide Ultrasonic Scissor Market
What the report delivers — practical contents
- Independent market-sizing and forecasting model (base year 2025; historical 2020–2025; forward projections to 2032) with scenario sensitivity for pricing, adoption and regulatory shifts.
- Competitive benchmark and playbook: capability matrices, go-to-market archetypes, supplier bargaining power and differentiated product features tied to clinical outcomes.
- Regulatory and reimbursement mapping: classification pathways (e.g., FDA product code dynamics for ultrasonic instruments), typical 510(k) strategies, and country-level approval risks.
- Technology roadmap and adoption curve: cordless vs. console, single-use vs. reprocessable, integration with robotic platforms, and the economics of vessel-sealing performance (e.g., up to 7mm vessel claims).
- Commercial levers and pricing playbook: bundling strategies, service-for-disposable models, hospital procurement negotiation tactics, and value-based contracting frameworks.
- Supply chain and manufacturing risk assessment: single-source component risks, geographic production concentration, and mitigation strategies including dual sourcing and strategic inventory policy.
- Opportunity matrix for investors and M&A teams: prioritized target profiles, synergy quantification and integration risk scoring.
Market structure and concentration
The ultrasonic scissor market exhibits a relatively high degree of concentration: the top three suppliers capture a majority share (CR3 ~65.4%), and the top five move substantially higher (CR5 ~78.85%). This concentration creates both barriers and openings. Incumbent majors benefit from trusted clinical relationships, extensive evidence portfolios and bundled platform economics, while nimble challengers can win through product differentiation (cordless convenience, competitive pricing, or robotic compatibility) and focused commercial plays in underpenetrated segments.
Worldwide Ultrasonic Scissor Market
Competitive dynamics — what incumbents and challengers are doing
- Incumbent platform leaders are doubling down on clinical differentiation. Companies with established surgical-energy franchises are promoting instruments with claims around rapid transection, consistent hemostasis and vessel sealing performance, while extending sterile single-patient-use offerings to simplify hospital workflows.
- Robotics and systems integrators are entering or partnering to embed ultrasonic energy into robotic arms and advanced energy platforms. Recent product launches demonstrate a trend toward modular advanced-energy instruments that can be paired with both manual and robotic systems.
- Emerging players, particularly device manufacturers from Asia, are competing on cost and regulatory speed-to-market. Several have secured CE markings, FDA 510(k) clearances, or have launched products claiming competitive vessel-sealing performance — signaling accelerated global competition.
- Reprocessing and aftermarket plays remain relevant. Some channel participants pursue reprocessing as a margin play in mature markets; others compete on total cost of ownership versus disposable models.
Notable recent developments shaping near-term strategy
- Robotics integration: A leading surgical robotics company announced an ultrasonic dissector designed for robotic platforms — an inflection point that highlights the commercial importance of cross-platform compatibility.
- Regulatory milestones: A number of companies secured regulatory clearances for disposable ultrasonic shears, underlining that the 510(k) pathway remains a practical route to market for entrants with robust equivalence claims.
- New product introductions: Vendors continue to launch ultrasonic shears with expanded vessel-sealing claims and hybrid energy platforms, intensifying competition on both clinical performance and the breadth of surgical indications supported.
Regulatory and clinical evidence — practical implications
Ultrasonic surgical instruments are typically classified under established regulatory product codes requiring premarket notifications in major markets. For 2026, companies must align regulatory strategy with commercialization timing: an aggressive launch can be derailed by incomplete equivalence data, while overly cautious evidence strategies can cede adoption momentum to competitors. The optimal path balances a defensible 510(k) dossier with prioritized post-market clinical studies demonstrating key economic endpoints (OR time saved, reduced consumable use, complication reduction) that matter to hospital purchasers.
Strategic playbook for 2026 — prioritized actions
- For incumbents: Convert platform trust into service-led differentiation. Bundle instruments with training, digital analytics and outcome guarantees. Accelerate compatibility modules for leading robotic systems and lock in large system integrators via co-development agreements.
- For challengers and fast followers: Focus on a narrow set of high-value use-cases (e.g., minimally invasive gynecology or robotic-assisted general surgery) where lower cost or unique form factors provide a clear switching incentive. Pursue focused clinical partnerships rather than broad-based trials to build momentum rapidly.
- For hospitals and group purchasing organizations: Re-evaluate TCO models — include reprocessing, downtime, and training costs. Negotiate outcome-based pilots tied to defined KPIs (procedure time, stapler reduction, OR throughput) and demand multi-year service commitments to limit vendor lock-in risk.
- For private equity and strategics: Seek bolt-on targets that supply niche indications, possess complementary regulatory clearances, or provide entry to high-growth geography or robotic-enabled workflows. Prioritize targets where integration can rapidly expand installed base or reduce per-procedure cost.
Tactical 90–180–360 day roadmap
- 0–90 days: Rapid portfolio audit — map products to clinical outcomes, identify three highest-ROI upgrade opportunities (e.g., cordless redesign, single-use economics, robotic adapter). Begin targeted KOL engagements for pilot site identification.
- 90–180 days: Secure regulatory timelines and start 510(k) submissions where appropriate. Launch minimum viable commercial pilots with outcome-based contracting. Lock in supply chain contingencies for critical components.
- 180–360 days: Scale pilots to multi-center studies that feed reimbursement dossiers and marketing claims. Finalize partnerships for robotics/console integration or distribution in prioritized geographies. Prepare M&A diligence for identified bolt-ons.
Risks and downside scenarios
- Price commoditization driven by lower-cost entrants could erode margins if incumbents fail to materially differentiate through service and outcomes.
- Regulatory setbacks or protracted equivalence disputes could delay market entry and create windows for competitors.
- Supply-chain concentration — especially for unique transducer components — may trigger capacity constraints if demand accelerates faster than forecasted.
- Clinical disappointments (e.g., failure to demonstrate meaningful OR time or complication benefits) can stall adoption and provoke aggressive pricing responses.
How PW Consulting’s report reduces execution risk
Beyond headline forecasts, our report provides decision-makers with reproducible models, granular sensitivity tests and a prioritized list of evidence-generation experiments tied to quantified commercial outcomes. Clients receive playbooks customized by company archetype, a list of vetted regional distribution partners, and a short-list of plausible M&A targets with integration scorecards. Importantly, for confidentiality and to preserve competitive advantage, this press summary does not publish the granular regional and application splits, price curves or company-by-company revenue allocations that underpin our models — these are available in the full report package with interactive spreadsheets and scenario tools.
Conclusion — the 2026 imperative
The ultrasonic scissor market offers a compelling growth runway, but the window to lock durable advantage in the 2026–2028 period is narrow. Companies that combine surgical performance differentiation with platform partnerships (especially robotics), evidence-led commercial models and supply-chain resilience will capture the most value as the market scales toward the projected USD ~2.26 billion (USD Million) endpoint in 2032. For executives preparing 2026 budgets, the choice is simple: deploy capital to defend or extend platform economics now, or plan for a catch-up game that will be structurally harder and costlier.
Next steps
To access the complete dataset, segmentation detail, competitor dashboards and our executable 2026 playbooks, visit the full report page or contact PW Consulting’s healthcare devices practice. The full report includes downloadable models that allow you to stress-test pricing, adoption and regulatory scenarios against your specific corporate assumptions.
For detailed analysis of this topic, please visit the official page: Worldwide Ultrasonic Scissor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com