

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Prescription Cat Food Market Valued at USD 6,240.5 Million in 2025, Poised for 6.45% CAGR Through 2032

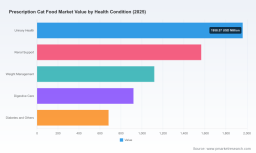
Worldwide Prescription Cat Food Market — 2026 Strategic Preview
As senior industry analysts at PW Consulting, we present an executive preview of our forthcoming Worldwide Prescription Cat Food Market report. This analysis distills the highest-value insights senior leaders need to align product, commercial and M&A strategies for 2026 and beyond. The full report contains the granular model, segment-level tables and scenario outputs that underpin the recommendations summarized here.
Worldwide Prescription Cat Food Market
Why this market matters to strategic decision-makers in 2026
Prescription cat food is no longer a niche within pet care: it is a structurally growing, clinically anchored category that combines medical necessity, recurring revenue and high margins. Our market model shows global revenue expanding from USD 4,565.2 Million in 2020 to USD 6,240.5 Million in the base year 2025, and projected to reach USD 9,665.85 Million by 2032. The forecast period (2026–2032) reflects a compound annual growth rate (CAGR) of 6.45% — a pace that supports both organic innovation and inorganic consolidation strategies.
Worldwide Prescription Cat Food Market
For corporate leaders, the 2026 inflection lies in two concurrent dynamics: accelerating clinical adoption (veterinarian recommendation and owner compliance) and margin pressure from upstream input volatility. The strategic choices you make now — in portfolio composition, channel economics and supply chain resilience — will determine whether your organization captures durable share or cedes ground to the high-concentration incumbents and agile challengers.
Worldwide Prescription Cat Food Market
What the report delivers (practical, transaction-ready content)
- Transparent market sizing and a 2026–2032 forecast model built on verified historicals (2020–2025) and scenario variants for raw material stress, accelerated clinical adoption and regulatory change.
- Actionable segmentation frameworks (by region, therapeutic indication, product form and channel) with downloadable data tables and model inputs for board-level presentations. Note: segment tables are exclusively included in the full report to preserve competitive confidentiality.
- Competitive landscape dossiers for every leading player, including product mix, R&D cadence, go-to-market structures and recent product developments.
- Playbooks for 12–36 month execution: new product launch sequencing, veterinarian engagement roadmaps, pricing and promotions frameworks, and retail — both brick-and-mortar and digital — optimization checklists.
- Supply-chain and procurement playbook addressing ingredient concentration, hedging strategies and alternative formulations to manage cost shocks.
- M&A and partnership screening templates: valuation heuristics, synergy capture plans and a prioritized target list based on capability gaps and portfolio adjacency.
- Regulatory and quality assurance guidance aligned to AAFCO, FDA and key import regimes, plus a recall-risk assessment matrix and mitigation playbook.
Competitive dynamics — who matters and why
The prescription cat food market exhibits high concentration: the top three players account for approximately 72.4% of industry revenue, and the top five capture roughly 84.6%. That structure creates both stability and strategic friction. Large incumbents have scale advantages in manufacturing, distribution to veterinary channels, clinical trial funding and brand trust. At the same time, concentration leaves spaces for specialized entrants to win on palatability innovations, focused therapeutic expertise and superior DTC service models.
- Hill's Pet Nutrition (Topeka, USA) remains a category anchor with a mature Prescription Diet franchise covering renal, urinary, metabolic and GI indications. Hill’s continues to invest in clinically backed extensions and niche therapeutic launches — for example, their recent dermatology-focused dry formula — which demonstrate the importance of evidence-based differentiation.
- Royal Canin (France) leverages veterinary-first positioning and a wide veterinary diet portfolio. Recent updates to renal formulations emphasize palatability improvements — a reminder that clinical efficacy must be matched with feeding acceptance to drive long-term adherence.
- Nestlé Purina PetCare (USA) uses portfolio breadth and packaging refreshes to maintain shelf presence across veterinary and retail channels; their catalog updates in 2024 reflect continued investment in product presentation and channel-tailored assortments.
For potential challengers, the strategic implications are clear: either build scale rapidly through M&A and distribution partnerships, or pursue a narrow, high-value therapeutic niche where clinical differentiation and owner adherence translate directly into premium pricing and recurring revenue.
Market drivers, headwinds and the 2026 agenda
- Clinical adoption and veterinary channel economics: Veterinarian recommendation remains the single most influential purchase driver for prescription diets. Investments in peer-reviewed evidence, veterinarian continuing education and simple sampling programs yield outsized returns in conversion and retention.
- Owner compliance and palatability: Prescription formulations that balance clinical efficacy with palatability and convenience materially improve long-term adherence. Product reformulation efforts that specifically target palatability — as seen in recent renal updates — should be prioritized.
- Input cost volatility: Raw-material inflation is an active operational risk. For example, chicken meal prices have risen materially year-over-year, demonstrating supply-side sensitivity. Procurement strategies that combine multi-sourcing, formula flexibility and selective vertical integration will be table stakes in 2026.
- Regulatory and labeling requirements: Compliance with AAFCO nutrient profiles and FDA labeling statutes remains mandatory and influences formulation and claims architecture. Importers must navigate registration regimes in key markets, affecting go-to-market timing and cost.
Strategic recommendations for 2026
Below are high-probability actions to prioritize in Q1–Q4 2026. Each is designed to be executable within 6–18 months and to materially improve competitive position under the baseline 6.45% CAGR scenario.
- Increase investment in veterinary KOLs and evidence generation: Allocate budget to pragmatic clinical trials and case-series that demonstrate real-world outcomes. Use fast, low-cost trials to support label improvements and peptide/palatability claims that directly improve adherence.
- Launch a palatability-led renal line extension: Market leaders have shown that palatability upgrades can lift share in renal segments. Prioritize sensory science, flavor systems and wet-dry pairing options for owners seeking convenience.
- Hedge ingredient exposure and densify suppliers: Implement a three-tier sourcing model (primary, secondary, contingency) for high-risk ingredients. Negotiate multi-year contracts with indexed pricing clauses to stabilize gross margins.
- Optimize channel economics: Rebalance channels to favor veterinary prescribing while expanding subscription and home-delivery models to enhance lifetime value. Create bespoke commercial agreements with veterinary networks to reduce friction around sample allocation and reimbursement.
- Pursue targeted M&A to fill capability gaps: Prioritize bolt-ons that provide clinical specialty (e.g., dermatology, GI), digital adherence tools or direct-to-consumer ecosystems. Use the report’s M&A screening templates to quantify synergies in 24-month timelines.
- Operationalize recall and safety readiness: Even with no active recalls among major brands as of Q1 2026, maintain rapid-response protocols, lot-level traceability and consumer communication playbooks to protect brand equity.
Scenarios and KPIs we model for 2026 board decisions
Our report includes three modeled scenarios (baseline 6.45% CAGR, a downside raw-material stress case and an accelerated adoption upside). For 2026 board discussions, focus on these KPIs:
- Net revenue growth by therapeutic cluster (available in full model)
- Gross margin sensitivity to ±10% ingredient cost swings
- Veterinary conversion rate and retention (30/90/180-day adherence cohorts)
- Customer acquisition cost and lifetime value under subscription vs single-purchase models
- Time-to-market and regulatory clearance lead-times for new formulations
What to expect from the full PW Consulting report
The full report is structured for direct operational use. It contains the downloadable forecast model (2026–2032) with scenario toggles, proprietary market-concentration mapping, supplier risk heatmaps and transaction-level diligence checklists. We purposely withhold the granular segment-by-segment tables from this preview to preserve the competitive signal; those tables are included with the report purchase and are the basis for the playbooks and M&A screens described above.
Closing view — how to convert insight into advantage
The prescription cat food market will remain a strategic priority for pet-food manufacturers, veterinary channels and private equity investors in 2026. The combination of clinical stickiness and predictable recurring demand creates opportunities for margin expansion — provided firms invest in adherence-centered product design, supply-chain resilience and vet-focused commercialization.
For executives preparing 2026 budgets or evaluating portfolio moves, the question is not whether to engage in prescription nutrition, but how to allocate capital between scale (distribution, manufacturing) and differentiated capabilities (clinical evidence, palatability, digital adherence). Our analysis suggests that selective investments in these vectors will yield disproportionate returns through 2032.
To access the full dataset, segment tables, company dossiers and the interactive forecast model, please consult the PW Consulting Worldwide Prescription Cat Food Market report. The complete package supplies the exact inputs and templates your strategy, commercial and M&A teams need to execute in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Cat Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com