

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide IT Infrastructure Outsourcing Market Set to Expand at a 6.74% CAGR Through 2032

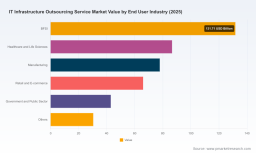
Worldwide IT Infrastructure Outsourcing Service Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market research previews the strategic inflection enterprises face as IT infrastructure outsourcing (IITO) shifts from labor arbitrage to outcome-driven, security-first managed services. The study synthesizes five years of historical performance (2020–2025) and a seven-year forecast window (2026–2032). At the topline, the market expanded from roughly USD 310.5 Billion in 2020 to an estimated USD 435.5 Billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.74% through 2032, reaching approximately USD 687.5 Billion by the end of the forecast period. These macro dynamics create a distinct set of opportunities—and risks—for enterprise procurement, architecture, and risk teams planning budgets, sourcing strategies, and transformation roadmaps for 2026 and beyond.
Worldwide IT Infrastructure Outsourcing Service Market
What the report delivers — practical, actionable intelligence (not a data dump)
-
Strategic frameworks for vendor selection that align total cost of ownership (TCO), service-level outcomes, and regulatory posture—accompanied by customizable RFP templates and weighting matrices designed for complex, hybrid environments.
Worldwide IT Infrastructure Outsourcing Service Market -
Operational playbooks for cloud migration and datacenter rationalization: phased migration plans, cutover risk-control checklists, runbook harmonization templates, and pragmatic KPIs for measuring business continuity and performance improvements.
Worldwide IT Infrastructure Outsourcing Service Market -
Security and compliance roadmaps tailored to outsourced environments—mapping requirements from GDPR, HIPAA, PCI DSS and new regulatory constructs (including the U.S. Department of Justice Bulk Data Rule) into technical, contractual, and audit-ready controls.
-
Workforce and sourcing models that quantify the impact of rising labor costs and AI automation on nearshoring decisions, change management, and cost-to-serve optimization—plus vendor governance operating models for continuous third‑party risk assessment.
-
Commercial and negotiation playbooks covering outcome-based contracting, performance incentives, transition risk caps, and exit strategies to avoid operational lock-in while preserving value continuity.
Why the topline matters to 2026 planning
The market’s steady upward trajectory—reflected in the mid‑single‑digit CAGR—signals sustained enterprise demand for outsourced infrastructure capabilities, but not uniform opportunity. Growth is being driven less by pure hosting transactions and more by integrated propositions: managed cloud and security services, AI-augmented operations, and compliance-as-a-service bundles. For executives preparing 2026 budgets, that means capital allocation should prioritize vendors and internal capabilities capable of delivering observability, automated remediation, and compliance assurance across hybrid estates, rather than cost-per-seat efficiency alone.
Competitive landscape — concentrated by capability, fragmented by share
Our market concentration analysis shows a sector that is capability-concentrated but market-share fragmented. Top global systems integrators and managed services firms lead on end-to-end outsourcing propositions, while a long tail of regional players serves specialized vertical or technical niches. The competitive set analyzed in the report includes legacy consultancies and global IT services firms whose strategic positioning illustrates the choices enterprises face:
-
Accenture: positions around integrated cloud, hybrid infrastructure, and agentic-AI enablement for complex enterprise environments.
-
IBM (and spin-offs tied to infrastructure services): focuses on hybrid cloud, AI-enabled infrastructure management, and legacy systems modernization.
-
TCS, Infosys, Wipro, HCLTech and Tech Mahindra: deliver global scale in managed infrastructure, cloud migration, and operations, with growing investments in automation and industry-specific offerings.
-
Cognizant, Capgemini, DXC Technology, NTT DATA, Atos, Fujitsu, Kyndryl and others: represent a mixture of consulting-led transformation and large-scale managed services, often differentiating through vertical depth or regional reach.
-
Deloitte and other consultancies: blend advisory and managed delivery, increasingly bundling compliance, cloud engineering and security services into single engagements.
Recent strategic moves — including acquisitions to stitch AI and cybersecurity into infrastructure propositions and alliances to accelerate AI-based operations — are reshaping delivery models. Examples covered in the report include major acquisitions embedding agentic‑AI and cybersecurity capabilities, and partnerships aimed at AI-enabled infrastructure management. These developments matter to buyers because they change the speed with which new automation and risk-management features appear in vendor toolchains and SLAs.
Regulatory and risk dynamics that must be embedded into sourcing decisions
Regulation is now a primary determinant of sourcing architecture. The report maps out how evolving legal mandates—ranging from cross-border data transaction rules to audits of AI governance—translate into contract terms, technical controls, and monitoring requirements. Key implications for 2026 procurement and architecture include:
-
Mandated evidence trails and continuous controls monitoring: enterprises must require vendors to provide automated attestations (SOC 2, ISO 27001) and real‑time telemetry to pass regulatory and audit scrutiny.
-
Data residency and cross-border transaction constraints: procurement teams need clause libraries and escape valves for bulk sensitive data processing, with clear escalation and remediation paths.
-
AI governance and third‑party risk: vendors must demonstrate AI lifecycle controls—data lineage, model validation, bias mitigation and rollback capabilities—when infrastructure services touch AI workloads.
-
Service continuity with compliance posture: disaster recovery and continuity tests must now incorporate compliance restoration scenarios, not just RTO/RPO targets.
Practical recommendations for enterprise leaders in 2026
-
Rebase outsourcing KPIs toward outcomes and resiliency. Move beyond utilization and headcount metrics to observability‑driven KPIs that measure detection-to-remediation time, configuration drift, and compliance coverage.
-
Make dual sourcing and modular contracts the default. Reduce lock-in by segmenting outsourcing scope into modular components—platform operations, security monitoring, network management—each with discrete SLAs, data export guarantees, and exit mechanics.
-
Insist on AI and automation roadmaps in proposals. Evaluate vendors on demonstrable automation that reduces mean time to repair while preserving governance and explainability for automated decisions.
-
Operationalize continuous vendor risk assessment. Embed vendor telemetry into your GRC and SIEM platforms, and require quarterly tabletop exercises that test regulatory and bulk-data incident responses.
-
Plan workforce transitions now. Rising labor costs and automation will shift the skill mix needed in-house—invest in vendor governance, cloud-native security expertise, and SRE capabilities rather than only traditional operations roles.
Implementation playbook (high level)
-
Phase 1 — Assess: map the estate, classify data by regulatory sensitivity, and quantify the business impact of downtime and compliance lapses.
-
Phase 2 — Design: build target state architectures that hybridize cloud with secured on‑prem/dedicated facilities; define measurable SLAs and compliance gates.
-
Phase 3 — Select: run a staged RFP with mandatory compliance proofs, automation baselines, and a simulated transition test as part of vendor scoring.
-
Phase 4 — Transition: adopt a phased cut-over with parallel runbooks, rollback triggers, and an empowered transition management office backed by the vendor.
-
Phase 5 — Optimize: measure outcomes, capture automation-led savings, and re-invest into resiliency and continuous improvement cycles.
How to use this report
This PW Consulting report is designed as an operational guide for CIOs, heads of procurement, security leaders, and business-unit sponsors who will make outsourcing decisions in 2026. It pairs market-level projections and competitive context with hands-on tools: tailored RFP templates, compliance checklists, TCO models and transition playbooks. Importantly, while this press preview outlines the strategic takeaways and actionable frameworks, the detailed segment-level tables, vendor scorecards, and region/service-specific quantitative matrices are deliberately reserved for the full report offering. These granular datasets are the critical inputs for bespoke sourcing scenarios and ROI models.
Next steps & access
Enterprises preparing 2026 sourcing cycles should use the topline growth trajectory and capability trends described here to stress-test existing contracts and near-term transformation choices. To unlock the complete segmentation data, vendor benchmarking heatmaps, and downloadable implementation artifacts that support procurement and architecture decision-making, please visit the report landing page or contact PW Consulting’s industry team. The full report contains the confidential segment and vendor-level analysis necessary to convert strategic intent into procurement-ready actions.
For detailed analysis of this topic, please visit the official page: Worldwide IT Infrastructure Outsourcing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com