

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Ceramic Wafer Boat Market Poised for 8.12% CAGR in 2026–2032 Forecast

Worldwide Ceramic Wafer Boat Market — Strategic Imperatives for 2026
PW Consulting today releases a forward-looking executive synopsis of our new market research, Worldwide Ceramic Wafer Boat Market (base year 2025; forecast 2026–2032). The study integrates an extended historical view (2020–2025) and a demand-driven forecast framework that sets out clear decision pathways for 2026 procurement, operations and investment choices. Key headline metrics underpin the urgency confronting semiconductor equipment buyers and materials suppliers: the market reached USD 542.8 Million (USD Million) in 2025 and, under our central-case scenario, grows at a compound annual growth rate (CAGR) of approximately 8.12% over the 2026–2032 forecast window.
Worldwide Ceramic Wafer Boat Market
Why this matters for 2026 decision-makers
Two converging dynamics make ceramic wafer boats a strategic purchasing and technology topic for 2026. First, wafer fabrication capacity expansion—particularly in Asia-Pacific—continues to drive demand for components that endure higher process temperatures and stricter contamination constraints. Second, the upstream industrial structure is neither fully fragmented nor completely consolidated: the top three suppliers together account for a meaningful share of the market (CR3 ~48.5%), and the top five approach concentrated leadership (CR5 ~62.3%). The combination of rising demand and concentrated supply amplifies supplier selection risk, qualification lead times, and leverage for established incumbents.
Worldwide Ceramic Wafer Boat Market
For procurement leads, process engineers, and corporate strategists, these dynamics translate into immediate priorities for 2026: accelerate supplier qualification cycles for advanced ceramic materials, incorporate regulatory scenarios into sourcing decisions, and align capital allocation to support resilient supply chains that match node and process roadmaps.
Worldwide Ceramic Wafer Boat Market
What the report delivers — practical, executable intelligence
- Market sizing and forecast models calibrated to 2020–2025 history and updated to reflect 2026 capacity plans, price and adoption curves.
- Scenario-driven regulatory impact assessments that map export-control permutations (including implications of refinements to the Foreign‑Produced Direct Product Rule) onto sourcing and qualification timelines.
- Supplier scorecards and strategic supplier shortlists built from capability matrices, manufacturing footprints, material certifications and contamination performance metrics.
- Procurement playbooks and TCO calculators that fold in lifetime part durability, process yield impact, replacement cycles and logistics risk to produce decision-ready procurement frameworks.
- Process-material matching guidance that helps process engineers select ceramic materials and coatings for diffusion, oxidation and vapor-deposition environments without unnecessary over-specification.
- M&A and investment dashboards that identify capability adjacencies, technology gaps and consolidation opportunities across the ceramic wafer boat value chain.
These deliverables are tailored for rapid operationalization: scorecards with weighting templates, ready-to-use RFP language for 2026 sourcing events, and sensitivity analyses designed for CFOs and supply-chain heads to stress-test capital planning under multiple geopolitical and demand scenarios.
Competitive landscape — assessing capability sets and strategic positioning
Our competitive analysis synthesizes primary supplier intelligence, public disclosures and product-level assessments to profile capability clusters. Several themes emerge:
- Full-spectrum engineered-ceramics leaders: Established firms with deep material science expertise and high-purity production—typified by companies that emphasize engineered ceramics and fine-ceramic processing—offer strong contamination control and long-life performance for advanced process steps. These players are natural partners for OEMs requiring co-development and stringent qualification programs.
- Thermal and chemical specialists: Firms focused on silicon carbide (SiC) and high-temperature ceramics address the most demanding diffusion and oxidation environments. Their competitive advantage is measured in thermal stability, particle generation performance and coating technologies designed to extend service life in corrosive chemistries.
- Regional-production innovators: A number of manufacturers based in Asia have scaled capabilities across SiC, recrystallized SiC and coated variants to serve local fabs and global supply chains. These suppliers offer speed-to-qualification for regionally located fabs but present buyers with trade-offs around IP protection, qualification parity and long-term supply commitments.
Representative profiles examined in the report include multinational engineered-ceramics firms based in Japan and the United States, quartz and SiC specialists operating with trans‑Pacific footprints, and a cohort of Asian manufacturers focused on custom SiC carriers and coated solutions. Each profile contains a concise assessment of: material portfolio, manufacturing scale, contamination-test performance, R&D roadmaps, and partnership posture.
Recent industry movements and their strategic implications
- Product innovation in recrystallized SiC with advanced CVD coating options points to a maturing technology curve—improved durability and lower replacement frequency will change lifecycle costing and procurement cadence.
- Updated product catalogs and trade-show activity from regional manufacturers indicate ongoing capability expansion and the availability of more tailored vertical and horizontal carrier designs for diffusion and oxidation processes.
- Refinements to export-control frameworks are elevating compliance and dual-sourcing planning into boardroom-level conversations; buyers must now model regulatory scenarios alongside conventional supply risks.
We translate these developments into actionable supplier-risk matrices and a set of qualification accelerators that reduce lead times without compromising contamination controls.
Materials and process dynamics — what separates winners from also-rans
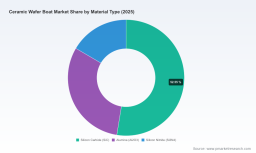
Material selection is the single largest technical lever in wafer-boat procurement. Silicon carbide (SiC) is increasingly favored for high-temperature, low-contamination environments due to its superior thermal stability and lower particle-generation risk relative to traditional quartz in advanced diffusion and oxidation steps. That said, high-purity quartz still retains a role in lower-temperature anneals where cost and proven qualification favor its use.
For 2026, decision-makers should adopt a process-driven materials taxonomy rather than a one-size-fits-all specification. The report provides a practical decision tree for matching materials and coatings to process windows, including condition-based thresholds where SiC becomes a de‑facto requirement. We also quantify the operational and yield impacts of material substitutions in our TCO modules.
Strategic recommendations for 2026
- Embed regulatory scenario planning into 2026 sourcing: integrate export-control contingencies into long-term supply contracts and qualification roadmaps.
- Prioritize co-development agreements with suppliers who demonstrate both material performance and capacity to scale—this reduces qualification time and secures long‑lead supply.
- Adopt a dual‑track materials strategy: qualify SiC or coated SiC for high-risk processes while maintaining validated quartz or lower-spec options for less demanding steps to optimize capex and lifecycle cost.
- Use supplier scorecards to identify where supplier concentration creates single-point-of-failure risk and pursue second-source relationships or strategic inventory buffering accordingly.
- For investors and acquirers, focus on upstream ceramics capabilities (coating, recrystallized SiC production and contamination control IP) as prime differentiation axes for consolidation plays.
How PW Consulting’s report supports execution
This research is built to be operational rather than purely descriptive. Subscribers gain access to Excel-native forecast models, supplier benchmarking templates, RFP language and a step-by-step procurement playbook tuned for 2026 qualification cycles. Critical segmentation tables, regional and application breakdowns, and vendor-level revenue reconstructions are intentionally reserved for the full report and supporting data pack—these deliverables contain the granular inputs necessary to run internal sourcing optimization and M&A screens.
For teams preparing 2026 capex and procurement plans, the full package removes ambiguity: it ties market demand scenarios to lead-time implications, supplier concentration metrics and regulatory risk contingency costs so that decision-makers can prioritize spend where it materially affects process continuity and yield.
Conclusion — action now, benefit later
The ceramic wafer boat market sits at the intersection of materials science, supply‑chain dynamics and geopolitics. Our analysis shows a sustained growth trajectory driven by wafer fabrications’ thermal and contamination demands, with the market expected to expand materially through the end of the forecast period. For 2026, the practical question is not merely which material or supplier to select today, but how to design sourcing and qualification processes that preserve yield, control lifecycle cost, and mitigate regulatory and concentration risks.
PW Consulting’s Worldwide Ceramic Wafer Boat Market report equips executives with the frameworks, models and supplier insight needed to make those choices with confidence. For access to the full dataset, granular segmentation, supplier revenue estimates and the downloadable toolset that operationalizes our findings, please visit our report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Worldwide Ceramic Wafer Boat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com