

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hotel Market Poised for 6.5% CAGR — Global Recovery Fuels New Growth Opportunities

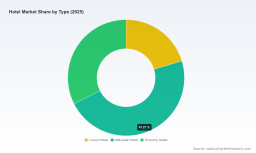
Worldwide Hotel Market — Strategic Briefing for 2026: What Leaders Must Know
PW Consulting’s latest Worldwide Hotel Market report (base year 2025, forecast 2026–2032) arrives at a pivotal moment for industry decision-makers. After a multi-year recovery, the global hotel market stands at approximately USD 1,230 Billion in 2025 and — under our central scenario — is set to expand at a compound annual growth rate of 6.5% through 2032, reaching nearly USD 1,910 Billion by the end of the forecast horizon. This release synthesizes macro performance, operating dynamics, competitive moves and actionable playbooks designed to inform capital allocation, brand strategy and operational priorities for 2026.
Worldwide Hotel Market
Why the 2026 Horizon Is Strategically Decisive
-
Market momentum is real but uneven. Global room revenue metrics recovered meaningfully in 2025 (RevPAR reached about USD 102, up ~4.5% year-over-year), driven by leisure reopening and rising international flows. That opens opportunity windows for expansion and yield optimization in 2026 — if players act with speed and strategic clarity.
Worldwide Hotel Market -
Macro cost pressures and regulatory shifts are forcing a re-think of operating models. Wage inflation, construction-material cost upticks and new digital disclosure rules are compressing margins and reshaping distribution economics.
Worldwide Hotel Market -
Fragmentation and selective consolidation coexist: market concentration remains relatively low (CR3 ~18.5%, CR5 ~23.4%), creating scope for roll-ups, platform plays and conversion strategies that can scale brand and loyalty economics.
What the Report Delivers — Practical Intelligence, Not Hazy Projections
PW Consulting’s Worldwide Hotel Market report is structured to be executional for 2026 decision cycles. Highlights include:
-
Top-down market sizing and transparent forecasting methodology (historical 2020–2025, base year 2025, forecast 2026–2032), with scenario outputs linked to demand drivers such as international travel recovery and corporate travel trends.
-
Revenue-management and RevPAR sensitivity models that tie room-rate levers to occupancy, calendar effects and channel mix — built for integration into five-year operating plans.
-
Cost-inflation playbooks addressing labor, construction and service inputs, with contracting and sourcing tactics to protect margins (short-, medium- and long-term actions).
-
Competitive benchmarking and capability maps across leading operators, franchise networks and emergent lifestyle players, including profiles of anchor competitors and recent strategic moves.
-
M&A and portfolio-optimization frameworks: target screening heuristics, valuation approaches for asset-light vs. asset-heavy structures, and integration checklists that prioritize near-term cash conversion.
-
Distribution and compliance trackers: OTA exposure analyses, commission sensitivity, and practical steps to meet new digital disclosure requirements while preserving direct-booking economics.
-
Commercial playbooks for owners and operators (brand conversion, soft-branding, franchise renegotiation, GDS vs. OTA channel mix), and investor-ready slide decks and data packs for due diligence.
Competitive Landscape — Who’s Moving and Why It Matters
The industry’s major operators are sharpening distinct strategic axes. Operators with large brand portfolios and global distribution networks are leveraging loyalty economics and conversions; asset-light franchisors are doubling down on pipeline growth; and regional groups continue to exploit local supply-demand asymmetries.
-
Marriott International continues to scale across multiple segments and geographies with a large global portfolio, prioritizing Asia-Pacific and Middle East expansions. Its push is emblematic of a strategy that combines new-builds and conversions to accelerate room growth while protecting distribution advantages.
-
Hilton Worldwide is pursuing brand-layering and conversion opportunities through targeted midscale launches designed to capture demand beneath the premium tier — an aggressive approach to densify presence in core markets without proportional capex.
-
IHG’s partnership and pipeline activity signal a renewed focus on luxury and lifestyle inventory in gateway cities, where premium RevPAR recovery and group demand can justify higher development multiples.
-
Wyndham’s franchise-led expansion reinforces the resilience of economy and midscale models in high-volume, price-sensitive segments — a reminder that scale and standardization remain powerful value drivers.
-
Accor, Hyatt, Choice and Radisson each exhibit differentiated plays — from European/Asia strength to lifestyle and soft-brand amplification — creating an environment where selective partnerships and co-investments are increasingly attractive to owners seeking distribution and brand premiums.
Collectively these moves should inform 2026 strategies: owners must decide whether to chase brand-driven premiums, protect yield through direct channels, or pursue conversion pipelines that balance capex with immediate revenue uplift.
Key Dynamics and Near-Term Risks
-
Regulatory transparency: New digital disclosure requirements have altered booking behavior and fee pass-through dynamics. Distribution strategies must be redesigned to preserve margin under more transparent pricing displays.
-
Labor and operating cost inflation: U.S. hotel labor costs rose materially in 2025, contributing to margin squeeze. Workforce productivity investments and tech-enabled service models will be key mitigants.
-
CapEx and construction inflation: Global hotel construction-material costs saw meaningful increases, pressuring development timelines and unit economics. Project contingencies and supply-chain re-designs must be factored into underwriting.
-
Demand composition shift: Leisure remains a major engine of growth, but corporate travel is staging a robust comeback. The unfolding cadence of business travel recovery will determine group bookings, corporate negotiated rates, and midweek demand normalization.
Strategic Priorities for 2026 — Where to Deploy Attention and Capital
-
Prioritize conversion and franchise conversion pipelines where balance-sheet light growth can deliver near-term room gains. Conversions can accelerate footprint at lower incremental capex versus ground-up development.
-
Recalibrate distribution economics: implement direct-booking incentives, renegotiate commission floors with OTAs, and invest in CRM and loyalty re-engagement to capture higher-margin repeat customers.
-
Embed cost pass-through clauses and indexation in new development and renovation contracts to mitigate material and wage inflation risk.
-
Lock in supply and labor partnerships: build regional hubs for procurement, adopt hybrid staffing models, and accelerate investments in automation for non-core guest touchpoints to improve productivity.
-
Design portfolio hedges for downside scenarios: stress-test forecasts against slower corporate demand rebound and higher interest-rate backdrops to inform covenant structures and refinancing windows.
-
Leverage white-space in fragmented markets. With concentration relatively low, roll-ups and platform plays that create distribution scale can unlock multiple arbitrage opportunities for private-equity and strategic acquirers.
-
Commit to distribution compliance and guest transparency early: compliance-ready booking flows and fee disclosures reduce booking friction and reputational risk as regulators tighten rules.
How PW Consulting Translates Insight into Action
Our report is tailored for the 2026 decision cycle: it pairs strategic narrative with toolkits you can deploy immediately. Clients receive:
-
Interactive financial models and scenario dashboards calibrated to your portfolio and investments.
-
A competitive heatmap and deal-screening engine to identify acquisition targets or conversion candidates that fit your risk-return thresholds.
-
Operational playbooks across commercial, development, and people functions — including clause templates, procurement strategies and channel optimization frameworks.
-
Executive briefings with bespoke slices of the data and a 90-day implementation roadmap for priority initiatives.
While this briefing presents the strategic contours and implications, the report contains the granular tables, regional and segment breakouts, and interactive datasets required to execute on these plays. We intentionally omit certain segmented figures from this preview to ensure stakeholders access the full, validated datasets in our detailed release.
Next Steps for 2026 Planning
-
Schedule a focused executive briefing to align your 2026 capital and operating plan with the market scenarios most relevant to your portfolio.
-
Request the report’s financial model to run bespoke sensitivity analyses on rate, occupancy and cost variables.
-
Engage PW Consulting to prioritize conversion targets, renegotiate distribution contracts, or develop an M&A pipeline based on our proprietary screening heuristics.
The coming two years will separate opportunistic entrants from disciplined value creators. With market volumes expanding and distribution dynamics evolving, 2026 is the year to convert momentum into durable competitive advantage. PW Consulting’s Worldwide Hotel Market report equips hotel owners, operators, investors and service providers with the evidence-based strategies and operational tools to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com