

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Prescription Diet Pet Food Market Poised for 7.12% CAGR Through 2032

PW Consulting Releases Strategic Brief: Worldwide Prescription Diet Pet Food Market — A Playbook for 2026 Decision-Making
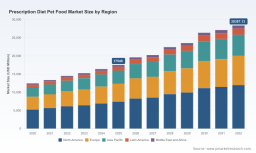
PW Consulting’s new market study on the Worldwide Prescription Diet Pet Food Market (base year 2025; historical window 2020–2025; forecast 2026–2032) reframes how executive teams should approach therapeutic pet nutrition in 2026. Our analysis finds the market reached approximately USD 17,540 Million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 7.12% through the forecast horizon, reaching multi‑billion scale by the end of the period. With high market concentration among a small set of incumbent veterinary brands, and accelerating cost and regulatory pressures across supply chains, the choices companies make in 2026 will disproportionately determine their 2028–2030 trajectories.
Worldwide Prescription Diet Pet Food Market
Why this report matters for 2026 strategic planning
-
Actionable near‑term intelligence: The report translates headline growth into executable options — from portfolio prioritization and pricing levers to channel and clinical evidence strategies — so leadership teams can convert market momentum into profitable share.
Worldwide Prescription Diet Pet Food Market -
Scenario‑ready forecasting: Our baseline forecast (CAGR 7.12%) is accompanied by downside and upside scenarios that quantify the impact of raw‑material shocks, regulatory tightening, and accelerated veterinary digital adoption on revenue and margin profiles.
Worldwide Prescription Diet Pet Food Market -
Concentration and competitive dynamics: The sector remains highly concentrated (CR3 ~68.5%; CR5 ~82.1%), which shapes competitive behavior, margin structures, and M&A windows. Understanding where to collaborate, compete, or consolidate is essential.
-
Practical toolkits: The study includes playbooks, unit economics templates, and a commercial due‑diligence checklist tailored to prescription diet portfolios for both established manufacturers and insurgent challengers.
What’s inside: Practical, commercially oriented content
-
Market sizing and forecast model (granular, downloadable): base year 2025, historical series 2020–2025, and detailed projections through 2032, with embedded sensitivity controls to test price, volume, and channel assumptions.
-
Go‑to‑market playbooks for veterinary channels: step‑by‑step engagement models for field sales, digital vet portals, and integrated clinical marketing to accelerate trial and adoption among veterinary professionals.
-
Regulatory risk matrix: assessment of jurisdictional veterinary authorization requirements, labeling and claims constraints, and compliance checklists for FSMA, AAFCO, EU import rules, and other relevant frameworks.
-
Supply‑chain stress tests: input cost pass‑through modeling, supplier concentration mapping, and contingency playbooks for ingredient shocks and logistics disruptions.
-
Competitive benchmarking and M&A playbooks: company profiles, capability maps, and acquisition target scoring to support inorganic growth or defensive consolidation.
-
Clinical evidence and R&D prioritization guidance: criteria for prioritizing therapeutic indications, trial design options, and cost‑benefit templates for demonstrating differentiated outcomes vs. commoditized offerings.
Strategic implications for 2026 — five priorities for leadership teams
-
Recalibrate portfolio focus to clinical differentiation. With steady market growth and dense competition among the leading veterinary brands, product programs that can demonstrate meaningful, peer‑reviewed clinical benefits will command premium positioning and stronger veterinary advocacy.
-
Hedge and redesign for input volatility. Recent commodity disruptions — including materially higher chicken meal costs linked to disease pressures — mean procurement and formulation strategy must be revisited. Near‑term steps include multi‑source supplier qualification, locked‑price contracts for key inputs, and recipe reformulations that preserve therapeutic efficacy while moderating feed‑cost exposure.
-
Operationalize veterinary channel economics. Prescription diets are sold predominantly through veterinary distributions; success requires optimized co‑op programs, evidence‑based sales tools, and digital stewardship mechanisms (subscription models, adherence tracking) to increase lifetime value per patient.
-
Embed regulatory and compliance design into product development. Jurisdictional differences in authorization, labeling and additive limits materially affect speed‑to‑market and go‑to‑export strategies. Firms that bake compliance into early‑stage design will avoid costly reformulations and trade barriers.
-
Use concentration to inform M&A and partnership strategies. High CR3/CR5 metrics compress competitive room for stand‑alone product launches but create attractive targets and partnership opportunities for mid‑size players seeking scale or distribution access.
Competitive landscape — positioning and near‑term moves
-
Hill’s Pet Nutrition (Topeka, Kansas, USA): With a broad Prescription Diet portfolio and deep clinical positioning, Hill’s continues to invest in therapeutic innovation and veterinarian‑facing educational assets. Recent product introductions targeted at renal health underline the play for condition‑specific leadership. For competitors, strategies include focused differentiation in underserved indications and channel partnerships to access veterinarian trust networks.
-
Royal Canin (Aimargues, France): Royal Canin’s Veterinary Diet range is characterized by tight integration with vet clinics and extensive formulation breadth. Its incremental product expansions and package sizing optimizations suggest emphasis on adoption economics at the clinic level. New entrants should prioritize clinic economics when pitching alternatives.
-
Nestlé Purina PetCare (St. Louis, Missouri, USA): Pro Plan Veterinary Diets leverage Purina’s scale in R&D and manufacturing and are actively showcased at major trade venues. Competitive responses should weigh clinical evidence and co‑marketing innovations to neutralize scale advantages.
-
Virbac (Carros, France): As a specialty veterinary firm, Virbac positions its veterinary diets alongside complementary clinical services and pharmaceuticals, creating cross‑sell synergies. The strategic play here is integration: diets plus clinic tools plus therapeutic programs.
Regulatory and standards dynamics to factor into 2026 planning
-
US regulatory environment: Prescription pet foods require veterinary authorization for sale under FDA expectations for therapeutic claims. Compliance programs that align marketing claims with substantiated clinical endpoints reduce regulatory friction and reputational risk.
-
AFFCO and labeling: AAFCO requirements for nutritional adequacy statements and ingredient listing govern product positioning and packaging across key markets. Product teams must coordinate formula changes with labeling updates and claim audits.
-
European import and additive limits: EU registration requirements and additive ceilings create barriers for rapid cross‑border launches; early regulatory engagement is essential for streamlined market entry.
-
Manufacturing controls under FSMA: Preventive controls for pet food manufacturing — including allergen cross‑contact prevention — are non‑negotiable for prescription brands that trade on safety and therapeutic integrity.
-
Raw material price trajectory: Ingredient cost inflation, exemplified by recent double‑digit movements in poultry meal pricing related to animal health events, will pressure gross margins. Tactical options include index‑linked pricing, formula redesign, and near‑shoring of critical inputs.
How to use this intelligence in 90‑ to 180‑day planning cycles
-
90‑day: Run a compressed ‘stress and opportunity’ workshop using our downloadable unit‑economics model to identify the top three products at risk from input price movements and the top three fast‑win commercial initiatives for clinic adoption.
-
180‑day: Implement a regional pilot that couples an evidence‑based clinical trial with a veterinary subscription program and a procurement hedging arrangement. Use results to inform full‑scale rollouts or M&A decisions.
What we deliberately withhold — and why
Consistent with our “trailer” approach, this release emphasizes strategic insight while withholding granular region‑by‑region and application‑level share tables, and the detailed segmentation sheets that underpin our forecasts. These granular splits — including market slices by geography, pet type and therapeutic indication, and the full company‑by‑company revenue breakouts used in our competitive models — are available in the full report package and interactive data workbook. This selective disclosure is designed to give leaders the directional clarity they need while preserving the comprehensive, source‑level intelligence that underpins commercial decisions.
Next steps and access
For commercial teams, R&D leaders, and corporate development executives preparing strategic plans for 2026, PW Consulting’s full report provides the granular inputs, scenario tools and playbooks needed to convert market growth into sustained, profitable share. To request an executive briefing, access the interactive forecast model, or obtain licensing for the full data workbook, reach out to pwconsulting.com/reports or contact our client services team to arrange a tailored walkthrough.
PW Consulting’s Worldwide Prescription Diet Pet Food Market study is intended to be a practical decision‑support tool — not just a market snapshot. In an environment defined by steady headline growth, concentrated competition, input volatility, and increasing regulatory complexity, the companies that combine clinical rigor, channel excellence, and supply‑chain resilience in 2026 will be best positioned to capture the next phase of value creation.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Diet Pet Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com