

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Portable Gaming Consoles Market Poised to Reach USD 30,127.12 Million by 2032, Driven by an 8.98% CAGR

Worldwide Portable Gaming Consoles Market — Strategic Preview for 2026 Decision Makers
PW Consulting is pleased to release an executive preview of our forthcoming Worldwide Portable Gaming Consoles Market report (base year 2025; historical 2020–2025; forecast 2026–2032). This briefing summarizes the strategic implications that matter most to corporate leaders, investors, and product teams as they set priorities for 2026. It showcases the analytical depth and decision-ready frameworks contained in the full report while reserving core segmented metrics for subscribers and report purchasers.
Worldwide Portable Gaming Consoles Market
Market at a Glance — What the Numbers Mean for Strategy
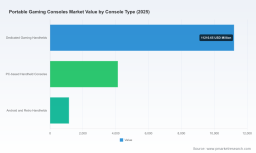
The global portable gaming consoles market reached an estimated USD 16,500 million in 2025. Our modeled outlook shows continued expansion through the forecast window, driven by technological refresh cycles, the maturation of cloud-streaming experiences, and converging device formats. The market is projected to grow at a compound annual growth rate (CAGR) of 8.98% over 2026–2032.
Worldwide Portable Gaming Consoles Market
Two high‑level structural realities underpin our projections and should shape 2026 decision making:
Worldwide Portable Gaming Consoles Market
- Concentration at the top: market share is concentrated among a small set of globally recognized platform and OEM incumbents, reinforcing the importance of IP, ecosystem advantages, and partner access for challengers and incumbents alike.
- Technology‑driven bifurcation: the category is evolving into distinct value ladders—premium portable PCs and hybrid consoles that emphasize raw performance and content compatibility, and more affordable streaming/retro-focused devices that prioritize accessibility and distribution scale.
What the Full Report Contains (Practical, Actionable Intelligence)
Our full report is designed as a strategic playbook rather than an academic exercise. It combines rigorous quantitative modeling with practical modules managers can use immediately:
- Market sizing and trend scaffolding: baseline market values, growth scenarios, and sensitivity testing under alternative technology and regulatory assumptions (currency: USD; revenue unit: Million).
- Strategic segmentation framework: a reproducible approach to mapping device archetypes (dedicated hybrid consoles, PC-based handhelds, Android/retro and cloud-first devices) to addressable monetization pathways.
- Go‑to‑market playbooks: tailored routes for manufacturers, platform owners, and service providers covering product roadmaps, pricing ladders, channel mixes, and promotional levers for 12–36 month horizons.
- Supply‑chain and sourcing playbook: supplier tiering, dual-sourcing templates, and risk mitigation actions tied to semiconductor export controls and display/DRAM bottlenecks.
- Regulatory and compliance compendium: concise checklists for battery safety, energy efficiency, and import/export constraints in key markets, with compliance milestones mapped to product launch timelines.
- M&A and partnership screening tool: heuristics and a scoring matrix to identify tuck-in versus transformational targets across hardware, middleware, IP, and cloud streaming services.
- Financial impact models: scenario-based P&L and ROI templates that quantify trade-offs between performance, battery life, and cost-to-serve for alternative product architectures.
These modules are illustrated through industry examples, anonymized supplier case studies, and an adaptative Excel model that buyers can use to test their own strategies. Note: proprietary segment-level tables and confidential supplier cost curves are available exclusively in the paid report.
Competitive Landscape — Who to Watch (and Why)
The portable consoles ecosystem now mixes long-established first‑party platform owners with a robust field of innovative OEMs and startups. Strategic posture differs markedly across these players:
- Nintendo Co., Ltd. — continues to leverage first‑party IP and platform control, having launched its next‑generation hybrid platform in 2025. Nintendo’s integrated hardware-software model remains the benchmark for ecosystem monetization and launch cadence planning.
- Valve Corporation — drives the PC‑handheld segment through SteamOS and the Steam Deck lineage. Valve’s emphasis on silicon/architectural jumps for its next iteration highlights the performance-vs-battery trade-offs that define premium handheld R&D.
- ASUS ROG / Microsoft (Xbox partnership) — entrants on the Windows-based handheld side are pushing PC-class performance into portable form factors, backed by close partnerships for ecosystem services (Game Pass) and advanced silicon platforms.
- Lenovo — experimenting with form factor innovation (foldable POLED concepts) and cross-OS strategies that blur the line between portable PC and gaming console, signaling new design paths for differentiation.
- Sony Interactive Entertainment and Microsoft/Xbox — both play strategic roles via streaming, remote-play, and platform-level integrations rather than competing purely on hardware economics.
- Specialist OEMs (AYANEO, GPD, Razer, Logitech, and boutique players) — continue to push niche performance, ergonomics, and cloud-specific devices; supply volatility and rising component costs are already shaping product availability and pricing strategies.
Recent corporate moves — from Nintendo’s 2025 product launch to ASUS/Microsoft handheld releases and prototype concepts unveiled by Lenovo — demonstrate an industry balancing iterative platform refreshes with experiments in form factor and cloud integration. At the same time, announcements of pre‑order suspensions and development constraints reflect cost and supply tensions that will be front‑and‑center in 2026 decision cycles.
Key Industry Dynamics to Prioritize in 2026
- Component and input cost pressure: high-density DRAM, advanced OLED/POLED panels, and premium silicon contribute materially to BOM inflation. Procurement strategies must balance cost, lead times, and performance alignment to avoid margin erosion.
- Semiconductor geopolitics: export controls and trade frictions continue to shape sourcing options for advanced processors. Firms should build resilient supplier maps and validate alternate silicon paths early in the product development cycle.
- Regulatory/compliance risk: energy efficiency and battery safety certifications are moving targets across regions; early engagement with certification labs reduces launch delays and recall risk.
- Convergence of models: hybrid consoles, portable PC devices, and cloud-first handhelds are converging on user expectations—seamless access to content, fast switching between local and cloud play, and cross‑device saves—creating opportunities for layered monetization beyond hardware sales.
- Concentration and partnership economics: dominant ecosystem owners retain outsized power; partnerships (OS licensing, store integrations, cloud access) are often the fastest route for smaller OEMs to scale discovered user bases.
Practical Recommendations for 2026 Planning
Below are the high‑impact actions we advise management teams to consider when finalizing 2026 plans:
- Prioritize supplier flexibility: create tiered sourcing strategies for silicon, displays, and batteries; negotiate volume options with second‑source commitments to protect launch timing.
- Design for modularity and trade-offs: make explicit design choices between peak performance and battery life, and plan SKU tiers that monetize both hardcore and casual segments without cannibalizing price tiers.
- Leverage ecosystem partnerships: secure content and cloud streaming agreements early; exclusive content windows or integrated subscription bundles materially increase retention.
- Invest in certification and compliance early: front-load regulatory testing and safety certification into roadmaps to avoid last‑minute delays in key launch markets.
- Use strategic pricing and channel experimentation: test online-first drops for demand sensing, while preserving curated offline experiences for premium devices to maintain brand prestige.
- Screen M&A for capability gaps: prioritize acquisitions that fill software/platform gaps (cloud integration, middleware), or that add IP and content libraries rather than commodity hardware manufacturing alone.
Why This Report Matters for 2026 Decisions
2026 will be characterized by selective hardware upgrades, fierce competition for content and services, and continued supply-side friction. Leaders who treat the portable gaming segment as a system-level challenge—optimizing hardware, software, supply, and regulatory timelines in tandem—will secure the best outcomes. PW Consulting’s report provides the consolidated market sizing, concentration diagnostics, scenario-tested financial models, and concrete playbooks executives need to make those choices with confidence.
For strategy teams preparing budgets, for product teams finalizing 12–24 month roadmaps, and for corporate development groups evaluating deals, the report converts industry complexity into executable next steps while preserving confidential details and vendor-level data for licensed subscribers.
Next Steps
PW Consulting will publish the full Worldwide Portable Gaming Consoles Market report with segmented analysis, supplier cost curves, and downloadable decision tools. The public executive preview above demonstrates the report’s strategic orientation without publishing the detailed segmentation tables and proprietary supplier data (which are reserved for purchasers). To obtain the complete report, licensing options, and bespoke advisory support, please visit the PW Consulting reports portal or contact our industry practice lead directly for custom briefings and model access.
PW Consulting — helping leadership teams convert market insight into measurable strategic advantage for the decade ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Gaming Consoles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com