

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 2D Game Market Poised for 7.5% CAGR to 2032 as Asia Pacific Leads with USD 27,593.36 Million

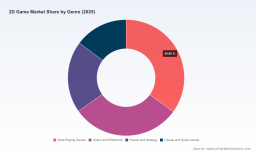
Worldwide 2D Game Market: A Strategic Preview for 2026 — PW Consulting Industry Brief
PW Consulting’s new Worldwide 2D Game Market research—based on a comprehensive historical window (2020–2025) and forward-looking forecasts (2026–2032)—provides an essential strategic compass for executives, investors, and studio leaders preparing decisions in 2026. Our modelling indicates the 2D game market reached approximately USD 55.2 billion in 2025 and is expected to grow at a 7.5% compound annual growth rate through 2032, exceeding USD 91.5 billion by the end of the forecast period. Market concentration remains notably diffuse: top-three firms account for less than one-fifth of industry revenues, underscoring a competitive landscape where agility and IP positioning are decisive.
Worldwide 2D Game Market
Why this report matters for 2026 planning
- Timing of strategic moves matters: With the market entering a sustained growth phase, 2026 is a pivot year for investments in IP revitalization, tooling, and discoverability mechanisms that compound value through 2032.
- Platform-neutral opportunity: 2D development is structurally cross-platform; choices about engine, monetization, and distribution in 2026 define addressable reach and unit economics for the next product cycle.
- Fragmentation creates arbitrage: Low top-player concentration creates acquisition and partnership windows for mid-market consolidators and service providers focused on art, porting and QA.
- Regulatory and distribution risk: Evolving digital competition rules mean that companies must redesign discovery and store strategies to retain margins and visibility.
What the report delivers (practical contents)
This research is designed as an operational playbook for decision-makers. Key deliverables include:
Worldwide 2D Game Market
- Bottom-up market sizing and validated forecast runs with scenario sensitivity (base, upside, downside) to stress-test 2026 investment cases.
- Monetization and pricing playbooks calibrated to contemporary consumer willingness-to-pay data and subscription dynamics.
- Engine and tooling decision frameworks comparing total cost of ownership, developer productivity, and platform portability for leading 2D engines (commercial and open-source).
- Go-to-market templates for discovery and marketing optimization across stores and direct channels, including KPI maps and CAC/LTV sensitivity tables.
- Outsourcing and partnership scorecards to evaluate art, animation, QA, localization and porting partners, with recommended contractual guardrails for quality and IP control.
- M&A screening filters and target archetypes for strategic acquirers and private equity entrants seeking scale in 2D IP, live-ops capabilities, or specialty studios.
- Risk matrix covering regulatory developments, platform rule changes, and labor/geopolitical exposure—paired with mitigation playbooks.
Note: In keeping with the “trailer” principle of this release, we present macro market sizing and high-level conclusions here while preserving the granular regional, platform and genre split tables (and underlying model) for the full report. Interested readers and clients can access detailed segment-level data, downloadable models, and company scorecards on our report page.
Worldwide 2D Game Market
Competitive landscape: how incumbents and enablers shape 2026 outcomes
The 2D landscape blends long-standing platform holders and franchise owners with nimble indie publishers, engine vendors, and specialized service providers. Our analysis highlights strategic positions and near-term moves for core players:
- Nintendo Co., Ltd. (Kyoto, Japan) — Remains the benchmark for IP-driven 2D experiences. Nintendo’s continued investment in marquee franchises keeps premium 2D design principles at the industry forefront. For competitors, Nintendo’s approach underscores the value of sustained IP stewardship and platform-tailored design.
- Capcom Co., Ltd. (Osaka, Japan) — With deep expertise in sprite-based action and fighting genres, Capcom’s catalog is a reminder that heritage IP can be monetized across remasters, episodic DLC, and competitive circuits.
- Konami Holdings Corporation (Tokyo, Japan) — Konami’s announced 2026 releases (e.g., new Castlevania projects) highlight a resurgent appetite for retro-styled titles with modern production values; licensors and co-development partners should prepare to scale art and QA pipelines.
- Devolver Digital (Austin, USA) — The indie curator model continues to validate the commercial potential of distinctive artistic 2D projects; publishers and platform holders should prioritize discoverability deals and limited-time promotions to surface these titles.
- Engine and tool vendors — Unity, Godot, YoYo Games, Epic — Engine strategy is a core determinant of development velocity and cost. Unity’s recent 2D tool updates (Unity 6.3 LTS) improve sprite and lighting workflows; open-source Godot continues to gain traction among indie teams seeking lightweight cross-platform options; GameMaker remains a preferred rapid-prototyping tool for many 2D creators. These dynamics make 2026 a decisive year for teams to lock in engine roadmaps and support arrangements.
- Service providers — Keywords Studios, Virtuos, Room 8 Group, Kevuru, Stepico — The outsourcing market for 2D art, animation, porting and QA is mature and geographically distributed. Buyers should emphasize IP security, transferability, and multi-site sourcing to lower geopolitical risk while preserving creative control.
Recent developments and their strategic implications
- Tooling innovation: Unity’s 6.3 LTS release (Mar 2026) strengthens 2D pipelines—expect shorter iteration cycles and reduced per-project art overhead for studios that adopt its best practices.
- Authoring democratization: Teasers from RPG Maker creators signaling HD-2D support point toward a lower barrier for high-polish retro aesthetics—this will expand the indie pipeline and intensify competition in art-driven niches.
- IP resurgence: Major publishers announcing stylized 2D titles for 2026 illustrate a strategic rotation toward heritage IP remakes and stylized new IP—publishers should be ready to monetize across DLC, collector editions, and cross-media tie-ins.
- Monetization shift: Advisory reports from leading consultancies have called out tiered pricing and subscription models as major determinants of indie and 2D monetization strategies; gaming companies must run 2026 experiments to optimize frictionless purchase flows and retention.
Actionable recommendations for 2026 (prioritized)
- Publishers with IP: Prioritize remaster and spin-off programs with modular production scopes. Use staged investments and live-ops pilots to fund creative experimentation while mitigating portfolio risk.
- Indie studios: Lock in engine and toolchains early, adopt community-driven marketing (alpha access, creator partnerships), and select outsourcing partners with proven 2D pipelines to accelerate time-to-store.
- Service providers: Expand flexible delivery models (fixed-price art packs, retainer QA) and build compliance tooling for IP protection to win publisher deals amid rising regulatory scrutiny.
- Investors and acquirers: Use concentrated screens for studios with repeatable live-ops or high-margin indie catalogs; valuation should stress-test discovery risk and platform fee exposures.
- Platform holders and stores: Invest in curation and discovery signals for 2D titles to reduce dependency on paid user acquisition while strengthening retention pathways.
Risks to monitor
- Discoverability and platform rules: Ongoing digital competition regulation will alter store economics and search dynamics; plan alternative direct-to-consumer channels.
- Talent and geopolitics: Outsourcing hubs remain critical but concentrated; diversify supplier geographies and ensure continuity plans for art and QA operations.
- Monetization sensitivity: Consumer tolerance for price rises is mixed; companies must A/B test pricing and subscriptions to avoid conversion cliffs.
PW Consulting’s Worldwide 2D Game Market report is tailored to inform the tactical choices that will define winners and followers through 2032. This brief highlights the strategic contours—our full report contains the complete segment-level breakdowns, scenario models, executive dashboards, and downloadable datasets required to build confident 2026 budgets, M&A screens, and product roadmaps.
To access the full dataset, company scorecards, and our executable playbooks, please visit the PW Consulting report page or contact our industry practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Game Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com