

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide WIPS Market Poised to Expand at a 14.2% CAGR Through 2032 as Demand for Wireless Security Surges

Worldwide Wireless Intrusion Prevention System (WIPS) Market — 2026 Strategic Preview
As organizations enter 2026, wireless attack surfaces have become a frontline battleground for data security, regulatory compliance, and operational resilience. PW Consulting’s new market study on the Worldwide Wireless Intrusion Prevention System (WIPS) market synthesizes five years of historical movement and a seven-year outlook to equip enterprise decision-makers with the strategic intelligence required to prioritize investments, architect defenses, and select vendor partners. This is a preview designed to demonstrate the depth of our analysis and why the report should be a primary source for C-suite, security program leaders, and procurement teams seeking an actionable roadmap for 2026 — while reserving detailed segment-level tables and proprietary vendor scores for the full report.
Worldwide Wireless Intrusion Prevention System (WIPS) Market
Market Trajectory: Why the Numbers Matter for 2026 Planning
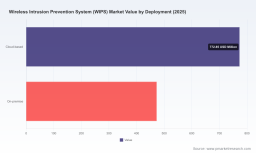
WIPS has transitioned from a niche point solution into an operationally critical capability embedded across networking, security, and compliance programs. PW Consulting’s macro view tracks an acceleration in market value from the early 2020s into the mid-2020s, culminating in an estimated global market size of approximately USD 1,245.5 Million in 2025. Our forecast anticipates continued expansion through the 2026–2032 window at a compound annual growth rate (CAGR) of 14.2%, with market momentum driven by regulatory mandates, expanding Wi‑Fi spectrum usage, and enterprise cloud transformation.
Worldwide Wireless Intrusion Prevention System (WIPS) Market
For decision-makers, this growth curve signals two practical realities for 2026: first, WIPS is no longer optional for organizations that handle sensitive data or operate in regulated sectors; second, the supplier ecosystem is consolidating, making vendor selection and integration strategy materially important for long-term operational effectiveness.
Worldwide Wireless Intrusion Prevention System (WIPS) Market
What the PW Consulting Report Delivers — Practically Useful, Immediately Actionable
- Executive decision framework: A concise, prioritizable checklist for CISOs, CIOs, and security architects to translate regulatory exposure and business risk into deployment timelines and budgetary scenarios.
- Technology and architecture guidance: Comparative analysis of WIPS delivery models, recommended integration patterns with WLAN controllers, SD‑WAN fabrics, and SIEM/SOAR workflows, and migration paths for organizations moving from air‑gapped to cloud‑managed operations.
- Use-case playbooks: Operational runbooks for detecting and mitigating common wireless threats (rogue APs, evil twin attacks, deauthentication/DoS events, spectrum anomalies), including detection thresholds, containment workflows, and post‑incident validation steps.
- Vendor and partner considerations: A vendor-agnostic evaluation framework covering integration maturity, threat telemetry fidelity, false-positive management, and field‑service capabilities — plus a proprietary benchmarking appendix available in the full report.
- Procurement and TCO model: A customizable total-cost-of-ownership model that helps procurement teams compare cloud-managed vs. on‑premise options across personnel, licensing cadence, and lifecycle refresh implications.
- Regulatory and compliance mapping: Practical alignment of WIPS capabilities to PCI DSS, HIPAA guidance, NIS2 obligations, federal frameworks such as FedRAMP/FISMA, and spectrum policy changes — highlighting compliance levers you can act on in 2026.
Competitive Landscape — Who Matters and Why
The WIPS vendor ecosystem includes established networking titans, security-first vendors, and specialized wireless monitoring providers. The market exhibits a measurable degree of concentration: the top three suppliers collectively control a meaningful share of market revenue, and the top five extend that dominance further — facts that underscore partner stability and integration depth as decisive procurement criteria.
- Cisco Systems Inc. (San Jose, CA) — Cisco remains a dominant integrator, embedding WIPS capabilities into its Catalyst and Meraki portfolios and leveraging DNA Center for continuous RF spectrum monitoring and multi‑layer threat containment. Recent enhancements emphasize AI‑driven anomaly detection in cloud management to improve detection fidelity.
- HPE Aruba Networking (Santa Clara, CA) — Aruba’s RFProtect suite continues to focus on real‑time rogue AP and client monitoring tightly coupled with Aruba Central, appealing to enterprises that prioritize centralized WLAN lifecycle and security management.
- Fortinet, Inc. (Sunnyvale, CA) — Fortinet’s Secure Wireless LAN approach integrates WIPS into the broader FortiOS security stack, delivering automation and high‑accuracy detection that resonates with organizations seeking unified security policy enforcement.
- Extreme Networks (Morrisville, NC) — Extreme weaves WIPS functionality into its ExtremeWireless and AirDefense analytics, offering continuous threat hunting capabilities for complex campus and branch environments.
- WatchGuard Technologies (Seattle, WA) — WatchGuard targets SMBs and distributed enterprises with cloud‑managed WIPS and proprietary techniques that aim to reduce false positives and simplify operations.
- Check Point Software Technologies (Tel Aviv, Israel) — Check Point extends its Infinity platform into the wireless perimeter, enabling holistic policy orchestration across wired and wireless domains.
- NetScout Systems, Inc. (Westford, MA) — NetScout pairs WIPS with network performance monitoring to provide correlated diagnostics for wireless incidents that originate from RF conditions or pathologies.
- IBM Corporation (Armonk, NY) — IBM integrates WIPS capabilities within its security services and threat management portfolio, focusing on enterprise-scale deployments and managed offerings.
- Ruckus Networks (CommScope) (Claremont, NC) — Ruckus continues to package WIDS/WIPS into controllers and access points to address DoS mitigation, rogue detection, and operational simplicity in dense environments.
- Arista Networks (Santa Clara, CA) — Arista provides classification and protection mechanisms via CloudVision and CUE, appealing to customers that prioritize automated device profiling and policy enforcement.
Our full benchmarking appendix maps these vendors across integration maturity, telemetry quality, automation, and managed-service readiness. In this preview we emphasize that enterprise selection should balance innovation (AI/ML detection, cloud analytics) against operational risk (false positives, lifecycle support, and field services).
Regulatory, Spectrum, and Market Dynamics Shaping 2026 Decision-Making
- Regulation is a primary demand driver: Recent mandatory updates and guidance — including PCI DSS version 4.0, updated HIPAA security guidance, and NIS2 enforcement — elevate continuous wireless monitoring from best practice to compliance requirement in many sectors. Organizations processing regulated data must treat WIPS as a control that bridges network security and compliance reporting.
- Federal procurement and certification pressure: U.S. federal agencies are increasing allocations toward wireless monitoring within FedRAMP/FISMA frameworks, and government certification initiatives (including commercial solutions for classified contexts) are shaping procurement preferences for validated solutions.
- Spectrum policy and technology shifts: Expanded authorized use of the 6 GHz band and broader Wi‑Fi 6E adoption increase the RF footprint enterprises must monitor. This expands the scope of WIPS functions from rogue AP detection toward continuous spectrum analytics, capacity monitoring, and coexistence management.
- Industry consolidation and channel dynamics: Market concentration among a few leading suppliers increases the importance of partner ecosystem strategy. Managed service providers and channel partners are emerging as critical accelerants for organizations that lack in-house wireless security expertise.
Strategic Imperatives for 2026 — A Practical Checklist
- Operationalize risk-based deployment: Start with high‑risk zones (payment processing, patient-care areas, critical infrastructure) and instrument those perimeters with WIPS capabilities that map directly to compliance controls.
- Design for integration and observability: Ensure WIPS telemetry is ingested into central SIEM/SOAR pipelines and correlated with endpoint and identity signals to reduce dwell time and enable automated containment.
- Adopt hybrid architectures thoughtfully: Cloud‑managed WIPS accelerates analytics and reduces local operational overhead, but on‑premise components remain essential where latency, sovereignty, or air‑gap constraints exist. Use our TCO model to stress-test options against operational SLAs.
- Calibrate detection thresholds and validation workflows: Prioritize solutions that deliver high signal‑to‑noise ratios and provide easy tuning to minimize false positives and alert fatigue.
- Factor vendor stability into SLAs: Higher market concentration means vendor roadmaps and channel coverage directly affect upgrade paths and incident response — include roadmap and support resilience clauses in procurement agreements.
How to Use This Preview — And Where to Find the Full Intelligence
This article is a strategic trailer: it outlines the market dynamics, vendor landscape, regulatory inflection points, and the practical frameworks you’ll need for 2026. PW Consulting’s complete Worldwide WIPS Market report contains the granular segmentation, vendor scorecards, downloadable TCO spreadsheets, regional deployment models, and proprietary scenario analyses that security leaders require to finalize budgets, vendor shortlists, and deployment roadmaps.
If you are preparing a 2026 security investment plan, migrating to Wi‑Fi 6E, or responding to regulatory obligations for wireless monitoring, the full report provides the empirical detail and templates to move from strategy to execution. For executives, the one‑page strategic exerpt and vendor comparison matrix will accelerate board briefings and procurement timelines; for architects, the operational playbooks and integration patterns will shorten pilot cycles and reduce rollout risk.
Final Note for Decision-Makers
WIPS has crossed the threshold from specialized capability to foundational control. The market’s robust growth — from roughly mid‑hundreds of millions in the early 2020s to an estimated USD 1,245.5 Million in 2025 and a multi‑billion‑dollar outlook by the end of our 2032 forecast window — reflects this shift. With a sustained CAGR of 14.2% across the forecast period and a supplier landscape where leading vendors collectively hold significant shares, 2026 is the year to move beyond proofs‑of‑concept and embed wireless intrusion prevention into your enterprise security fabric. PW Consulting’s full report is designed to be the playbook that gets you there — with the detailed segment data, vendor benchmarks, and executable templates you’ll need to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Intrusion Prevention System (WIPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com