

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hypersomnia Drug Market to Surge from USD 5,001.21 Million in 2025 to USD 10,060.31 Million by 2032 at a 10.5% CAGR

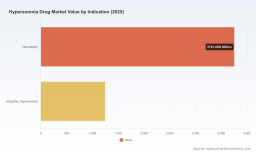
Worldwide Hypersomnia Drug Market — Strategic Outlook 2026: PW Consulting Report Preview
PW Consulting today releases a strategic preview of our upcoming Worldwide Hypersomnia Drug Market report, prepared to inform and accelerate executive decisions through 2026 and beyond. The global hypersomnia therapeutic market has expanded rapidly over the last half‑decade and is now at a scale that demands strategic clarity: from a documented base of approximately USD 3.12 billion in 2020 the market exceeded USD 5.0 billion in 2025, and our modelling conservatively projects that it will double by 2032 to roughly USD 10.06 billion — an aggregate trajectory consistent with a 10.5% compound annual growth rate over the forecast period (2026–2032).
Worldwide Hypersomnia Drug Market
Why this report matters for 2026 decision cycles
-
Near‑term inflection points. A concentrated competitive landscape combined with a wave of near‑term regulatory and clinical readouts creates a compressed window for strategic action in 2026. Companies that sequence portfolio, licensing, pricing and access activities to these events will capture disproportionate value.
Worldwide Hypersomnia Drug Market -
Commercial model disruption. Entry of authorized generics and lower‑sodium branded alternatives has already begun to reshape payer negotiations and patient access paradigms. Corporates must reassess revenue models, discounting strategies, and channel economics.
Worldwide Hypersomnia Drug Market -
Technology and mechanism shifts. The transition from symptomatic wake‑promotion and oxybate management to targeted orexin receptor agonism and other mechanistic innovations alters product development priorities and long‑term market share pools.
-
Regulatory and controlled‑substance complexity. REMS frameworks and controlled‑substance scheduling materially affect distribution, manufacturing and pharmacovigilance requirements — governance that must be embedded in commercial and operational plans.
What the PW Consulting report delivers (practical, executable content)
-
Proprietary demand model and scenario engine: an interactive, sensitivity‑driven market model that quantifies outcomes across patient‑access, pricing, and clinical adoption scenarios — designed to be used in board‑level strategic workshops.
-
Event‑driven decision calendar: prioritized near‑term milestones (regulatory dates, Phase‑3 readouts, filing acceptances, and major M&A) mapped to recommended corporate actions and trigger points.
-
Commercial playbooks by asset archetype: differentiated GTM templates for oxybate formulations, wake‑promoting agents, orexin agonists and once‑nightly formulations; includes sales force sizing, speciality distribution models and REMS governance checklists.
-
Payer and HTA negotiation frameworks: evidence templates, real‑world study designs and value dossiers tailored to the controlled‑substance and rare‑disease reimbursement environment.
-
Pipeline and competitive heatmap: independent assessment of clinical-stage assets, mechanism overlap, and probability‑adjusted launch windows to guide in‑licensing, partnering and divestiture strategies.
-
Manufacturing and supply chain risk matrix: compliance requirements for controlled‑substance production, inventory control strategies, and contingency options to protect launch timelines and mitigate shortages.
-
M&A and partnering screen: prioritized target lists with playbooks for integration, carve‑outs and bolt‑on acquisitions aligned to five common corporate objectives (scale, capability, pipeline, geography, cost).
Competitive landscape — strategic implications
The hypersomnia market remains an oligopolistic segment characterized by a handful of incumbents controlling a material share of current revenues while a set of clinically differentiated entrants and generics are actively reshaping access and pricing dynamics. Our market concentration analysis shows that the top three firms account for close to seven in ten dollars today, and the top five capture over four fifths of the market — a structure that supports premium pricing but is vulnerable to rapid share reallocation once biosimilar/generic and novel mechanism entrants scale.
Key strategic observations from our company‑level analysis include:
-
Incumbent branded innovators maintain advantaged positions through indication breadth, REMS‑enabled distribution and entrenched clinical relationships. Therapies that combine differentiated safety/administration profiles and strong label claims continue to command durable commercial value.
-
Authorized generics and recently approved ANDAs are compressing price differentials in core oxybate categories, accelerating payer substitution and volume‑price tradeoffs. This trend increases the urgency for branded players to defend with value‑added services (adherence programs, RWE) or to pivot to differentiated formulations.
-
Mechanism innovation — particularly orexin receptor agonists and selective orexin‑2 receptor compounds — has emerged as a true inflection point. Regulatory recognitions and breakthrough designations for orexin programs validate both scientific rationale and commercial potential; these assets pose medium‑term threats to symptomatic classes if efficacy and tolerability translate into superior real‑world outcomes.
-
M&A and portfolio reshaping are active levers. Recent acquisition activity underscores strategic appetite among large pharma to augment orexin pipelines quickly; mid‑sized and specialty players will need to consider partnering or targeted acquisitions to remain competitive.
Regulatory, reimbursement and access dynamics to watch
-
Controlled‑substance regulation and REMS frameworks remain a gating factor for distribution and patient onboarding. Companies must resource specialized compliance capabilities and flexible distribution partnerships to avoid launch delays and access bottlenecks.
-
Lower‑sodium oxybate formulations and once‑nightly dosing represent meaningful clinical and commercial differentiators. Where clinical data supports improved tolerability or adherence, payers will consider preferential placement — but this will hinge on robust cost‑effectiveness and RWE evidence.
-
Expanded availability of generics and authorized generics increases payer leverage but also enlarges total addressable patient access. The net commercial outcome depends on the balance between price erosion and incremental volume capture.
Actionable strategic recommendations for 2026
-
Prioritise portfolio clarity: classify assets into short‑term cash generators, mid‑term defendable franchises and long‑term disruptive bets. Assign tailored commercial and evidence strategies to each cluster.
-
Accelerate payer evidence generation: invest in targeted RWE and health economic studies now to support formulary negotiations when generics pressure pricing and new entrants seek premium access.
-
Hedge supply‑chain and distribution risk: build redundancy for controlled‑substance manufacturing and evaluate authorized generic agreements to preserve market share under differing price scenarios.
-
Prepare M&A and licensing playbooks: maintain active scouting for orexin‑mechanism programs and differentiated oxybate delivery platforms. Use staged option agreements to manage clinical and regulatory risk.
-
Operationalize REMS and patient support as a revenue‑enabler: design integrated adherence and monitoring services that convert REMS requirements into a commercial advantage and demonstrate real‑world benefit to payers.
Timing is material — near‑term catalysts for 2026 planning
Several concrete milestones in late 2025 and early 2026 have already shifted the competitive calculus and compress the timeline for strategic choices. Clinical program readouts, NDA acceptances and high profile transactions will create windows of opportunity and risk. Firms that align capital allocation, regulatory sequencing and commercial readiness to these catalysts will materially outperform peers over the next 24 months.
Why PW Consulting
PW Consulting combines pharmacoeconomic modelling, regulatory expertise, and deal advisory to translate data into executable corporate decisions. Our hypersomnia practice offers hands‑on experience across REMS‑governed products, orexin‑targeting modalities and specialty distribution networks. The full report — delivered with an editable market model and tailored advisory options — is built to support boardroom decisions, investor diligence and commercial launch planning.
Next steps
-
For immediate strategic support, request our executive briefing package which includes a condensed event calendar and a one‑page decision matrix tailored to your asset class.
-
Access the full Worldwide Hypersomnia Drug Market report for comprehensive scenario outputs, the complete competitive heatmap and our recommended action plans — the preview above is intentionally high‑level to protect detailed segment estimates and proprietary modelling.
Contact PW Consulting to schedule a private briefing and hands‑on model walkthrough. Our advisory team stands ready to convert the report’s insights into a bespoke 90‑day action plan aligned to your fiscal and portfolio timelines.
For detailed analysis of this topic, please visit the official page: Worldwide Hypersomnia Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com