

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting report: Worldwide Methylparaben Market set to expand at a 4.5% CAGR through 2032, driven by rising Asia‑Pacific demand

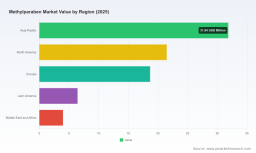
Worldwide Methylparaben Market: Strategic Briefing for 2026 — What Senior Decision-Makers Need to Know
PW Consulting’s latest market study — the Worldwide Methylparaben Market (Base Year: 2025; Forecast Period: 2026–2032) — translates granular chemistry-market intelligence into boardroom-grade guidance. Built from a rigorous review of historical performance (2020–2025), supply-chain telemetry, regulatory landscapes and primary-sourced competitor intelligence, the report is designed as an operational playbook for commercial strategy, procurement, product development and M&A screens in 2026.
Worldwide Methylparaben Market
Why this matters in 2026
Methylparaben remains a staple preservative in cosmetics, pharmaceuticals and select food formulations. After a period of volatility through the early 2020s, the market re-anchored in 2025 at an estimated USD 82.45 Million (base year). Our modeled outlook projects a compound annual growth rate (CAGR) of approximately 4.5% across the 2026–2032 forecast window, culminating in a projected market size north of USD 110 Million by 2032. That trajectory — steady, not hyperbolic — creates a very particular set of strategic choices for incumbents and new entrants alike: optimize for margin resilience, regulatory agility and supply diversification rather than pure volume-first expansion.
Worldwide Methylparaben Market
Market dynamics and the levers that will shape 2026 decisions
-
Demand composition and growth profile. Demand continues to be anchored in personal care and pharmaceuticals, with food and certain industrial applications providing counter-cyclical demand in periods of regulatory tightening. Growth is positive but measured; commercial plans predicated on double-digit volumetric expansion are exposed to downside risk if regulatory or raw-material shocks recur.
Worldwide Methylparaben Market -
Supply-side pressures. Feedstock tightness has already transmitted into meaningful cost pressure: p‑hydroxybenzoic acid — the key precursor — experienced a material price step-up in late 2024 due to phenol supply constraints. That episode highlights how upstream specialty-chemical dynamics can rapidly compress manufacturing margins for methylparaben producers and downstream formulators.
-
Regulatory friction and market access. The regulatory environment is mixed and geographically patchwork. Longstanding EU rules constrain cosmetic concentrations and emphasize labeling; China has issued product-specific restrictions that affect pediatric oral-care formulations; and trade remedies have emerged as a near-term market access variable in North America. These regulatory vectors are not binary; they reshape product positioning, labeling, and go-to-market models.
-
Market structure. The methylparaben market is moderately concentrated: a set of established specialty-chemical and ingredient suppliers account for a substantial share of supply. This creates both supply-side stability and competitive pressure at the top end, while mid-tier and regional producers continue to offer local cost advantages and service flexibility.
Competitive landscape — who to watch and what they signal
Our research synthesizes primary interviews, public filings and product catalog analysis to profile the leading suppliers active today. Firms like Eastman Chemical Company, Celanese Corporation and major specialty producers in Asia continue to emphasize regulatory compliance and portfolio premiumization (e.g., low-impurity or pharma-grade offerings). Regional manufacturers from China supply industrial and cosmetic grades globally, often competing on cost and logistics speed. Several observations emerge that are directly actionable for 2026 planning:
-
Quality segmentation is widening. One global incumbent has recently updated REACH certifications for EU-facing grades, while another released an expanded portfolio with lower-impurity pharma options in early 2024. These moves indicate a bifurcation of supplier strategies: regulatory- and quality-led premiumization versus cost/scale-led commodity supply.
-
Export and trade tactics matter. Tariff and trade remedy actions — including preliminary anti‑dumping measures in key import markets — have altered commercial calculus for exporters and importers alike. Sourcing teams must build tariff-scenario playbooks into 2026 budgets.
-
Regional supply hubs are resilient but exposed. Asian producers provide essential volume and proximity to large formulators, yet they remain exposed to feedstock price swings and periodic export scrutiny. For formulators, a two- or three-source procurement approach by geography will be a best practice in 2026.
Regulatory & raw-material intelligence: immediate implications
-
Regulatory compliance is table stakes. EU concentration limits and mandatory labeling requirements, regional product-use restrictions in certain markets, and active trade remedy investigations mean that product specifications and documentation must be continuously audited. For product teams, this translates into prioritized investments in regulatory affairs capabilities and traceability enhancements.
-
Feedstock volatility requires hedging and supplier collaboration. The late‑2024 p‑hydroxybenzoic acid price shock underscores the need for integrated cost models and supplier partnerships. Where possible, secure multi-year conditional supply contracts, co-invest in process improvements with feedstock suppliers, or explore forward-buying strategies for high‑impact raw materials.
What the PW Consulting report delivers (practical, decision-ready content)
This study is structured to convert market intelligence into executable choices. Highlights of the deliverables include:
-
Transparent market sizing and a seven-year forecast model (2026–2032) with scenario sensitivity to feedstock price, regulatory tightening and demand shocks.
-
An operationally focused segmentation framework that maps grades, applications and buyer archetypes to procurement and product-development playbooks (note: detailed segment tables and regional/application splits are available exclusively in the full report).
-
Supplier profiles and capability matrices that benchmark quality certifications, capacity posture, and export footprints for the key global and regional producers.
-
Regulatory tracker and rapid-response templates that operational teams can deploy to assess market-entry risk and labeling changes in prioritized jurisdictions.
-
Commercial and M&A decision tools: valuation primers, synergy checklists, and integration risk maps tailored to target archetypes (technology-led specialty grades vs. volume-focused regional producers).
Strategic actions PW Consulting recommends for 2026
-
Optimize product-mix for margin resilience. Prioritize development and procurement of higher-spec grades where formulation stability and regulatory compliance command a pricing premium. Reduce exposure to commodity-grade volatility through mix adjustments and differentiated SKUs.
-
Harden supply chains. Implement a multi-tier sourcing strategy that combines global incumbents for compliance-backed supply and selected regional partners for cost and lead-time flexibility. Negotiate contingency clauses and visibility into feedstock sourcing to manage p‑hydroxybenzoic acid price risk.
-
Embed regulatory scenario planning into NPD and market-entry decisions. Build a three-track approval and labeling playbook for priority markets and test product variants that mitigate single-market regulatory exposure — especially for infant and pediatric formulations.
-
Revisit pricing tactics. Shift from fixed, list-based pricing to adaptive pricing models tied to raw-material indices and regulatory-cost pass-through clauses. This preserves margins without sacrificing competitiveness.
-
Targeted inorganic options. Use M&A to acquire specialized grades, certification capabilities or regional distribution footprints rather than generic volume. Smaller bolt-on acquisitions or strategic JV structures can accelerate access to compliant, low-impurity product lines while mitigating integration risk.
-
Invest in transparency and traceability. Competitive differentiation will increasingly come from demonstrable provenance, batch-level documentation and regulatory-ready dossiers. For B2B customers, traceability is becoming a procurement decision criterion.
How PW Consulting’s intelligence de-risks 2026 choices
Our report is designed as a short-cycle decision tool for C-suites and functional leaders. It combines a quantitative forecast (CAGR 4.5% across 2026–2032), scenario-tested downside cases, and supplier-level intelligence to create an integrated view of opportunity and risk. The outcome: a pragmatic set of prioritized actions you can operationalize in quarters, not years.
Concluding perspective
Methylparaben’s market is neither booming nor terminally in decline; it is in a phase of quality-driven maturation where regulatory, raw-material and trade dynamics define winners and losers. 2026 will be a watershed year for organizations that either shore up procurement and compliance capabilities or accelerate product premiumization. PW Consulting’s Worldwide Methylparaben Market report gives strategic leaders the market context, competitive insights and practical tools to make those choices with confidence.
To access the full dataset, detailed segment tables, supplier scorecards and the scenario forecast workbook that underpin these findings, visit the PW Consulting report page and download the full Worldwide Methylparaben Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Methylparaben Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com