

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Offshore Riser Systems Market Poised for 6.52% CAGR in 2026–2032, Signaling Strong Growth

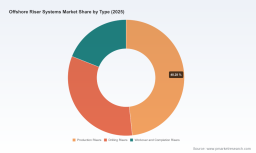
Worldwide Offshore Riser Systems Market — Strategic Imperatives for 2026 Decision‑Makers
PW Consulting’s newest market research brief on the Worldwide Offshore Riser Systems Market provides a disciplined, practitioner‑grade roadmap for companies making procurement, investment, and portfolio decisions in 2026. Built on a 2025 base year and a granular historical series (2020–2025), the study projects the market through 2032 and quantifies a mid‑single‑digit growth trajectory (CAGR 6.52% across the 2026–2032 forecast window). The market, measured in USD (revenue unit: Million), demonstrates clear recovery and expansion dynamics: from the 2025 baseline to the 2032 projection the study identifies sustained demand uplift driven by a mix of brownfield redevelopment, deepwater program restarts, and strategic exports infrastructure.
Worldwide Offshore Riser Systems Market
Why this report matters for 2026
-
Timing: 2026 will be a pivotal year for offshore riser decisions because project sanctioning is concentrating on a smaller set of high‑return developments as global upstream capex is expected to tighten (consensus estimates point to a modest decline in upstream capex year‑on‑year in 2026 amid oil price volatility).
Worldwide Offshore Riser Systems Market -
Regulatory inflection: Updated standards for dynamic risers and riser integrity management (notably API Standard 2RD third edition and continuing ISO/API specifications) are already changing design baselines and contractual acceptance criteria for floating production systems.
Worldwide Offshore Riser Systems Market -
Supply‑chain pressure: Volatility in steel and tubular markets, plus concentrated fabrication capacity for flexible and hybrid riser systems, will materially affect lead times and procurement risk profiles through the year.
-
Competitive windows: A small number of large EPCI and SURF contracts announced or tendered at the end of 2025 and into early 2026 create narrow execution windows and potential cascading tender opportunities or bottlenecks for suppliers and integrators.
What the report delivers (practical, boardroom‑ready)
-
Validated market sizing and forward scenarios — a defensible 2025 baseline and 2026–2032 forecast with sensitivity cases tied to oil‑price and capex glidepath assumptions.
-
Project pipeline mapping — a prioritized catalogue of near‑term and medium‑term projects that drive riser demand (ranked by sanction probability, complexity, and execution timing).
-
Procurement playbooks — contract structures, commercial levers, and phased delivery approaches to mitigate long lead times for specialty pipes, flexible flowlines, and module fabrication.
-
Supply‑chain stress tests — material cost scenarios (including tubular price bands and freight/FOB sensitivities), supplier capacity overlays, and recommended inventory / hedging actions.
-
Regulatory and integrity roadmaps — implementation guide for the 2025 API 2RD updates and associated compliance checks for dynamic risers and floating systems.
-
Vendor intelligence suite — qualitative profiles and capability maps for the major solution providers, plus an RFP scorecard template tailored to riser and SURF scopes.
-
Operational playbook — installation sequencing, fatigue management checklists, and integrity monitoring recommendations designed to reduce OPEX and downtime risk during first‑oil ramp‑up.
Key market signals shaping strategy
-
Renewed project activity in specific deepwater basins has lifted near‑term demand: our baseline shows a noticeable uptick in total market value entering 2026, with continued expansion through 2032 under the core scenario.
-
Standards and safety: The 2025 revision of dynamic riser guidance raises the technical bar for floating developments — a shift that benefits vendors with documented fatigue‑resistant designs, integrated integrity systems, and third‑party testing capabilities.
-
Material input volatility: Seaborne tubular and steel markets remain a cost and schedule risk. Our supply‑chain scenarios use recent FOB benchmarks and regional export dynamics to model procurement outcomes and contract exposure.
-
Concentration of delivery capacity: fabrication and specialized riser assembly remain concentrated among a limited set of suppliers and yards. This creates timing and margin opportunities for firms that can offer modular delivery, pre‑assembly, or bundled SURF solutions.
Competitive landscape — what winners are doing
-
Integrated SURF and riser specialists (examples among market leaders) are differentiating by combining design, manufacturing and installation capabilities to own project risk from engineering through hook‑up. These players benefit from scale in flexible riser production and the ability to offer single‑point accountability for complex EPCI scopes.
-
Pure‑play riser equipment manufacturers are sharpening their IP around fatigue resistance, connector technology and buoyancy systems — with an emphasis on modular designs that speed installation and simplify inspection access.
-
Materials suppliers with premium tubular product lines are capturing value by certifying product performance for high‑pressure, high‑temperature (HP/HT) and steel catenary applications; their relationships with major fabricators shorten lead times and reduce substitution risk.
-
Installation contractors that control heavy‑lift and deepwater pipelay assets are leveraging recent contract awards and long‑lead vessel bookings to secure multi‑project itineraries — a strategic advantage that translates into higher utilization and better pricing power.
Recent industry moves to watch
-
Late‑2025 and early‑2026 contract awards and tenders underscore where near‑term demand will concentrate — including large EPCI scopes for deepwater flexible flowlines and risers, and multi‑hundred‑kilometer export pipeline programs with integrated riser interfaces. These opportunities will dominate fabrication schedules and vessel allocations in 2027–2028.
-
Regulatory updates (notably API’s 2025 revision on dynamic risers) are already altering acceptance criteria; operators and vendors must reconcile legacy designs with the new baseline to avoid late‑stage redesigns that inflate cost and push schedules.
-
Major tenders issued by national oil companies and integrated operators are redefining supplier shortlists and opening potential for strategic partnerships or consortium bids to capture end‑to‑end scopes.
Strategic implications by stakeholder
-
Operators and IOC/NOC procurement teams: prioritize locked‑price procurement for long‑lead metallics where possible; mandate early submittal of integrity and fatigue modelling tied to API 2RD compliance; consider staged awards that align fabrication milestones with installation windows.
-
Vendors and fabricators: accelerate modularization and pre‑assembly capabilities; invest in fatigue‑resistant designs and third‑party validation labs; pursue strategic alliances with installation contractors to present bundled, lower‑risk EPCI propositions.
-
Installation contractors and EPCI houses: secure vessel capacity and yard slots through multi‑year charters and joint venture arrangements; expand consultancy services around integrity management to capture aftermarket revenue.
-
Investors and PE sponsors: the market’s mid‑single‑digit CAGR masks attractive pockets of return in servicing brownfield redevelopment and export infrastructure where long‑term contracted cash flows can be structured; focus due diligence on counterparty concentration risk in raw materials and vessel availability.
Recommended 2026 playbook — eight concrete actions
-
Run a 0/6/18‑month procurement plan: lock critical tubulars and specialty items early; use staged payments and acceptance tests to align vendor cash flow with fabrication milestones.
-
Rebase design criteria against API 2RD (2025): require vendors to submit compliance matrices and fatigue test evidence as part of technical scorecards.
-
Perform supplier capacity stress tests: simulate combined workloads from announced large contracts and nation‑level tenders to identify single‑point failure suppliers.
-
Adopt modular delivery: where feasible, shift to pre‑assembled riser modules to reduce offshore hook‑up time and weather exposure.
-
Hedge material risk: evaluate targeted hedging or strategic stockpiling for priority grades of tubulars and pipe coatings; consider multi‑source strategies for critical inputs.
-
Negotiate installation windows: include liquidated delay clauses and vessel availability guarantees in large EPCI contracts to control schedule spillover.
-
Invest in digital twins and integrity monitoring: early small investments in monitoring hardware and analytics reduce lifecycle OPEX and improve producibility assumptions.
-
Explore JV and alliance models: combine complementary strengths across riser design, fabrication and pipelay to bid competitively on large integrated scopes.
Report toolkit and operational annexes (selected)
-
Scenario‑driven financial model with adjustable oil price and capex inputs and automated outputs for NPV and payback under different procurement strategies.
-
Supplier scorecard templates and RFP language tuned to API 2RD acceptance and fatigue test deliverables.
-
Project‑level pipeline tracker, ranked by sanction probability and expected riser demand intensity.
-
Case studies documenting recent large EPCI programs and how delivery risk was mitigated in procurement and execution.
-
Material price and lead‑time stress scenarios using recent tubular and steel market data to quantify procurement exposure.
PW Consulting’s Worldwide Offshore Riser Systems Market report is designed to be a strategic decision‑support tool for 2026: it translates macro trends and regulatory shifts into concrete procurement, engineering, and commercial actions. The headline numbers — a robust 2025 baseline and a core forecast showing steady expansion through 2032 at a 6.52% CAGR — provide the quantitative frame; the report’s operational annexes and supplier intelligence supply the tactical engine that executives need to convert that frame into defensible project choices.
For firms that need to move from strategy to execution in 2026 — whether to bid, to buy, or to reorganize an offshore S&OP for riser systems — this report is structured to shorten decision cycles and to reduce execution risk. Access to the full data tables, the project‑level pipeline, and the interactive models is available in the complete study; those appendices contain the detailed segmentation, vendor financials, and downloadable procurement templates required to operationalize the recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Offshore Riser Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com