

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Composite Railroad Tie Market at USD 943.15M in 2025 — Poised to Reach USD 1.43B by 2032 (6.12% CAGR)

Worldwide Composite Railroad Tie Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s new market brief on the Worldwide Composite Railroad Tie Market provides the strategic intelligence infrastructure leaders need to make high‑confidence decisions in 2026. Built on a rigorous base year of 2025 and a seven‑year forecast horizon, the report synthesizes market sizing, technology performance data, supplier capability assessments, and field‑trial evidence into a compact playbook for procurement, operations, and investment teams.
Worldwide Composite Railroad Tie Market
Headline market context
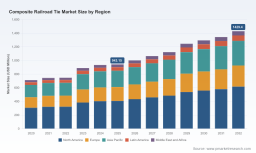
The composite railroad tie market has moved from niche experimentation to mainstream project consideration. Our historical sizing work shows growth from USD 712.14 Million in 2020 to a base‑year market of USD 943.15 Million in 2025. With a compound annual growth rate (CAGR) of 6.12% over the forecast interval, PW Consulting projects market expansion to an addressable size in excess of USD 1.0 Billion in 2026 and reaching approximately USD 1.43 Billion by 2032. Market concentration is meaningful but not prohibitive for new entrants: the top three players account for just under 40% share, and the top five for about 52% — a structure that supports partnership, selective consolidation, and local scale plays.
Worldwide Composite Railroad Tie Market
Why 2026 is a pivotal year for buyers, operators and investors
- Regulatory inflection points are accelerating adoption. Procurement bans and tighter environmental rules in major markets have already redirected specification decisions away from creosote‑treated timber toward recyclable composites.
- Field evidence is maturing. Large‑scale field trials and mass installations carried out by Class I railroads and metropolitan systems have validated installation workflows and early performance claims, significantly reducing execution risk for buyers ready to pilot deployment at scale.
- Industrial consolidation and strategic partnerships are reshaping go‑to‑market dynamics. Recent strategic investments and exclusive supply/marketing agreements are increasing channel reach and industrial capacity for selected suppliers.
- Lifecycle economics and circularity requirements are becoming board‑level procurement criteria. Operators are shifting the conversation from unit price to whole‑life cost and end‑of‑life recyclability.
What the PW Consulting report delivers — practical, transaction‑ready content
- Proven market sizing and demand model (2020–2025 historical, 2026–2032 forecast) with sensitivity scenarios and adoption curves that reflect both conservative and accelerated deployment pathways.
- Segmentation framework by material class, application tier and purchasing archetype, paired with supplier positioning maps — the report intentionally highlights segment dynamics while reserving detailed sub‑segment datapoints for the full licensed report.
- Supply‑side diagnostics including plant capacity overlays, raw material inputs (post‑consumer plastics, glass fiber reinforcements), and a risk heat map for feedstock volatility and logistics bottlenecks.
- Supplier scorecards and a procurement playbook — independent technical assessments (standards/approvals), warranty regimes, installation productivity benchmarks and a procurement checklist for pilots through commercial roll‑out.
- Lifecycle cost models and total‑cost‑of‑ownership templates that let you compare timber, concrete and composite alternatives under user‑configurable assumptions (replacement rates, discounting, maintenance intensity).
- Field‑trial case studies and failure‑mode analysis summarizing installation outcomes, NPV impact, and operational lessons learned from heavy‑haul and metro environments.
- Deal playbook: partnership structures, JV templates, off‑take and capacity financing options, plus an M&A screening matrix for strategic acquirers and financial sponsors.
Competitive landscape — who matters and what to watch
The competitive set includes long‑tenured synthetic sleeper pioneers, agile recycled‑materials specialists, and large rolling‑stock and infrastructure companies moving into distribution and global marketing. Key strategic profiles in the market include:
Worldwide Composite Railroad Tie Market
- Evertrak LLC — a recycled‑plastic + GFRP manufacturer with demonstrated AAR/AHEMA‑level approvals and a track record of large installations targeted at heavy‑haul and high‑decay geographies. Its certified products and recent strategic capital injection support accelerated North American capacity expansion.
- TieTek (EFG TieTek) — an incumbent market leader in recycled‑plastic composite ties with decades of field experience and a strong product portfolio for grade crossing and mainline applications.
- Triton Group / Triton Ties — a materials specialist whose glass‑reinforced polymer ties attracted large‑scale trial attention; a 2026 strategic agreement with a major equipment supplier dramatically expands global marketing and distribution reach.
- Sicut Enterprises, Pioonier and AGICO — regional champions with approvals from national rail authorities and a clear focus on metro and specialty track use cases, often winning specification‑level decisions where timber procurement is being curtailed.
- Established heavy‑infrastructure players (e.g., Sekisui, Vossloh, Lankhorst) and resilient niche producers (Axion, IntegriCo) — these firms anchor the market with manufacturing scale, broad project experience and product families that meet specific high‑speed, turnout and bridge requirements.
Recent industry moves — including strategic investments, mass trial deployments and exclusive marketing agreements — are shifting competitive advantage from purely technical performance to supply‑chain control, warranty depth and the ability to contract for whole‑life services.
Core dynamics shaping procurement and investment decisions
- Raw materials: Composite ties increasingly rely on post‑consumer polyolefins and HDPE reinforced with glass fiber. Securing diversified recycled feedstocks and downstream recyclability is now a procurement priority.
- Standards & certification: Products that meet or exceed AREMA/AAR standards and secure national approvals materially shorten adoption cycles; certification programs and independent laboratory validation are non‑negotiable.
- Sustainability mandates: Creosote bans, circularity targets and CO2 accounting are assigning premiums to fully recyclable composite solutions that reduce deforestation and hazardous chemical use.
- Operational fit: Installation productivity, compatibility with existing tamping and tie‑handling fleets, and expected service life differentials (composite designs targeting multi‑decade service versus timber replacement cycles) determine total cost outcomes.
Strategic recommendations for 2026 decision‑makers
- Recast procurement KPIs: move from unit‑price comparisons to lifecycle TCO, warranty‑weighted NPV and circularity scoring.
- Deploy targeted pilots where upside is highest — high‑decay corridors, transit networks undergoing timber phase‑outs, and specialty structures — to build operational confidence before broad substitution.
- Use strategic partnerships to de‑risk supply and accelerate scale: consider off‑take agreements, minority equity stakes or exclusive distribution pacts with established suppliers that have approvals and field evidence.
- Invest in local capacity or guaranteed supply lines for recycled feedstock to protect against commodity swings and regulatory constraints on cross‑border material flows.
- Insist on independent verification: include third‑party mechanical testing, long‑term monitoring clauses and clearly defined remediation paths in contracts.
- Prepare aftermarket services and spare‑parts strategies — warranty fulfillment, inspection regimes and end‑of‑life recycling pathways should be contractual deliverables.
Principal risks and mitigation levers
- Material price and quality volatility — mitigate through multi‑sourcing and feedstock partnerships.
- Performance surprises under atypical load or climate regimes — manage via staged roll‑outs, expanded instrumentation, and performance‑based payments.
- Regulatory and standards divergence across jurisdictions — reduce exposure with supplier approvals and pre‑emptive testing aligned to target markets.
- Capacity mismatch during rapid adoption — secure contractual capacity or co‑invest in manufacturing to align supply with project pipelines.
How PW Consulting helps execute your 2026 roadmap
For organizations preparing for procurement cycles, pilot programs, or strategic investments in composite railroad ties, PW Consulting offers tailored advisory services: custom scenario modelling using the full 2026–2032 demand projection, supplier due diligence and technical audit, pilot program design and implementation oversight, and transaction support for partnerships and M&A. Our deliverables bundle the quantitative models, procurement templates and field‑trial playbooks that mobilize capital and operations teams quickly and confidently.
This press preview is intended to demonstrate the actionable insight and strategic posture contained in PW Consulting’s full report. Core segmentation tables, material‑level demand breakdowns, regional adoption curves and the interactive financial model are reserved for the comprehensive report package and licensed clients. To access the complete dataset, supplier scorecards and downloadable TCO tools, visit PW Consulting’s report page or contact our strategic infrastructure practice to arrange a briefing tailored to your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Composite Railroad Tie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com