

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automatic Weapons Market Poised for 7.0% CAGR, New Report Shows

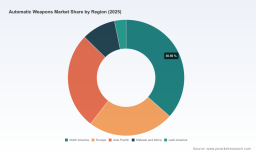
Worldwide Automatic Weapons Market — Strategic Implications for 2026: PW Consulting Report Preview
As defence budgets and battlefield demands evolve, the automatic weapons market is entering a phase of structurally different growth and strategic re-alignment. Our new PW Consulting market study (base year 2025; forecast period 2026–2032) models the addressable market at USD 9,250 Million in 2025 and projects a steady compound annual growth rate (CAGR) of 7.0% through 2032, when modelled revenues reach approximately USD 14,853 Million. This preview highlights the decision-critical takeaways for manufacturers, primes, tier‑1 suppliers, and defence procurement offices preparing plans for 2026 procurement cycles and beyond. For full segment-level tables, tender-by-region forecasts, and vendor scorecards, access the complete report on our website.
Worldwide Automatic Weapons Market
Why this matters for 2026 decision-makers
-
Investment timing: A mid-single-digit to high-single-digit growth runway creates windows for targeted capital expenditure—particularly in modular weapon platforms and squad-level lethality improvements—while also increasing competition for production capacity and specialist components.
Worldwide Automatic Weapons Market -
Portfolio prioritisation: Firms must choose between scaling existing automatic weapons lines or shifting R&D into adjacent subsystems (e.g., suppressors, integrated optics, turreted mounts) where margin pools are expanding faster than base weapons volumes.
Worldwide Automatic Weapons Market -
Regulatory and export risk: Rapidly evolving export controls and multilateral lists are creating asymmetric access to markets; compliance-driven localisation or partnership strategies are becoming decision-making prerequisites.
Market dynamics shaping supplier and buyer strategies
-
Modernisation and capability refresh programs remain the primary demand engine. Initiatives such as next-generation squad weapons and allied fleet/platform upgrades continue to push requirements for increased range, penetration, and integration with sensors and fire-control systems.
-
Raw-material volatility: Input cost dynamics—highlighted by hot-rolled coil steel trading near USD 900 per short ton in mid‑2025—are a tangible margin pressure point for manufacturers. Our modelling shows that small cost shifts materially affect tender competitiveness for high‑volume rifle and receiver lines and underscores the importance of hedging and vertical sourcing.
-
Export-control tightening: Updates to the Wassenaar Arrangement in December 2025 and continuing U.S. ITAR/EAR refinements are increasing licensing friction for dual‑use components (e.g., advanced imaging sensors, ceramic composites). Buyers and sellers must operationalise compliance as a commercial differentiator, not merely a legal obligation.
-
Platform modularity and lifecycle services: The value migration from hardware alone to systems-of-systems—ammo, optics, maintenance, and training—means aftermarket and sustainment offerings are now decisive in procurement awards.
What PW Consulting’s report delivers — practical, executable intelligence
-
Market sizing and outlook: Top‑down and bottom‑up forecasts through 2032 including scenario variants (baseline, constrained supply, accelerated modernization).
-
Procurement pipeline mapping: Consolidated program timelines and likely award windows to inform capacity planning and capture campaigns.
-
Supplier benchmarking: Operational scorecards for major manufacturers (technology, contract wins, IP positions, manufacturability, and export footprints) to support partner selection and M&A due diligence.
-
Regulatory matrix & export-playbook: Actionable pathways to reduce licensing risk, including suggested control-list mapping and recommended compliance investments per export jurisdiction.
-
Supply‑chain resilience toolkit: Stress-tested scenarios that quantify margin and delivery risk under raw-material shocks, semiconductor/component shortages, and trade restrictions—with mitigation playbooks.
-
Technology and product roadmaps: Comparative analysis of ammunition, barrel, suppression, and integration trends with guidance on R&D prioritisation and differentiation vectors.
-
Commercial strategies: Tender pricing models, offset strategies, and aftermarket-service monetisation playbooks that translate forecasts into 12–36 month sales and margin plans.
Competitive landscape: what the market is signaling about vendor strategies
The automatic weapons market is moderately consolidated: leading vendors capture a significant share of industry revenues, with the top three firms holding a distinct leadership position and the top five capturing just over half of the market. This configuration yields both predictable sourcing channels for large prime contractors and meaningful opportunities for specialised entrants that can deliver differentiated capabilities.
-
FN Herstal (FN America) — Deep product heritage across SCAR, Minimi/M249 and medium-machine-gun families positions FN as a go-to for modular small arms and sustained fire systems. FN’s January 2026 launch of a next‑generation SCAR family (modularity and suppressor‑ready options) underscores its strategy to defend platform relevance through upgradeable kits and accessory ecosystems.
-
Heckler & Koch — A premium engineering and special-forces pedigree with platforms like the HK416/417 and MP7. H&K’s strength lies in technology leadership and specialised procurement channels; expect continued focus on high-value niches and marked presence in European and coalition procurement.
-
SIG Sauer — Strategic momentum from its Next Generation Squad Weapon successes (Type Classification milestones for XM7/XM250 in 2025) translates into near-term production scale-up and downstream ammunition and logistics opportunities. SIG is positioning to convert program access into longer-term platform-authority.
-
Rheinmetall, General Dynamics, Northrop Grumman, BAE Systems — These primes command systems and integration capabilities (vehicle, naval, and airborne mounts) and are increasingly internalising modular weapon subsystems to deliver platform‑level solutions rather than stand‑alone guns.
-
Colt, IWI, Kalashnikov, Beretta, Denel, ST Engineering — Regional champions and legacy makers that remain highly relevant in national procurement, export markets, and low‑to‑mid value segments; their strategic playbooks prioritise local partnerships, licensing, and niche product strengths (e.g., light machine guns, PDWs, anti‑materiel rifles).
Strategic implications and recommended actions for 2026
-
Prioritise platform modularity and upgrade paths. Design product families that accommodate accessory ecosystems, calibre conversions, and software-enabled fire-control inserts to extend contract lifecycles and aftermarket revenue.
-
Operationalise export-control compliance as a commercial function. Invest now in licensing infrastructure, local manufacturing partnerships, and technology-transfer playbooks to reduce bid risk on multinational tenders.
-
Hedge raw-material exposure. Establish strategic metal purchase agreements, near‑shoring options, and second‑tier suppliers for critical receiver and barrel inputs; quantify the margin impact of +/-10% HRC swings for core product lines.
-
Build sustainment and training bundles. Compete on total cost of ownership—warranties, spares provisioning, training simulators, and depot support often decide procurements when base weapon specifications are similar.
-
Pursue focused M&A and partnerships. Targets should be selected for capability gaps (suppression, optics, fire-control electronics) or for market access (local manufacturing, national champions in protected markets).
-
Scenario-plan for supply constriction. Maintain manufacturing flex (convertible lines, dual-sourcing) and tender staffing capacity to exploit near-term procurement upticks predicted in our baseline and upside scenarios.
Final note — where this preview stops and the full intelligence begins
This briefing is intentionally selective: it summarises the high‑value signals decision-makers need for 2026 planning while withholding granular tables and segment-level allocations that are included in the full PW Consulting Worldwide Automatic Weapons Market report. The complete study provides the detailed regional and application splits, vendor scorecards, contract-timing heatmaps, and price‑sensitivity matrices required to execute bidding, investment, and M&A decisions with confidence.
To download the full report, access the interactive datasets, or request a tailored briefing for your executive team, please visit the PW Consulting market intelligence portal. Our analysts are available to walk through scenario outcomes and to tailor the supply‑chain stress tests and go‑to‑market playbooks to your organisation’s needs.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Weapons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com