

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Subsea Flowlines Market to Rise from USD 4.8 Billion in 2025 to USD 6.98 Billion by 2032 at 5.5% CAGR — Carbon Steel Leads, Latin America Tops Region

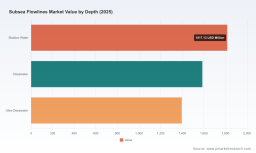
Worldwide Subsea Flowlines Market 2026: Strategic Briefing for Decision‑Makers
PW Consulting’s latest market study—Worldwide Subsea Flowlines Market (base year 2025, forecast 2026–2032)—distills the strategic intelligence energy and marine executives need to make decisive moves in 2026. Combining a granular view of supplier capabilities, technology adoption, and regulatory shifts with an investment‑grade market model, this briefing explains why flowlines are re‑emerging as a critical lever for offshore value creation, and how corporates should reconfigure sourcing, engineering and M&A playbooks to capture next‑wave opportunities.
Worldwide Subsea Flowlines Market
Market snapshot: direction and scale (what senior leaders must internalize)
After a multi‑year recovery, the global subsea flowlines market reached roughly USD 4.8 billion in 2025. Our base‑case forecast anticipates a steady expansion through the next business cycle, with the market approaching the low‑single‑digit‑billion range by the end of the 2026–2032 forecast window—reflecting a compound annual growth rate of approximately 5.5% across the outlook period. This trajectory encapsulates new deepwater project awards, an uptick in tie‑backs enabling satellite field development, and incremental spend on flow assurance technologies that extend tie‑back economics.
Worldwide Subsea Flowlines Market
Market structure remains moderately consolidated: the top three suppliers account for more than half of global share today, while the top five control roughly three quarters of activity. For market participants this means concentrated pricing power among a handful of integrated EPCI and equipment providers—yet material opportunity exists for specialists that can demonstrate cost‑to‑value advantage on thermal management, connection systems, and modular SURF delivery.
Worldwide Subsea Flowlines Market
Why this matters for 2026 decision cycles
-
CapEx allocation and project selection: Operators evaluating sanction decisions in 2026 must price in longer tie‑backs and higher thermal management spend to protect barrel recovery rates. Projects that lean on existing host infrastructure or prioritize simplified SURF scopes are forecast to reach first production more quickly and at lower risk.
-
Supplier strategy and contracting: Given the market concentration dynamics, negotiating leverage will favor early engagement and integrated contracting where lead contractors can offer bundled engineering, manufacturing, and installation packages. Procurement teams should prioritize frame agreements and long‑lead procurement commitments for flexible pipes and coated line pipe to avoid schedule premium erosion.
-
Technology roadmaps: Thermal management—electrically heat‑traced flowlines (EHTF), pipe‑in‑pipe (PiP), and advanced clad solutions—has shifted from niche to mainstream for deep tie‑backs. Companies that adopt modular heating or pre‑qualified PiP designs can materially extend tie‑back distances and lower life‑of‑field OPEX risk.
-
M&A and partnership plays: The top‑tier contractor community continues to pursue strategic alliances and bolt‑on acquisitions to secure SURF margins and intellectual property. Buyers should look for targets that close capability gaps in flow assurance, subsea connectors, or local manufacturing footprints that de‑risk project delivery in contested basins.
-
Regulatory and standards compliance: Updates to subsea production system standards (notably the EN ISO family refreshes) will influence design margins and qualification programmes in 2026; early compliance planning prevents late‑cycle rework and preserves schedule integrity.
What the full PW Consulting report delivers (practical, transaction‑ready intelligence)
Our study is structured to be directly actionable for boardrooms, commercial teams, and engineering leads. It combines an investible market model with a pragmatic toolbox:
-
Market model and scenario runs: Top‑down and bottom‑up revenue forecasts across 2026–2032, plus alternative scenarios that stress oil price sensitivities, regional sanctioning timelines and technology adoption curves.
-
Project pipeline synthesis: An anonymized, tiered view of defined and probable SURF projects that drives near‑term demand visibility without exposing raw client‑sensitive figures in this summary.
-
Supplier scoring and procurement playbook: A qualitative and quantitative assessment of contractors, flexible pipe manufacturers, line‑pipe mills, and specialized connector vendors—highlighting delivery risk, cost competitiveness, and capacity constraints. Our procurement playbook provides contract templates, long‑lead mitigation strategies, and KPI frameworks for EPC/EPCI engagements.
-
Technology decision matrices: Comparative decision frameworks for selecting EHTF vs. PiP vs. CRA‑clad solutions by reservoir temperature, tie‑back length and H2S/CO2 content, coupled with sensitivity outputs on lifecycle cost and emissions intensity.
-
Regulatory impact analysis: Practical checklists to ensure designs and operating procedures align with the 2025 standards update, and to anticipate qualification timelines for new materials and connection technologies.
-
Commercial intelligence annexes: Contract award tracking, capability maps, and a confidential supplier negotiation scorecard available for premium subscribers.
Competitive dynamics: who matters and why
The subsea flowlines value chain blends large integrated EPCI contractors with specialized equipment and materials suppliers. Leading integrated suppliers—characterised by global project delivery capabilities and end‑to‑end SURF offerings—continue to win the marquee, complex deepwater programmes, while niche vendors capture higher margin pockets in connectors, flexible pipe, and thermal systems.
Key participants profiled in the report include established EPCI houses with global SURF capabilities; flexible pipe and subsea systems specialists supplying mid‑to‑long length tie‑back solutions; and materials manufacturers producing premium line pipe, clad options and riser products. Our competitive analysis highlights how firms are differentiating along three vectors: execution scale (project delivery footprint and vessel access), technical differentiation (proprietary connectors, PiP expertise, integrated flow assurance), and commercial model (risk‑versus‑reward sharing, guaranteed performance clauses).
Notable strategic moves tracked in our research: several major contractors have recently secured (and continue to bid for) large SURF packages in deepwater basins, reinforcing the relevance of integrated delivery. Suppliers of flexible pipes have expanded capacity and won long‑length supply contracts, underscoring the ongoing demand for flexible solutions in pre‑salt and comparable plays. Technology consortia and joint industry projects are accelerating qualification cycles for next‑generation heating solutions—shifting the bar for what is considered “proven” technology within procurement evaluations.
Technology, materials and standards shaping the next wave
Three technical themes will determine competitive advantage through 2026 and beyond:
-
Thermal management and flow assurance: Electrically heat‑traced flowlines, insulated PiP constructions and improved CRA cladding approaches are enabling longer, more reliable tie‑backs and reducing the breakeven distance for marginal fields.
-
Connection systems and modularization: Metal‑to‑metal sealing technologies, pressure‑containing clamp systems and vertical connectors that simplify subsea tie‑ins reduce diver/ROV time and lower installation uncertainty—translating to tangible schedule risk reduction.
-
Standardization and qualification: The 2025 updates to subsea production standards have raised qualification expectations for novel materials and designs. Early design alignment with these standards is a practical lever to shorten permitting and acceptance cycles.
Five priority actions for executives in 2026
-
Re‑price opportunities with technology premiums: Update sanction cost models to reflect thermal management premiums and long‑lead procurement risk. Projects that omit robust flow assurance are at higher schedule and economic risk.
-
Lock in strategic supply: Enter conditional long‑lead agreements for flexible pipe and premium line pipe capacity where supplier concentration creates potential bottlenecks.
-
De‑risk delivery through partnerships: Pursue alliances with specialist vendors for connectors and PiP delivery to gain margin stability and execution expertise without full vertical integration.
-
Embed standards‑led design reviews: Integrate EN ISO standards compliance checkpoints into FEED and procurement milestones to avoid late‑stage redesign and qualification costs.
-
Prepare M&A playbooks for capability gaps: Prioritize targets that deliver demonstrable flow assurance IP, local fabrication capacity in high‑growth basins, or complementary SURF installation assets.
Where this report fits in your 2026 decision cycle
For operators, the study functions as a risk‑adjusted project screening tool and a procurement readiness scorecard. For contractors and suppliers, it is a commercial playbook that identifies capacity constraints, tech adoption timing, and the most attractive pockets for margin expansion. For investors and asset owners, it provides a data‑backed view of where value will accrue in the subsea value chain over the coming years and where to allocate capital to hedge against execution and technology risk.
PW Consulting’s Worldwide Subsea Flowlines Market report is intentionally crafted as a decision‑grade product: it exposes the critical levers and directional market sizing while reserving contract‑level, basin‑specific and supplier‑score detail for the full report and accompanying data workbook. This “teaser‑plus‑access” approach preserves client confidentiality and ensures our analysis remains commercially actionable.
Next steps
Executives preparing 2026 budgets and strategic plans should request the full report and the interactive data workbook to: run bespoke scenario analyses against their portfolio, access the supplier negotiation scorecard, and review the confidential project pipeline that underpins our demand forecast. PW Consulting’s advisory team is available to translate the report’s findings into bespoke CAPEX prioritization, procurement negotiation support, and M&A diligence packages.
Contact PW Consulting to obtain the full Worldwide Subsea Flowlines Market report and unlock the detailed, project‑level intelligence required to turn 2026 into a year of disciplined growth and competitive advantage in the subsea domain.
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Flowlines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com