

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 4.85% CAGR for Worldwide Caustic Calcined Magnesia Market; Market to Reach USD 1,170.9 Million by 2032

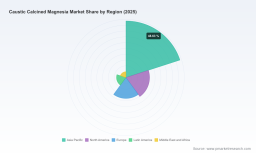
Worldwide Caustic Calcined Magnesia Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting’s newest market study on the Worldwide Caustic Calcined Magnesia (CCM) market synthesizes five years of historical observation and a seven‑year forecast horizon to deliver a pragmatic, decision‑grade picture for 2026 and beyond. The market has expanded from approximately USD 665 million in 2020 to roughly USD 840 million in our base year (2025), and our model projects steady expansion through 2032, reaching an estimated USD 1,171 million by the end of the forecast window. That trajectory corresponds to a mid‑single‑digit compound annual growth rate (CAGR) of about 4.85% for the 2026–2032 period — a pace that supports both portfolio optimization and targeted growth investments but requires clear strategic tradeoffs in sourcing, product positioning, and regulatory compliance.
Worldwide Caustic Calcined Magnesia Market
Why this report matters for 2026 decisions
Managers making capital allocation, sourcing, and M&A decisions in 2026 face an environment where volume growth is solid but margin pressure and regulatory complexity are rising. The combination of persistent raw‑material tightness, shifting trade policy, and stronger impurity/regulatory regimes means that commercial outcomes will be determined as much by supply‑chain and regulatory strategy as by traditional sales channels. Our report is structured to translate those macro dynamics into executable options: where to densify capacity, which grades merit premium positioning, how to structure contracts to defend margins, and where value pools will emerge under alternative scenarios.
Worldwide Caustic Calcined Magnesia Market
What the PW Consulting report delivers — practical, actionable elements
- Integrated market model: an editable, bottom‑up model covering 2020–2032 that ties demand by end‑use and grade to price and input‑cost scenarios, enabling rapid sensitivity testing for raw material, freight, and tariff shocks.
- Commercial playbooks: go‑to‑market frameworks for premium high‑reactivity and low‑iron grades, certification roadmaps (e.g., potable water standards), and contract templates that balance volume commitments with pass‑through cost protection.
- Supply‑chain resilience toolkit: supplier scorecards, dual‑sourcing decision matrices, and an inventory‑optimization module that quantifies the tradeoffs between working capital and disruption risk.
- Regulatory and compliance tracker: a living register of regional impurity limits, classification status, and certification paths, with recommended compliance timelines for EU, US, and major export markets.
- Strategic M&A and capex roadmaps: prioritized lists of asset archetypes (e.g., specialty low‑iron plants, regional grinding/logistics hubs) with IRR sensitivity bands under conservative and aggressive demand scenarios.
- Competitive heatmaps and supplier risk ratings: a consolidated view of global capacity footprints, concentration dynamics, and reputational or operational risk factors that matter to buyers and investors.
Competitive landscape — concentration, archetypes and recent moves
The CCM market exhibits a measured level of concentration: the top three suppliers account for a meaningful but not dominant share of market volumes, while the top five collectively represent a majority share — a structure that creates both bargaining power for incumbents and room for well‑targeted entrants or consolidators. The competitive set spans large integrated raw‑material miners and global refractory specialists, regionally focused commodity producers, and smaller firms specialized in high‑purity or certified grades for water and environmental use.
Worldwide Caustic Calcined Magnesia Market
- Integrated western producers with downstream brands are leveraging certification and customer relationships to defend higher margin channels. Recent capacity expansion announcements signal a tactical response to water‑treatment demand and an attempt to secure share in regulated markets.
- European and South American producers are positioning technology and logistics as differentiators, emphasizing product formulations tailored for refractories, flue‑gas desulfurization and specialty chemical uses.
- Large Chinese manufacturers continue to supply a global commodity corridor, but trade measures and freight volatility are reshaping where and how those volumes can compete with local or regional supply.
- Specialty suppliers — those focused on ultra‑low impurity grades and certified potable‑water products — are capturing premium niches; recent certification wins demonstrate the tangible commercial value of targeted quality investments.
Recent corporate developments exemplify these dynamics: a North American producer announced a material capacity expansion to capture water‑treatment growth; a Mediterranean exporter launched a low‑iron premium grade for advanced wastewater applications; a specialty supplier secured potable‑water certification across a broader portfolio; and a refractory group showcased new CCM formulations at a major industry event. Each move underscores the dual pressures of scale and differentiation that characterize the market in 2026.
Market dynamics and near‑term risk drivers
The operating environment for CCM is being reshaped by several interlocking forces that should inform any 2026 strategic plan:
- Raw‑material price and availability: Recent supply constraints in key magnesite producing regions have pushed input prices higher and introduced greater volatility into feedstock procurement. Procurement teams must plan around both price and quality variability.
- Regulatory tightening: New impurity thresholds and certification expectations in major markets elevate the cost of non‑compliance and can create technical barriers to entry — particularly for commodity suppliers selling into regulated chemical or potable‑water chains.
- Trade policy and tariffs: Recent import restrictions and tariff actions have re‑shaped competitive economics for cross‑border flows. Sourcing strategies must be recalibrated to balance landed cost with duty exposure and reputational risk.
- Logistics and route fragility: Disruptions to key maritime corridors have increased bulk freight cost and transit uncertainty, amplifying the value of regional inventory hubs and modal diversification.
- Occupational and product safety expectations: While CCM is not classified as a hazardous substance under global harmonized criteria, dust control and occupational exposure management remain compliance necessities that influence plant design and operating cost.
Strategic playbook for 2026 — recommendations for executives
- Prioritize dual levers: protect existing margins through short‑term commercial levers (indexation clauses, strategic stockpiles) while investing selectively in higher‑margin specialty grades that benefit from certification and process know‑how.
- Localize strategic nodes: evaluate establishing or partnering on regional grinding or finishing facilities in high‑demand markets to mitigate freight volatility and tariff exposure.
- Invest in quality and certification early: securing potable‑water and low‑impurity credentials is a de‑risking investment that can unlock premium channels and reduce exposure to tightening regulatory regimes.
- Adopt a scenario‑based capital plan: use the report’s sensitivity model to test capex under at least three cases (baseline growth, raw‑material shock, trade‑policy shock), and stage investments with trigger points tied to price or utilization thresholds.
- Treat M&A as capability acquisition: prioritize bolt‑on assets that add specialty grades, regional logistics, or certification competence rather than simply incremental tonnage.
- Sustainability and customer transparency: embed traceability of feedstock and impurity data into commercial documentation — many end users increasingly require chain‑of‑custody assurances as part of procurement decisions.
KPIs and governance to monitor
We recommend a tight set of KPIs for 2026 execution: utilization and on‑time delivery for regional hubs, margin per grade, inventory days (segmented by strategic versus cycle stock), supplier risk scores, certification time‑to‑market, and contract pass‑through effectiveness. A cross‑functional governance rhythm — combining commercial, procurement, quality and regulatory leads — is essential to convert market insight into performance.
Why PW Consulting’s analysis is uniquely actionable
Our study combines an editable market model, supplier and product scorecards, regulatory trackers and commercial playbooks into a single package designed for rapid decision use. We deliberately present deep methodological transparency so teams can re‑run scenarios with internal assumptions and stress‑test investment cases. At the same time, we have withheld granular split‑level intelligence in this summary — the full dataset, segmental demand curves, and company‑level volume mosaics are available in the complete report package, enabling clients to convert strategic direction into an executable plan.
Next steps
For teams preparing 2026 capital, sourcing or M&A playbooks, the full PW Consulting report delivers the models, templates and benchmark data required to move from strategic intent to operational execution. Access to the underlying data and the sensitivity models materially shortens the time to a defensible investment thesis. Contact PW Consulting to obtain the complete report and the interactive model that powers our analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Caustic Calcined Magnesia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com