

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Smart Ticketing Market to Expand at a 12.35% CAGR, Accelerating the Shift to Mobile and Contactless Fare Systems

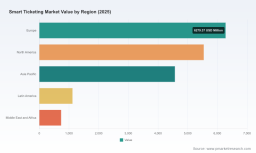
Worldwide Smart Ticketing Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest Worldwide Smart Ticketing Market report (base year 2025, forecast period 2026–2032) distills a complex and fast-moving ecosystem into the practical intelligence that transport operators, ticketing vendors, payments teams, and infrastructure investors need to act in 2026. The market has more than doubled in scale since 2020, rising from approximately USD 10.45 billion in 2020 to USD 18.25 billion in 2025, and is projected to expand at a compound annual growth rate (CAGR) of 12.35% across our forecast window, reaching just over USD 41.2 billion by 2032. This release is a strategic “teaser”: it demonstrates the analytical rigor behind our findings while preserving proprietary segment-level details that are accessible in the full report and accompanying client tools.
Worldwide Smart Ticketing Market
Why this report matters for 2026 strategy
Smart ticketing is no longer an isolated technology project; it sits at the intersection of payments, identity, mobility-as-a-service (MaaS), and public policy. For executives planning capital allocations, procurement roadmaps, or new product launches in 2026, timing and compliance will matter as much as technical capability. Our report converts market momentum into decision-ready guidance by combining market sizing and scenario-based forecasts with operational playbooks: vendor scorecards, procurement templates, deployment cost models, regulatory impact assessments, and ROI scenarios tailored to different operator profiles.
Worldwide Smart Ticketing Market
Two high-level structural characteristics shape the competitive arena. First, market concentration is meaningful but not monopolistic — the top-three players account for roughly 42.5% of market share, while the top-five approach about 58.2% — creating both scale advantages and opportunities for differentiated entrants. Second, the shift from closed, card-centric systems to hybrid architectures that embrace account-based ticketing (ABT), mobile wallets, EMV, and open standards is accelerating. These forces are reflected in the vendor behaviors and product launches tracked in our competitive analysis.
Worldwide Smart Ticketing Market
What’s inside: practical, deployable deliverables
- Robust market sizing and forecasting: a reproducible methodology tied to real deployments and cost drivers, showing annual market trajectories from the historical period (2020–2025) into the 2026–2032 forecast horizon.
- Scenario modelling: three strategic pathways (consolidation & scale, open-standards-driven migration, and multi-modal integration) with sensitivity analyses for capex, farebox recovery, and customer adoption.
- TCO and procurement tools: total cost of ownership templates that incorporate hardware refresh cycles, software licensing, hosting, and operations — including realistic reader deployment unit costs that urban projects should budget for.
- Regulatory & standards playbook: a checklist and roadmap to achieve compliance with critical mandates—such as recent EU open-standards requirements—and payment-security frameworks like PCI DSS v4.0.
- Vendor assessment matrix: qualitative and quantitative criteria (technology stack, deployment velocity, client references, interoperability, and data ownership clauses) that support “go/no-go” procurement decisions.
- Implementation playbooks: phased migration strategies for moving from legacy card-based systems to hybrid architectures that support mobile wallets, EMV, and account-based ticketing without disrupting revenue collection.
- Operator-ready KPIs and pilot templates: adoption, fraud, latency, and cost-per-trip metrics plus templates for structuring vendor pilots and public-private partnerships.
Competitive landscape — core vendors and strategic implications
-
Masabi (London, UK) — Masabi’s Justride platform has become a reference for mobile-first ticketing and account-based solutions. Its October 2025 integration enabling Apple Wallet express transit mode is an indication of two trends: (1) deepening collaboration between platform vendors and mobile ecosystems, and (2) a race to deliver low-friction tap-to-ride experiences. For operators, Masabi represents a fast path to mobile adoption but also a reminder to negotiate clear data portability and integration terms.
-
Moovit (Tel Aviv, Israel) — Moovit’s expansion of account-based ticketing across European cities demonstrates how journey-planning apps and MaaS providers are vertically integrating ticketing. For cities focused on multimodal integration, Moovit’s combined trip-planning and payment capabilities reduce friction, but operators should evaluate dependencies on third-party customer interfaces and revenue-settlement mechanics.
-
HID Global (Austin, USA) — HID remains a strong incumbent in credential technologies and secure element provisioning (Seos). Their strengths are in large-scale credential issuance and operator partnerships; procurement teams should treat HID as a hardware and credentialing anchor while insisting on open APIs for future mobility integrations.
-
NXP Semiconductors (Eindhoven, Netherlands) — As a supplier of contactless ICs (MIFARE family), NXP sits at the chipset layer that underpins many card deployments globally. That technical moat creates long product cycles and high interoperability value, especially for operators that must maintain backward compatibility; however, it also implies supply-chain risk management becomes a strategic procurement imperative.
-
Thales Group (Paris, France) — Thales’ recent deployments of contactless EMV systems highlight its capability to execute large, bank-card-friendly rollouts. For networks exploring bank-card acceptance alongside closed media, Thales’ experience is a valuable capability — but organizations must model interchange, settlement, and certification impacts explicitly.
-
Cubic Transportation Systems (San Diego, USA) — With Umo Mobility 2.0 and enhanced QR/NFC multimodal capabilities, Cubic positions itself as a platform integrator for multi-operator environments. The commercial question for transit authorities is whether to adopt an integrator that reduces fragmentation at the expense of potential lock-in.
-
Scheidt & Bachmann (Ratingen, Germany) — Known for fare-collection hardware and integrated systems, Scheidt & Bachmann offers robust vendor-managed solutions for bus and rail operators. Their strength is in end-to-end delivery for line-haul and curbside operations, with a focus on reliability and long-term support.
-
Vix Technology (Adelaide, Australia) — Vix’s deployments in major networks underscore its ability to operate and scale fare collection back-ends. For operators that prioritize operational continuity and proven migration experience, Vix is a practical choice, particularly in markets moving toward hybrid models.
Regulatory, standards and cost dynamics to factor into 2026 plans
Three regulatory and standards dynamics will shape near-term choices. First, recent EU mandates on open standards for public transport ticketing create both obligations and opportunities for cross-border interoperation; systems that cannot demonstrate conformity risk exclusion from funded deployments. Second, payment-security requirements (PCI DSS v4.0) now apply more broadly to systems that touch cardholder data, and operators must embed compliance into procurement specifications and cloud architectures. Third, legacy contactless cards governed by ISO/IEC 14443 remain dominant in many networks (approximately 80% penetration in transit ticketing globally), implying that migration strategies must preserve backward compatibility.
Operationally, agencies should budget for infrastructure refreshes: urban NFC reader installation costs typically range between USD 150–300 per unit depending on volume and integration complexity. These unit economics materially affect rollout timing and capital requests; our TCO models translate per-unit costs into multi-year cashflow impacts for different deployment scenarios.
Top-line recommendations for executive teams (2026 planning cycle)
- Prioritize interoperability and data portability clauses in all RFPs. Compliance with open standards is now a gating factor for access to cross-border and pooled funding.
- Run at least one live pilot of account-based ticketing (ABT) or mobile-wallet express mode in 2026, focused on a high-frequency corridor where failure modes can be tightly controlled.
- Embed PCI DSS v4.0 and secure credential lifecycle management into vendor contracts; treat security as a service requirement, not an optional add-on.
- Model hybrid architectures that support the continued use of contactless cards (ISO/IEC 14443) while enabling mobile wallets and EMV; phase migration to reduce revenue risk.
- Use our TCO templates to stress-test reader deployment unit costs and staging plans; front-load interoperability and integration costs in budget cycles.
- Negotiate exit and data-extraction clauses with platform providers to preserve the option to switch integrators as technology and partnerships evolve.
- Favor vendors with both deployment-scale references and modular APIs — scale alone is insufficient if the platform cannot interoperate with local fare rules, MaaS providers, and payment rails.
How PW Consulting helps
This briefing summarizes themes and strategic imperatives; it is intentionally selective. The full Worldwide Smart Ticketing Market report includes granular segment-level forecasts, regional breakdowns, detailed vendor profiles with deployment case studies, vendor financial benchmarking, and client-ready scenario models that populate your capital planning and procurement processes. For organizations that require bespoke analysis — for example, ROI modeling for a regional rollout, vendor selection support, or a compliance gap assessment ahead of a 2026 procurement — PW Consulting offers tailored advisory engagements that operationalize the report’s insights.
To access the complete datasets, vendor scorecards, and customizable models referenced here, please consult the official report page or contact PW Consulting’s mobility practice for a briefing and demo. Our objective is to turn market insight into operational certainty, helping you choose the right technology path at the right time.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Ticketing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com