

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Lennox‑Gastaut Syndrome Drug Market Set to Grow at 4.52% CAGR Through 2032, Led by Cannabinoids and Hospital Pharmacies

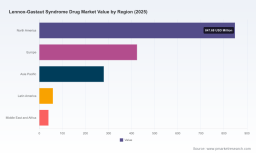
Worldwide Lennox-Gastaut Syndrome Drug Market: Strategic Outlook for 2026 Decision‑Making
PW Consulting’s new market brief on the Worldwide Lennox‑Gastaut Syndrome (LGS) drug market consolidates actionable intelligence for executives, strategy teams, and investors confronting a clinical area that remains therapeutically complex, commercially dynamic, and increasingly evidence‑driven. With a 2025 base year and a forecast horizon to 2032, the study synthesizes historical trends (2020–2025), regulatory and reimbursement shifts, product life‑cycle events, and competitive dynamics to illuminate where value will accrue and what choices matter most in 2026.
Worldwide Lennox-Gastaut Syndrome Drug Market
Macro snapshot: steady growth under clinical and commercial pressure
The global LGS drug market has expanded from roughly USD 1.25 billion in 2020 to about USD 1.65 billion in 2025, and our baseline projection anticipates continued expansion to the low‑to‑mid USD 2 billion range by the end of the 2026–2032 forecast window. That trajectory reflects a compound annual growth rate of approximately 4.52% over the forecast period. This growth belies a more nuanced set of forces at play: novel branded anti‑seizure medications (ASMs) commanding premium pricing, persistent clinical need for better seizure control and tolerability, and intensifying generic competition that is compressing margins in legacy categories.
Worldwide Lennox-Gastaut Syndrome Drug Market
Why this report matters for 2026 strategic planning
- Decision relevance: We translate market evolution into concrete choices—portfolio prioritization, pricing and contracting strategy, R&D prioritization, and M&A screening—so leadership teams can align 2026 capital and commercial plans with realistic near‑term outcomes.
- Timing sensitivity: Several regulatory, clinical and payer inflection points are clustered around 2025–2027 (generic approvals, real‑world evidence disclosures, and label‑enabling analyses). The report highlights how these events alter revenue runways and the competitive calculus for both incumbents and entrants.
- Operational implications: From supply‑chain risk (specialized active ingredients) to field force reprioritization and payer dossier updates, we identify practical operational pivots that protect revenue while supporting long‑term growth.
Report coverage: practical analytics without the noise
The full PW Consulting dossier combines quantitative market modeling with qualitative, practitioner‑level guidance. Key deliverables include:
Worldwide Lennox-Gastaut Syndrome Drug Market
- Granular market sizing anchored to a 2025 base year and projected through 2032, including sensitivity scenarios reflecting varying uptake rates for branded innovations and differing generic erosion patterns.
- Commercial playbooks for branded and generic manufacturers: market access positioning, value dossier frameworks, and tactical contracting recommendations for payers and hospitals.
- Competitive landscaping that matches asset profiles, regulatory exclusivity timelines, and portfolio fit—helping identify near‑term acquisition targets and licensing opportunities.
- Clinical and regulatory trackers that map approval histories, boxed‑warning constraints, and scheduled evidence readouts critical to label expansion or market defense.
- Forward‑looking risk matrices covering raw material and manufacturing bottlenecks, supply continuity for plant‑derived compounds, and the impact of scheduling/regulatory changes on distribution.
Competitive dynamics: incumbents, challengers and what to watch
The LGS drug space is shaped by a mix of established epilepsy specialists and diversified pharmaceutical players. Leading commercial narratives include:
- Innovator brands with disease‑specific approvals are driving value despite access headwinds. High‑cost, high‑value products continue to shift the standard‑of‑care debate toward outcomes and budget impact evidence.
- Generics and authorized generics are materially altering the economics of classic ASMs, changing prescribing behavior and payer step‑therapy construction. This dynamic increases the importance of lifecycle management for reference brands and creates pricing pressure upstream in distribution channels.
- Smaller specialty firms and licensing deals are concentrating on formulation innovation (for example, alternative delivery formats) and label differentiation to avoid head‑to‑head pricing wars.
Profiles of companies featured in our landscape include manufacturers of cannabidiol and fenfluramine, originators of clobazam and lamotrigine, and firms retaining rights to distinctive formulations. Each profile in the full report pairs commercial metrics with strategic options—defend, harvest, divest, or double down—based on likely 2026 market scenarios.
Recent industry developments with tactical implications
- Generic approvals in early 2026 have widened low‑cost alternatives for certain legacy ASMs, changing payer incentives and physician prescribing patterns. Manufacturers of reference products must now weigh intensified formulary negotiations, rebate strategies, and potential authorized generic launches.
- Real‑world evidence presented at 2026 conferences has illuminated persistence and discontinuation drivers for newer agents, highlighting the need for targeted patient support programs and adherence interventions that sustain outcomes and justify premium pricing.
- Analyses mining genetic forms of developmental and epileptic encephalopathies inside trial datasets are reshaping how clinicians view treatment heterogeneity—presenting opportunities to pursue label expansion or targeted reimbursement pathways based on biomarker‑driven subpopulations.
Regulatory and reimbursement dynamics that will shape 2026 plays
Regulatory clarity on approved adjunctive therapies for LGS provides both a foundation and constraints for commercial strategy. Notably, some older ASMs are now widely available as generics, while newer agents carry substantially higher list prices. The reimbursement landscape is therefore bifurcated: payers are incentivized to control costs through step edits and prior authorization for premium branded therapies, but clinicians continue to press for access to agents that deliver meaningful seizure reduction in refractory patients.
Separately, safety caveats for certain third‑line options (boxed warnings and monitoring requirements) continue to influence formulary placement and clinical sequencing. Supply considerations are also material for plant‑derived compounds that require controlled cultivation or complex extraction—manufacturers should preemptively secure upstream raw‑material sourcing or plan for contract manufacturing redundancy.
Strategic implications and recommended actions for 2026
- Reassess portfolio prioritization using scenario‑based financial models. For incumbents with reference brands facing generic competition, prioritize programs that extend differentiation—formulation improvements, delivery systems, or biomarker‑linked label expansions.
- Invest in targeted real‑world evidence generation. Payers increasingly demand longitudinal outcomes and economic impact data. A focused RWE program tied to payer communication plans can preserve net price and access for high‑value assets.
- Design payer‑centric contracting pilots. Value‑based and outcomes‑linked agreements are now feasible for selected LGS therapies; pilot programs in integrated delivery networks or specialty pharmacy channels can demonstrate shared risk models without full scale rollouts.
- De‑risk supply chains for specialized inputs. For plant‑derived or highly purified compounds, secure multi‑sourced supply lines and consider vertical integration options where margins and strategic control justify capital deployment.
- Targeted M&A and licensing: seek bolt‑on assets that either shore up specialty portfolios or provide access to differentiated delivery formats and patient support capabilities. Early engagement with smaller specialty firms often yields favorable terms in auctions.
- Prepare a generics defense playbook. Options include authorized generics, value‑added formulations, and intensified provider education on comparative effectiveness to retain clinical preference where clinically justified.
What the full PW Consulting report delivers (and why you should download it)
The public summary you are reading intentionally surfaces strategic themes and high‑level metrics to orient 2026 planning. The full worldwide LGS drug market report expands on these insights with proprietary demand modeling, scenario‑based revenue waterfalls, country‑level payer frameworks, and a prioritized tracker of upcoming patent expiries and regulatory events. Importantly, it contains the detailed segmentation, regional and channel splits, and competitive market shares that corporates rely on to finalize budgets, commercial rollouts, and M&A diligence—data we deliberately reserve for the full study to preserve its commercial utility for subscribers.
Concluding view: execute with evidence and strategic flexibility
By 2026, the LGS market will be governed by a tension between the clinical imperative to adopt higher‑value novel therapies and commercial pressures to manage costs via generics and payer controls. Companies that combine disciplined evidence generation, payer‑focused contracting, and operational foresight will secure disproportionate returns. PW Consulting’s report equips leaders with the analytical backbone and tactical playbooks necessary to navigate this landscape—delivering both the “why” and the “how” for 2026 decisions.
To access the full dataset, regional and segment breakouts, and executable templates for market entry and defense, visit the PW Consulting report page. Our analysts are available for tailored briefings to translate these insights into a 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Lennox-Gastaut Syndrome Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com