

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Luxury Car Coachbuilding Market Set to Expand at a 9.15% CAGR Through 2032

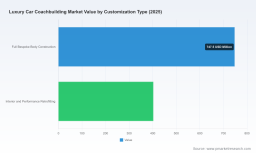
Worldwide Luxury Car Coachbuilding Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting today publishes an executive briefing that distils the strategic implications of our full Worldwide Luxury Car Coachbuilding Market report (base year 2025). The designer‑to‑collector market is entering a new phase of growth and structural renewal: after five years of steady expansion, the market reached roughly USD 1,150 million in 2025 and is projected to grow at a 9.15% CAGR through 2032, approaching the low‑billions by the end of the forecast horizon. This briefing highlights the decision levers senior executives, private equity investors, OEM strategy teams and supply‑chain leaders should prioritize in 2026 — and why the full report is essential to operationalize those choices.
Worldwide Luxury Car Coachbuilding Market
Why 2026 is a Pivotal Year
-
Electrification and experiential luxury are converging. High‑net‑worth clients now expect coachbuilt cars to reflect electrified propulsion, sustainability credentials and multi‑year bespoke ownership journeys. Recent program launches from legacy marques demonstrate this realignment.
Worldwide Luxury Car Coachbuilding Market -
Material and manufacturing economics are shifting incentives. Lightweight composites are becoming commercially viable at scale for boutique coachbuilding, while traditional hand‑formed aluminum remains core to the craft aesthetic. These material dynamics affect cost, lead time and design freedom.
Worldwide Luxury Car Coachbuilding Market -
The competitive structure is concentrated. A small group of OEM divisions and specialist coachbuilders captures the majority of market value, creating a dual dynamic of boutique scarcity and high barriers to entry for scale‑dependent services such as low‑volume EV integration.
Top‑line Market Trajectory (Strategic Implication)
From a strategy perspective, the market’s near‑double‑digit projected CAGR signals two concurrent opportunities for incumbents and challengers in 2026: (1) grow premium revenue by converting traditional bespoke buyers to electrified coachbuilds and (2) capture margin uplift through proprietary material know‑how and integrated client experience services. For corporate strategy teams this translates into concrete choices: invest in electrified coachbuilding platforms now, or risk being relegated to second‑tier bespoke offerings within a five‑to‑seven‑year window.
Key Structural Trends Shaping Strategic Choices
-
Electrified Coachbuilding: Landmark initiatives from tier‑one OEM coachbuild divisions have moved EV coachbuilt projects from concept to limited production. The implication for 2026 planning is urgent — electrified chassis integration, battery packaging and thermal management must become core competencies for coachbuilders and their suppliers.
-
Material Transition and Cost Curves: Carbon fibre is the fastest‑growing material class in the sector, posting near‑double‑digit growth rates in recent years as aerospace‑grade costs have meaningfully declined. Aluminum continues to underpin traditional coachbuilding due to hand‑forming advantages, but composites are shifting the product‑performance frontier. Procurement and engineering leaders must reprioritise supplier roadmaps and inventory risk accordingly.
-
Experience‑Centric Revenue Models: New offerings are bundling limited‑run coachbuilt cars with multi‑year client experiences and access programs. This creates recurring revenue possibilities and deeper customer data collection — critical for pricing sophistication and lifecycle services.
-
Concentration and Scale: The market is characterised by a small number of dominant players controlling the lion’s share of value. That concentration raises the strategic bar for new entrants, but also generates M&A and partnership opportunities for suppliers with complementary technical capabilities.
How the Report Helps 2026 Decisions (What’s Actionable)
Our full report is structured to convert insight into tactical programmes for 2026. Key deliverables that corporate decision‑makers will find directly actionable include:
-
Validated market sizing and scenario models that let you stress‑test investment cases for electrified coachbuild lines, bespoke interior programmes and limited series production runs across multiple demand scenarios.
-
A competitive playbook mapping 15+ coachbuilders, OEM divisions and boutique design houses by capability, capacity, client archetype and strategic intent — enabling you to prioritise partnership or acquisition targets.
-
Supplier and materials assessment that contrasts aluminum and composite supply chains, unit costs, lead times and certification barriers, with procurement levers to reduce time‑to‑build for bespoke projects.
-
Go‑to‑market templates for tiered coachbuilt propositions (one‑off commissions, limited‑series drops, subscription‑style experiences) including pricing heuristics and client engagement sequences.
-
Operational playbooks covering engineering integration for electric platforms, IP protection for bespoke designs, factory layout options for low‑volume coachbuilding, and compliance checklists for emissions‑related regulations affecting body structures.
Competitive Landscape — Strategic Readings
The market is shaped by a mix of legacy OEM coachbuild divisions, independent Italian and British maison, modern hypercar specialists and bespoke conversion houses. Our full profiles evaluate each on six strategic axes: design heritage, engineering integration, low‑volume production capability, electrification readiness, client ecosystem and financial model. High‑level takeaways:
-
OEM Coachbuild Divisions (e.g., select marques with in‑house coachbuilding): They command premium pricing, direct access to proprietary platforms and client relationships, and are rapidly integrating electrified limited series into curated client programmes. For strategy teams at adjacent suppliers or potential partners, the priority is to demonstrate technical compatibility with EV architectures and to offer tightly scoped co‑development terms.
-
Italian design ateliers and small‑series coachbuilders: These firms retain design leadership and manual craft advantages. Their strategic edge will be preserved if they can commercialise composites expertise without diluting exclusivity. Collaboration models — joint limited editions or design licensing — will be the growth vector for 2026.
-
High‑performance and tuning houses: They continue to monetise performance upgrades and high‑impact aesthetics, often leveraging carbon fibre competencies. Their challenge is moving from visual conversions to fully integrated coachbuilt electrified products where structural and thermal design matters more than before.
Noteworthy recent developments — illustrative of the strategic shifts described above — include program launches from legacy coachbuilding divisions that pair limited coachbuilt EVs with multi‑year client experiences. Such moves concretely validate the electrified, experience‑first strategic thesis for 2026.
Risks, Constraints and Timing
-
Regulatory and certification timelines can materially affect launch schedules for electrified coachbuilt vehicles. Compliant integration of battery systems into bespoke bodies requires early engineering engagement.
-
Material supply volatility — while carbon fibre costs have declined over the past decade, supplier consolidation and aerospace demand cycles can re‑introduce price and availability risk. Hedging and strategic sourcing must be part of 2026 procurement plans.
-
Client concentration risk: Ultra‑luxury coachbuilding depends on a small, discreet client base. Experience programmes reduce churn but necessitate sophisticated CRM and privacy governance.
-
Brand dilution: For heritage coachbuilders, scaling bespoke offerings risks eroding exclusivity. Carefully tiered product families and strict allocation models are effective mitigants.
Recommendations for 2026 — A Practical Priority List
-
Establish an EV integration task force now: align engineering, legal and purchasing to close platform compatibility gaps within 12 months.
-
Lock in strategic material partners: secure supply agreements for aerospace‑grade composites while maintaining aluminum forming capabilities for craft authenticity.
-
Design a two‑tier client proposition: ultra‑exclusive one‑offs with premium margins, and limited‑series coachbuilt drops that enable recurring revenue and collector community building.
-
Pursue selective partnerships or minority investments with specialised design ateliers to acquire design IP without overpaying for scale economies the ateliers cannot deliver alone.
-
Invest in a compact CRM and digital experience platform that supports multi‑year ownership programmes and captures the data needed for advanced pricing and aftercare monetisation.
About the Full Report
The full PW Consulting market study delivers the underlying dataset, methodology and granular segmentation behind the insights summarised here. It includes scenario models, detailed competitor dossiers, supplier evaluations, and executable playbooks for go‑to‑market, operations and M&A that are calibrated to 2026 execution cycles.
Our approach balances craft heritage and modern engineering: the report combines on‑the‑ground interviews with coachbuilders and OEM engineers, proprietary transaction‑level deal data, and a bottoms‑up assembly of materials and labour cost models to produce investable recommendations. Note: this briefing intentionally highlights strategic takeaways while withholding detailed sub‑segment figures and proprietary splits that are available in the full report.
Next Steps for Executives
-
Request the full PW Consulting report to access the proprietary datasets and scenario models that operationalise the strategies above.
-
Schedule a workshop with our strategy team to tailor the playbook to your organisation’s capabilities and timing constraints; our consultants can run a bespoke 48‑hour rapid assessment to prioritise initiatives for 2026.
For executives planning capital allocation, partnership negotiations, or product roadmaps in 2026, the choice is straightforward: act now to close electrification and materials gaps, or invest to secure premium client experiences that will define the coachbuilt luxury market over the next decade. PW Consulting’s full report provides the validated numbers and the operational templates you will need to execute with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Luxury Car Coachbuilding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com