

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Tuner ICs Market Poised for Steady Expansion at a 4.52% CAGR Through 2032

Worldwide Automotive Tuner ICs Market — Strategic Outlook and Imperatives for 2026 Decision‑Makers
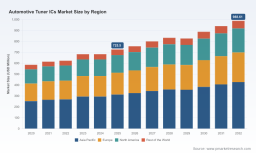
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision‑focused briefing that summarizes the strategic value of our new Worldwide Automotive Tuner ICs Market report for organizations planning their 2026 priorities. The brief highlights the forces shaping supplier selection, product roadmaps and investment choices — and explains why the full report is essential for executable planning. Our core macro view: the Automotive Tuner ICs market reached approximately USD 725.5 Million in 2025 and, under our central forecast, expands to roughly USD 988.6 Million by 2032, implying a compound annual growth rate of about 4.52% across the 2026–2032 horizon. That trajectory combines steady volume demand with structural change, producing both risk and opportunity for suppliers, OEMs and investors.
Worldwide Automotive Tuner ICs Market
Why this market matters for 2026 planning
Tuner ICs sit at the crossroads of several megatrends: the migration from legacy broadcast reception to software‑defined and streaming‑centric infotainment, growing integration of radio receivers with broader vehicle compute and connectivity stacks, and persistent supply‑chain and critical‑materials stress across the semiconductor industry. For executives responsible for product roadmaps, procurement and M&A, decisions in 2026 will determine whether their product families remain cost‑competitive and resilient as vehicle architectures evolve.
Worldwide Automotive Tuner ICs Market
Key contextual signals we folded into our analysis include recent OEM product decisions that accelerate broadcast displacement (most notably the announced removal of AM/FM tuners from entry trims by a major EV OEM), widening semiconductor lead times in late 2025 and early 2026, and acute raw‑material policy shifts that introduce geopolitical supply risk for certain compound semiconductors. Together these developments change the time horizons and tactics that will be effective in 2026.
Worldwide Automotive Tuner ICs Market
Market structure and concentration — strategic implications
The tuner IC market remains concentrated. Our concentration metrics show a high degree of market share aggregation at the top: the three largest suppliers account for a significant majority of revenues, and the top five push concentration still higher. That structure creates a two‑tier reality for buyers and new entrants alike. For OEMs and Tier‑1s, a compact supplier base simplifies qualification logistics but increases supplier leverage on price and roadmap timing. For smaller IC suppliers and potential disruptors, winning a niche will require either highly differentiated technology (e.g., superior low‑power digital front ends or integrated multi‑standard receivers) or a proven mitigation strategy for supply risk.
Competitive landscape — capabilities that matter in 2026
- NXP Semiconductors (Eindhoven, Netherlands) — Broad automotive radio tuner portfolio with alignment‑free low‑IF and single‑chip multi‑standard solutions. Strengths: deep automotive relationships and integration capabilities for infotainment stacks.
- STMicroelectronics (Geneva, Switzerland) — Comprehensive AM/FM and digital broadcast receiver lineup, spanning entry‑level to multi‑antenna high‑end designs and strong automotive qualification. Strengths: system‑level support and multi‑standard roadmaps.
- Infineon Technologies (Neubiberg, Germany) — Recognized leader in automotive semiconductors; expanding power and system solutions that intersect with infotainment power domains. Strengths: automotive grade portfolio and scale in vehicle electronics.
- Texas Instruments (Dallas, USA) — Supplier of analog and mixed‑signal building blocks that remain essential to tuner sub‑systems. Strengths: analog excellence and broad design‑win footprint.
- Analog Devices (Wilmington, USA) — High‑performance analog/RF and mixed‑signal solutions for signal processing in infotainment and tuner applications. Strengths: performance leaders for high‑fidelity designs.
- ROHM Semiconductor (Kyoto, Japan) — Offering automotive ICs that support in‑vehicle electronics and infotainment platforms. Strengths: integration and reliability for Japanese OEMs and tier suppliers.
- ON Semiconductor / onsemi (Scottsdale, USA) — Automotive‑qualified power and IC solutions across vehicle electronics, including subsystems that interface with infotainment architectures. Strengths: power management and qualification breadth.
These players collectively define the available technology architectures for OEMs and tier suppliers. In our report we benchmark their product portfolios, qualification timelines and go‑to‑market approaches — and show where gaps exist for challengers to pursue.
Supply‑chain and policy shocks to plan for in 2026
- Raw‑material policy risk: Export controls and licensing regimes for key inputs (including gallium and germanium) raise sourcing and cost uncertainties. Several governments have introduced or discussed measures that can alter supply economics within months.
- Lead‑time inflation: Automotive semiconductor lead times lengthened materially in Q4 2025, and select device categories show lead windows stretching into the 30–42 week band early in 2026. Buyers must assume extended qualification and replenishment cycles.
- Critical‑minerals coordination: New bilateral and multilateral agreements among major markets are likely to shift pricing and minimum‑price discussions for minerals relevant to semiconductor manufacture — an inflationary force for certain component classes.
- Memory price volatility: Legacy memory types used in infotainment systems experienced steep price increases early in 2026, adding cost pressure to module‑level BOMs and amplifying the need for re‑costing and hedging strategies.
These factors collectively make single‑source dependency and thin inventory strategies much riskier. They also amplify the commercial value of IC suppliers that can secure long‑run supply agreements with wafer fabs or offer alternative silicon solutions that reduce reliance on constrained materials.
What the PW Consulting report delivers — practical content for 2026 execution
We built the report to be actionable for procurement teams, product leaders, investors and corporate strategists. Highlights include:
- Robust market sizing and a transparent forecasting framework (base year 2025 through 2032) that decomposes demand drivers and quantifies upside/downside scenarios.
- Concentration and competitive mapping with supplier capability matrices, qualification lead‑time benchmarks, and a supplier risk scorecard tied to raw material exposure and geopolitical sensitivity.
- Scenario planning modules that model the commercial impact of accelerated AM/FM removal, streaming‑first OEM strategies, and technology adoption curves for digital vs analog tuners (note: detailed segment-level metrics are contained within the full report).
- Procurement playbooks: recommended contract structures, inventory buffers, hedging approaches for memory and critical substrates, and a prioritization matrix for multi‑sourcing.
- Product roadmap guidance for OEMs and IC vendors: trade‑offs between single‑chip integration, software‑defined radio strategies, antenna diversity, and certification schedules.
- Financial and M&A checklists: valuation sensitivities to supply‑chain shocks, integration risks, and target‑qualification timelines for acquisitive consolidation.
Each element is supported by traceable data sources and a full methodology appendix so decision‑makers can validate assumptions and re‑run scenarios against internal inputs.
Recommended 2026 actions — prioritized and practical
- Immediate (0–6 months): Conduct a supplier resilience audit that includes second‑source feasibility, alternative material qualifications, and renegotiation of lead‑time SLAs. Prioritize components with the longest reported lead windows and the highest exposure to volatile memory prices.
- Near term (6–18 months): Accelerate design wins for software‑defined radio and digital tuner architectures in parallel with legacy analog solutions, but de‑risk transitions via modular hardware abstractions and field‑updateable firmware.
- Strategic (18–36 months): Consider selective vertical integration or long‑term strategic partnerships with suppliers that can provide wafer access or control over critical substrates. For OEMs, evaluate trade‑off matrices for removing legacy broadcast hardware versus maintaining hybrid support for markets where broadcast remains prevalent.
- Corporate finance: Update valuation models to include scenario stress tests for critical‑material price shocks and to reflect market concentration advantages or exposures. For investors, identify targets with differentiated technology or low‑risk supply footprints.
How to use our findings in boardroom decisions
Boards and executive teams need concise, evidence‑based inputs to decide on capital allocation and product commitments in 2026. Use the following framework derived from the report:
- Test the strategic hypothesis: Will your product roadmap require integrated tuner ICs beyond 2026, or is a transition to streaming and software sufficient? Run both scenarios against our demand curves and sensitivity tables.
- Quantify supplier risk: Use our supplier risk scorecard to identify the top three vendors with the most favorable combined profile of technical fit, business terms and supply security.
- Set procurement KPIs: Move from price‑only metrics to a composite KPI that includes lead‑time volatility, material exposure and qualification velocity.
- Plan for optionality: Fund a modest R&D reserve to pivot to alternative silicon or software solutions if material restrictions tighten further than anticipated.
Why PW Consulting’s report is the practical input you need for 2026
Our analysis combines granular supplier benchmarking, scenario modelling calibrated to the latest policy and supply‑chain signals, and transaction‑oriented guidance that translates forecast insights into executable actions. The market’s projected growth (CAGR ~4.52% through 2032) masks substantial strategic variance across customer segments, regional policies and technology choices — variance that the full report quantifies and turns into operational recommendations.
This briefing intentionally provides a strategic overview while withholding detailed, segment‑level numbers and the full competitive scoring matrix that are included in the full report. That detailed intelligence — including the regional, application and type breakdowns, supplier scorecards and downloadable model files — is available in the complete PW Consulting Worldwide Automotive Tuner ICs Market report.
To obtain the report, access the PW Consulting publications page or contact our industry team for a briefing and a tailored executive summary that applies the findings to your product, procurement and M&A priorities for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Tuner ICs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com