

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide 3D ToF Market Hits USD 6,450.5 Million in 2025, Set to Surge to USD 21,165.17 Million by 2032 at an 18.5% CAGR

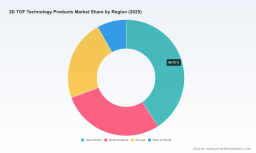
Worldwide 3D ToF Technology Products Market: Strategic Briefing for 2026 Decisions
PW Consulting today publishes an executive briefing drawn from our forthcoming Worldwide 3D Time-of-Flight (ToF) Technology Products Market report. The briefing synthesizes actionable insights for executives preparing capital allocation, product roadmaps, and ecosystem strategies in 2026. Our analysis puts the market in context: from a base of USD 6,450.5 Million in 2025 the market is expected to reach approximately USD 8,029.6 Million in 2026 and to expand at a compounded annual growth rate (CAGR) of 18.5% through the 2026–2032 forecast window—underscoring a rapid, programmatic shift in where and how three-dimensional sensing will be deployed across end markets.
Worldwide 3D TOF Technology Products Market
Why 2026 Is a Strategic Inflection Point
-
Acceleration from multiple fronts: Convergence of higher-resolution imaging, lower-cost illumination sources, and more capable edge compute is moving ToF from niche use-cases into mainstream device architectures. This is manifest in broadened adoption across consumer electronics, automotive perception stacks, industrial automation, and robotics platforms.
Worldwide 3D TOF Technology Products Market -
Technology crossroads: Indirect ToF architectures continue to push the envelope in point-cloud fidelity, but are constrained by SPAD array complexity and readout speed—practical limits that currently confine many indirect systems to VGA-equivalent implementations. Direct ToF systems, by contrast, are demonstrating improved sunlight immunity with modulated laser approaches, shifting the tradeoffs for outdoor-capable applications.
Worldwide 3D TOF Technology Products Market -
Regulatory and standards pressure: Automotive safety standards (e.g., ISO 26262 requirements) and interface standardization (such as MIPI I3C adoption for high-speed sensor data) are making compliance and platform interoperability non-negotiable design constraints for any OEM targeting ADAS and automotive body applications.
-
Market structure and concentration: The market displays moderate concentration—our analysis of provider share indicates that leading triads and quintets command substantial portions of value creation—an important consideration for sourcing, negotiation leverage, and M&A strategy.
What PW Consulting’s Report Delivers — Practical, Executable Insight
-
Robust market-sizing and scenario planning: Granular topline trajectories with three disruption scenarios that stress-test demand under differing technology, regulatory, and macroeconomic outcomes.
-
Actionable go-to-market frameworks: Roadmaps for product managers and BD teams covering integration trade-offs (sensor vs. module vs. camera), preferred partnership models, and margin-sensitive pricing envelopes.
-
Vendor heatmaps and supplier risk matrices: Comparative scoring across technology maturity, production scale, IP position, and time-to-certification for safety-critical markets.
-
Component-level economics and cost-degression curves: Forecasts for sensors, illumination sources, optics, and ancillary components linked to procurement strategies and BOM optimization (note: segmented financials and unit economics are available in the full report).
-
Technical annex and integration playbooks: Engineering-focused guidance on mitigating ambient-light interference, achieving necessary ASIL levels for automotive programs, and implementing MIPI-based interfaces at scale.
-
Commercial playbook for investors and acquirers: Due diligence checklists, valuation sensitivities tied to commercialization timing, and recommended KPIs for tracking portfolio companies.
Competitive Landscape — Who’s Moving and What It Means for 2026
Our competitive assessment profiles established semiconductor suppliers, specialized module vendors, and camera OEMs. Below are strategic highlights for the most active players and the implications for market participants planning 2026 initiatives.
-
STMicroelectronics (Geneva) — Strengths: broad FlightSense ToF portfolio and multi-zone direct ToF parts with improved ambient-light immunity. Implication: ST’s advances reduce outdoor performance risk for consumer and robotics applications; OEMs should evaluate ST’s latest multi-zone offerings early in 2026 for pilot programs where sunlight robustness is a gating constraint.
-
ams OSRAM (Premstätten) — Strengths: compact multi-zone sensors optimized for gesture and proximity. Implication: Expect aggressive positioning in form-factor-constrained consumer and automotive interior sensing; partners should prioritize low-power and miniaturization opportunities.
-
Infineon Technologies (Neubiberg) — Strengths: indirect ToF image sensors tailored for automotive and robotics. Implication: Infineon’s automotive demos signal accelerated feature integration for ADAS/occupancy sensing; software partners must prepare for close hardware–firmware co-development to meet ASIL requirements.
-
pmdtechnologies (Ulm) — Strengths: module-level expertise in indirect ToF for industrial and AR/VR references. Implication: pmdtechnologies’ AR glass integrations highlight the opportunity for specialized module vendors to capture value by supplying reference designs and developer ecosystems.
-
Sony Semiconductor Solutions (Tokyo) — Strengths: high-resolution stacked CMOS ToF sensors and automotive-grade certifications. Implication: Sony’s certification roadmap positions it as a strategic supplier for high-reliability applications; OEM roadmaps should align procurement cycles to Sony’s qualification timelines.
-
Texas Instruments & OmniVision — Strengths: TI’s multi-zone sensors for drones/IoT and OmniVision’s front-facing ToF parts for secure UX. Implication: Expect differentiated competition in edge and security-focused use cases; software-driven segmentation will be decisive.
-
Camera and module specialists (Basler, Lucid Vision Labs, ifm electronic) — Strengths: turn-key 3D camera systems for factory automation and logistics. Implication: System integrators should prioritize partnerships with camera OEMs to accelerate deployment cycles while mitigating in-house development risk.
Recent Industry Movements: Signals to Monitor in 2026
-
Product refreshes and demos are accelerating: Major suppliers continue to refresh portfolios emphasizing ambient-light robustness and automotive readiness; these releases are precursors to accelerated OEM qualification programs.
-
Strategic integrations: Partnerships around AR reference designs and camera-module tie-ups are creating new route-to-market options for semiconductor vendors and integrators.
-
Standard and regulatory alignment: MIPI I3C interface adoption and automotive safety compliance are increasing technical entry costs but also creating differentiation for compliant suppliers.
Eight Strategic Priorities for 2026
-
Prioritize pilot-to-scale validation: Launch 12–18 month pilot programs that embed both hardware and edge-processing stacks—de-risking qualification lead-times for automotive and industrial customers.
-
Adopt standards early: Implement MIPI-compliant interfaces and align development timelines with expected certification windows to avoid costly redesigns.
-
Invest in ambient-light mitigation: For outdoor and mixed-light scenarios, prioritize partners and sensor architectures that demonstrably reduce error rates under high illuminance.
-
Differentiate through software: Treat point-cloud processing, AI-based denoising, and privacy-preserving depth abstraction as primary product differentiators rather than afterthoughts.
-
Design for ASIL-readiness where relevant: For any program interfacing with vehicle perception, start functional safety planning now—hardware choices and supply agreements must reflect functional safety roadmaps.
-
Build modular commercial options: Offer sensor-only, sensor+module, and camera-system alternatives to address differing customer risk appetites and integration capabilities.
-
Monitor consolidation and partnership windows: With significant value concentrated among leading suppliers, prepare M&A or JVs to secure capability gaps and scale advantages.
-
Be explicit on privacy and ethics: Implement opt-in depth sensing and limit raw point-cloud export in consumer deployments to pre-empt regulation and consumer resistance.
Next Steps and How to Use the Full Report
PW Consulting’s full report contains the complete datasets, segmented forecasts, supplier benchmarking matrices, and executable playbooks referenced above. If your 2026 strategy involves product launches, sourcing decisions, partnership formation, or investment in 3D sensing capabilities, the report supplies the empirical foundation and step-by-step guidance needed to convert opportunity into realized revenue.
To access the complete intelligence, including the detailed segmentation, proprietary financial models, and supplier scorecards that we intentionally reserve for the full report, please visit PW Consulting’s report portal. Our analysts are available for bespoke briefings and scenario workshops tailored to executive planning cycles for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide 3D TOF Technology Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com