

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Liquid Termiticides Market Poised to Reach USD 4,042.31 Million by 2032, Riding a 5.12% CAGR

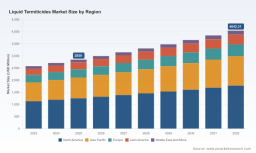
Worldwide Liquid Termiticides Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive summary
PW Consulting’s newest market study, “Worldwide Liquid Termiticides Market,” offers a forward-looking, decision-grade analysis designed for executives who must act in 2026. Built on a 2025 base-year assessment and a seven-year forecasting window (2026–2032), the study projects continued expansion at a 5.12% CAGR. In our baseline view, the market expands from a 2025 valuation to a materially larger opportunity by 2032, driven by converging forces in construction activity, regulatory shifts, raw-material volatility, and the accelerating adoption of lower-risk chemistries and integrated service models.
Worldwide Liquid Termiticides Market
Why this preview matters for 2026 strategy
Leaders in manufacturers, distributors, professional pest management firms, and private equity investors face an inflection point: incremental revenue growth is available, but commercial and regulatory headwinds are growing more complex. This report is intended as a practical bridge between macro trends and implementable tactics. It highlights how to reposition portfolios, hedge procurement exposures, and structure go-to-market approaches that protect margin while meeting evolving stewardship and compliance expectations.
Worldwide Liquid Termiticides Market
- Authoritative market sizing and a transparent forecasting methodology to underpin investment cases and board-level briefings.
- Scenario modeling tools that quantify impacts from raw-material price shocks, regulatory constraints, and adoption of reduced‑risk actives.
- Actionable go-to-market playbooks and cost-to-serve benchmarks that translate strategy into operations.
- A competitive framework and M&A screen designed to support bolt-on and capability-building transactions in 2026.
What the numbers tell us (high-level)
Using consistent historical tracking (2020–2025) and forward projections (2026–2032), PW Consulting quantifies the market trajectory and provides clear sensitivity testing around the 5.12% CAGR. The headline is straightforward: the global liquid termiticides market remains a growing, mid-sized specialty-chemical market with attractive pockets for premium service offerings and innovation-led share gains. However, growth will be uneven across operator types and product classes, and success will depend on aligning product stewardship and supply resilience with commercial execution.
Worldwide Liquid Termiticides Market
Competitive landscape: dynamics and strategic positioning
The competitive field blends multinational incumbents with agile regional and generic suppliers. Leading legacy manufacturers maintain deep channel relationships, extensive registration portfolios, and brand recognition in professional pest management channels. At the same time, mid-sized players and specialized suppliers are increasingly competing on formulation flexibility, service integration, and pricing.
- BASF SE: Strength lies in a flagship portfolio focused on professional soil treatments and strong technical support offerings. Established product platforms and HE (high-efficiency) formulations make BASF a reference point for barrier technologies.
- Syngenta AG: Positioned around reduced‑risk chemistry, Syngenta’s Altriset is a strategic example of how lower-toxicity actives can establish premium positioning—particularly as regulators and purchasers press for safer alternatives.
- FMC Corporation: A broad pyrethroid-based offering and professional channel reach provide FMC with scale advantages, particularly where price and distribution breadth remain decisive.
- Bayer AG: Known for established soil‑barrier formulations; Bayer faces the same regulatory and stewardship pressures that affect neonicotinoid-class chemistries.
- Niche and generic players (e.g., Nufarm, Sumitomo, Control Solutions, Ensystex): These firms provide competitive pressure on pricing and service models, and in several markets they are driving faster adoption of bundled services including baits and digital monitoring.
Market concentration is moderate: the combined share of the three largest firms indicates a measurable incumbent advantage, while the top five capture a clear majority of market value. That structure creates a strategic landscape where incumbents can defend scale advantages but new entrants or specialist product owners can carve high-margin niches with differentiated propositions.
Regulatory and raw-material risk — the operative constraints
Two sets of non-market forces will be decisive in 2026: regulatory policy and raw-material supply/price dynamics. Recent regulatory activity, including a 2025 insecticide strategy from a major regulator that tightens mitigation for non-target species, is changing allowable use patterns and creating additional compliance costs for product labels and field protocols. Separately, regulatory tolerances and time-limited approvals for certain actives have created short- to medium-term uncertainty around product lifecycle economics.
On the input side, specialty active ingredients have experienced meaningful price pressure. For example, common actives experienced double-digit cost increases in recent historical windows, tightening gross margins for formulators that cannot quickly pass costs through to professional customers. Geopolitical and logistical disruptions have exacerbated these pressures, underscoring the importance of diversified sources and contingency inventory planning.
Strategic pathways we recommend for 2026
Based on our analysis, companies should prioritize a small set of strategic moves that are high-impact and executable within 12–24 months:
- Portfolio repositioning: Accelerate development and commercialization of reduced‑risk chemistries and non-chemical adjuncts (e.g., baits, physical barriers) to mitigate regulatory risk and capture premium pricing.
- Supply-chain resilience: Negotiate multi-year supply agreements, localize critical intermediates where feasible, and build inventory buffers for key actives to smooth price volatility.
- Service-led monetization: Convert one-time treatments into recurring revenue via monitoring subscriptions, technician certification programs, and bundled inspection services.
- Value-based pricing and channel segmentation: Differentiate pricing and service models by end-customer willingness to pay; extend premium technician-led installations where reliability and warranty claims matter most.
- M&A and partnership playbook: Target regional service providers, digital monitoring startups, and registration/registrant entities to speed market entry and expand capability sets without extended greenfield timelines.
Operational playbook highlights
The full report includes an operational playbook with tactical templates. Examples include:
- Cost pass-through scenarios that quantify margin impacts under raw-material shock scenarios and recommended contract language for distributors and large fleet accounts.
- SKU rationalization guidelines to reduce inventory carrying costs while preserving coverage for priority use-cases and high-margin products.
- Technician productivity and training benchmarks that convert field expertise into measurable warranty performance and cross-sell rates.
- Regulatory readiness checklist to accelerate label amendments, implement stewardship programs, and prepare for jurisdictional tolerance changes.
Report contents — what you will get when you download the full study
Pursuant to the “preview” objective, PW Consulting details the scope of the deliverable without disclosing all segmented tables here. The complete report package includes:
- Market sizing and a transparent forecast model (base year 2025; forecast period 2026–2032) delivered in an editable spreadsheet.
- Scenario analyses testing regulatory, raw-material, and demand-side shocks with probability-weighted impacts on revenue and margin.
- Competitive benchmarking across technical capabilities, channel coverage, registration strength, and service offerings for the key players in the space.
- Segmentation analysis by product type, application mode, and distribution channel, with prioritized country- and region-level opportunity maps.
- Supply-chain risk assessment, including supplier concentration, logistics exposure, and price sensitivity modeling tied to active‑ingredient inputs.
- Commercial playbooks: go-to-market strategies tailored for manufacturers, distributors, and professional pest management companies.
- M&A and partnership candidate screen with scoring criteria tailored to strategic fit, integration complexity, and expected ROI horizons.
- Case studies and operator-level unit economics to shorten implementation cycles.
How to use this study in boardroom decisions for 2026
Executives should use the report as their single source of truth for investment prioritization and tactical planning. Typical use cases include:
- Validating a go/no-go decision on a new active or formulation based on forecasted incremental revenue versus anticipated registration and stewardship costs.
- Structuring procurement hedges and inventory policy for critical actives in the face of demonstrated historical price volatility.
- Framing M&A diligence on regional service providers and digital monitoring assets with quantifiable synergies and payback timelines.
- Aligning commercial incentives and field operations to capture value from premium, service-led offerings that reduce reliance on commodity pricing.
Closing perspective
The worldwide liquid termiticides market in 2026 is neither a simple commodity contest nor a closed oligopoly. It is a dynamic specialty-chemical and service ecosystem where regulatory stewardship, formulation innovation, and service economics will determine winners. PW Consulting’s report equips leaders with the quantitative forecasts, scenario tools, and operational playbooks required to translate insight into advantage. For a full set of tables, segment detail, and the editable forecast model that executives use for board and investment committee presentations, please visit the PW Consulting report page to download the complete study.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Termiticides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com