

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Digital Dermatoscope Market to Grow at 9.2% CAGR, Reaching USD 2,155.38 Million by 2032

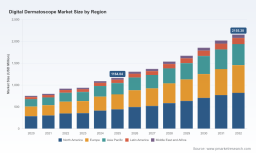
Worldwide Digital Dermatoscope Market: Strategic Insights to Shape 2026 Decisions
Executive preview — why this PW Consulting report matters to executives preparing for 2026
PW Consulting’s latest market research on the Worldwide Digital Dermatoscope Market delivers a concise, action-oriented intelligence package designed for boardrooms, product teams, and investors making decisions for 2026 and beyond. Built on a 2020–2025 historical foundation with 2025 as the base year and a detailed forecast spanning 2026–2032, the study synthesizes market trajectory, technology dynamics, regulatory levers, and vendor strategies into an operational playbook.
Worldwide Digital Dermatoscope Market
At the macro level, the market has experienced robust expansion over the 2020–2025 period and is forecast to continue growing at a compound annual growth rate (CAGR) of 9.2% across the 2026–2032 projection window. This momentum reflects accelerating clinical adoption, improved imaging and AI capabilities, and expanding teledermatology use cases. For decision makers, these facts are not abstract — they translate into product roadmaps, go‑to‑market timing, and capital allocation choices that will define winners and laggards in the next three to five years.
Worldwide Digital Dermatoscope Market
Market context and near-term inflection points
-
Market maturity and growth dynamics: The digital dermatoscope category has moved beyond early adopter clinics into broader outpatient and hospital workflows. This structural shift supports sustainable top‑line growth and creates opportunity for differentiated service models, such as imaging-as-a-service and managed teledermatology platforms.
Worldwide Digital Dermatoscope Market -
Technology combine: High‑resolution optics, LED illumination, and embedded AI lesion analysis are converging to raise the clinical utility of devices. This technical progress is enabling new software-enabled revenue streams (diagnostic support, image tracking, population screening) that can materially expand lifetime value per installed device.
-
Cost and supply considerations: Medical‑grade optics and LED sub‑assemblies remain a dominant portion of manufacturing cost, representing a strategic leverage point for margin improvement either through vertical integration, component partnerships, or design optimization.
-
Regulatory and reimbursement levers: Compliance with medical electrical safety standards (e.g., IEC 60601‑1) and the availability of relevant outpatient procedure reimbursement codes are shaping procurement decisions in primary care and specialist settings. These factors can accelerate adoption where coverage and compliance are clear, and create friction where they are ambiguous.
What the PW Consulting report contains — the operative intelligence you can action now
-
Market sizing and trend lines: A validated baseline and multi‑year forecast (2026–2032) that quantify the growth runway and highlight demand inflection points tied to technology adoption cycles.
-
Adoption and use‑case mapping: Practical segmentation by product architecture and end‑user workflows, showing where handheld devices, integrated imaging systems, and software suites create differentiated value.
-
Economics and unit‑cost modeling: Breakdowns of manufacturing cost drivers, margin sensitivity analyses, and supplier risk maps to support sourcing and product development tradeoffs.
-
Regulatory, pricing and reimbursement playbook: A checklist for compliance (including key safety standards), payer engagement templates, and coding strategies for outpatient deployment.
-
Competitive benchmarking and vendor strategies: Side‑by‑side diagnostics of leading incumbents, go‑to‑market archetypes, recent product and certification activity, and M&A/partnership scenarios.
-
Commercial scenarios and decision frameworks: Actionable scenarios for market entrants, incumbent hardware OEMs, imaging‑software integrators, and private equity — plus a risk‑adjusted matrix to prioritize initiatives for 2026.
-
Executive recommendations and 100‑day playbooks: Concrete steps for C‑suite, product and commercial leaders to capture the most attractive pockets of growth during 2026.
Competitive landscape — who matters and why
The market is characterized by a mix of specialist optics manufacturers, clinical imaging system integrators, and nimble USB/portable device vendors. Rather than enumerate proprietary market shares here, the report synthesizes relative positioning across four dimensions: clinical credibility, imaging and AI capability, integration & interoperability, and commercial reach.
-
Heine Optotechnik (Herrsching, Germany) — A leader in precision optics and digital dermatoscope hardware, Heine’s DELTA series emphasizes advanced imaging fidelity and early AI integration for melanoma detection. Recent regulatory milestones (updated CE marking) sharpen its competitive credibility in regulated markets and enable faster commercial deployment.
-
DermLite (Caliber I.D., Inc.; Vista, CA, USA) — Known for practical, clinician‑focused devices, DermLite blends polarized/non‑polarized imaging with app and teledermatology connectivity. Their presence at major clinical conferences underscores a user‑centric field engagement strategy that fuels adoption among dermatology specialists.
-
FotoFinder Systems (Bad Birnbach, Germany) — FotoFinder pairs total‑body imaging and lesion analysis tools with AI software (e.g., Moleanalyzer). A recent software release strengthened its lesion analytics roadmap and underscores the growing importance of software upgrades and subscription revenues.
-
Canfield Scientific (Parsippany, NJ, USA) — Canfield’s portfolio links imaging devices with enterprise‑grade vision software for tracking and workflow integration, positioning it well for hospital deployments and multi‑user clinical environments.
-
Dinolite (Los Alamitos, CA, USA) — Offering portable, cost‑effective USB dermatoscopes, Dinolite targets broad clinical and point‑of‑care use cases where price and mobility trump enterprise integration.
-
AnMo Electronics Corporation (New Taipei City, Taiwan) — Focused on USB and wireless dermatoscopes with LED lighting, AnMo competes on device versatility and affordability, making it a frequent choice for clinics and telehealth providers adding imaging capabilities rapidly.
The report expands on these profiles with comparative product matrices, recent development timelines, patent landscapes, and partnership/ distribution mapping to highlight where rivals are likely to invest in 2026.
Recent vendor moves that shape 2026 competitive dynamics
-
Product innovation continues to be front and center: a major vendor released an AI‑enhanced lesion analysis upgrade in late 2024, demonstrating the cadence of software differentiation and upgrade monetization.
-
Regulatory certifications issued during 2024 for advanced models signal that next‑generation imaging platforms are cleared for broader market release — a trigger for procurement cycles in 2026.
-
Conference visibility and app integrations shown in 2024 illustrate vendor emphasis on interoperability and clinician workflows — a leading indicator of which players will succeed in enterprise deployments.
Strategic implications and recommended actions for 2026
Based on the modeled market trajectory and competitive activity, PW Consulting recommends the following priority actions for key stakeholders:
-
Hardware OEMs: Prioritize modular architectures that separate optics, illumination, and compute. This reduces time‑to‑market for software upgrades and creates cross‑sell opportunities for AI services. Pursue selective vertical integration of critical optical components or long‑term supplier contracts to protect margins.
-
Imaging‑software companies: Invest in clinically validated AI models and interoperability (FHIR/API) to become the preferred analytics layer. Consider SaaS pricing to capture recurring revenue as clinical workflows shift to subscription models.
-
Hospitals and clinics: Evaluate strategic pilots that pair handheld devices for point‑of‑care triage with integrated systems for high‑risk patient management. Use procurement windows following regulatory clearances to negotiate bundled hardware+software deals tied to performance metrics.
-
Payers and public health bodies: Leverage reimbursement levers to incentivize early detection programs using validated digital dermatoscopy workflows. Clear coding and payment pathways will be key to scaling population screening pilots into sustainable programs.
-
Investors and corporate development teams: Target companies with defensible data assets (annotated imaging libraries), repeatable upgrade revenue, and clear pathways to hospital interoperability. M&A activity is likely centered on bolt‑on analytics and component suppliers through 2026.
Risk factors and blind spots to monitor
-
Regulatory uncertainty in non‑OECD markets that may delay broad deployment.
-
Data privacy and cross‑border data transfer constraints that could limit cloud‑based analytics adoption in certain jurisdictions.
-
Supply chain pressure on optical and LED components; single‑source dependencies can cause production bottlenecks.
Why PW Consulting’s report is essential reading for 2026 planning
This report is more than a market forecast: it is a playbook that translates growth curves and vendor moves into executable strategy. For leaders deciding where to allocate R&D budgets, when to pursue certification, or how to package hardware with analytics subscriptions, the report frames the tradeoffs and provides templates — from 100‑day commercialization plans to sample reimbursement arguments — that are ready to adapt to organizational constraints.
We purposefully present high‑level signals and strategic levers here while withholding granular segment valuations and proprietary competitive metrics to preserve the report’s primary value as the definitive source of record. For access to the full dataset, segmented forecasts, and the executable 2026 playbooks, please visit PW Consulting’s Worldwide Digital Dermatoscope Market report page.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Dermatoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com