

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Active Optical Cable & Extender Market Set to Rise from USD 4.50 Billion in 2025 to USD 14.34 Billion by 2032 on an 18% CAGR

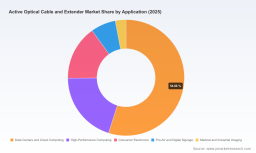
Worldwide Active Optical Cable and Extender Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s new market study on the Worldwide Active Optical Cable (AOC) and Extender market frames 2026 as a decisive year for infrastructure owners, hyperscalers, component suppliers and systems integrators. Our analysis—anchored on a comprehensive historical window (2020–2025) and a scenario-driven forecast through 2032—finds the market expanding rapidly from a multi‑billion dollar base in 2025 and accelerating into a sustained growth trajectory (18.0% CAGR across the forecast horizon). This release previews the strategic levers and risk vectors executives must prioritize to convert growth into durable advantage.
Worldwide Active Optical Cable and Extender Market
Market trajectory at a glance
Based on the consolidated model used throughout our research, the global AOC and extender market showed accelerated adoption through 2024–2025, reflecting compressed time-to-deploy in data center and enterprise initiatives. Our baseline shows notable year‑on‑year expansion into 2026 and beyond, with the market roughly doubling over the forecast period to 2032 under the core scenario. Those topline dynamics are driven by an interplay of hyperscale bandwidth demand, AI/ML workloads that push optical density, and aggressive product innovation from both legacy and new entrants.
Worldwide Active Optical Cable and Extender Market
Why 2026 is an inflection point
- AI-driven density: The shift to large-scale AI clusters is materially increasing interconnect density requirements. This is creating sustained demand for higher‑performance optical links and for packaging innovations that preserve rack-level thermal and power envelopes.
- Technology convergence: Miniaturization trends—such as multicore fibers, micro‑cable architectures and nascent microLED optical sources—are moving quickly from lab to product demonstrations, enabling new form-factor tradeoffs in AOC design.
- Price & procurement dynamics: Standard 100G AOC units continue to experience 12–15% annual price erosion while a pronounced pricing gap persists between OEM-coded and compatible white‑box alternatives. That pricing differential is reshaping procurement strategies.
- Supply constraints & component concentration: Critical optoelectronic components (VCSELs, photodetectors, and advanced transceiver chipsets) account for a large share of the bill of materials and remain capacity‑constrained, producing lead times that can extend to 6–8 months for some configurations.
- Geopolitical friction: Tariff actions and trade policy uncertainty add procurement risk, particularly for projects that span multi‑jurisdictional supply chains and that rely on cross-border sourcing of critical components.
What the PW Consulting report delivers — practical, implementable content
Our report is built for decision-makers. It goes beyond market sizing to provide hands-on frameworks you can apply immediately:
Worldwide Active Optical Cable and Extender Market
- Robust topline forecasts and sensitivity scenarios (base, upside, downside) that translate demand drivers into procurement timing and capital planning inputs.
- A vendor scorecard and strategic positioning matrix that evaluates technology differentiation, manufacturing scale, and route-to-market—designed to support shortlists for qualification and vendor consolidation.
- Cost build-up and TCO models that isolate the transceiver-dominated bill of materials and quantify implications of component price erosion and alternative coding strategies.
- Supply-chain risk maps and mitigation playbooks, including contract structures that shorten lead‑time exposure and clauses suited to volatile tariff environments.
- Engineering checklists for interoperability testing, qualification gating and lifecycle management—useful for CTOs and data‑center architects during design cycles.
- M&A and partnership heatmaps highlighting where consolidation or vertical integration is most likely to create value for platform players and component specialists.
Competitive landscape — who matters and why
The market exhibits a medium concentration profile: the top three players hold a material but not dominant share, and the top five capture a clear majority of revenue—creating space for both scale players and fast‑moving specialists. Key competitive dynamics we observe:
- Incumbent material and fiber specialists are leveraging depth in optical materials and manufacturing to push density and reliability improvements. Their investment in multicore fiber and micro cables is a deliberate play for data center interconnect upgrades.
- Component and chipset leaders are integrating connectivity and optics into broader silicon portfolios, reducing friction for hyperscale OEMs that prefer single‑source optics modules that pair to their ASICs and NICs.
- Connectivity and cable suppliers emphasize ruggedization and vertical B2B channels—addressing industrial, military and enterprise networking segments where reliability and qualification matter more than unit price.
- Newer, cost‑focused manufacturers—many based in Asia—are aggressively addressing the white‑box and secondary OEM opportunity, intensifying the price gap debate and creating tradeoffs for buyers between short‑term cost and long‑term vendor support.
Recent strategic moves underline these trajectories. Market leaders showcased density and co‑packaged optics innovations at industry events early in 2026, while semiconductor and photonics collaborations announced microLED‑based approaches that promise improved efficiency and integration in coming product cycles.
Procurement & engineering playbook for 2026
For organizations planning capital deployments over the next 12–24 months, our report prescribes a prioritized set of actions:
- Diversify component sources while qualifying a primary supply partner for long‑lead optoelectronic parts; explicitly model 6–8 month sourcing delays in project timelines.
- Institutionalize a dual-track procurement approach: strategic buys of OEM-coded cables for critical paths, and tactical adoption of validated white‑box units for non‑mission-critical links to capture cost savings.
- Build procurement clauses that address pricing erosion and supply fairness—indexing volumes or including price guides tied to defined degradation curves rather than fixed one‑time prices.
- Prioritize interoperability testing early in procurement cycles; require vendors to meet common electrical and thermal profiles to reduce field surprises during rollouts.
- Adopt TCO frameworks that quantify cooling, power and replacement costs across the expected lifecycle rather than focusing solely on unit price.
Strategic guidance for vendors and investors
Suppliers and investors should view 2026 as a window to reposition around three high‑value initiatives:
- Differentiate through technology and systems: invest in multicore fibers, micro‑cable routing, and co‑packaged optics integration where scale advantages create structural barriers.
- Targeted verticalization and partnerships: form alliances with hyperscalers and silicon vendors to embed optical solutions into end‑to‑end stacks—this raises switching costs and captures more of the BOM value pool.
- Cost leadership via chipset optimization: because the transceiver chipset dominates material cost, focused R&D to reduce power, footprint and cost per lane yields asymmetric returns.
Our M&A overlays identify logical adjacencies—component makers, test/qualification specialists, and regional manufacturing footholds—that accelerate scale or fill capability gaps. Investors should prioritize businesses that combine technical IP with stable channel relationships and defensible manufacturing scale.
Research methodology and confidence
PW Consulting’s analysis is grounded in a blended methodology: primary interviews with vendors, hyperscalers and systems integrators; bottom‑up bill‑of‑materials modeling; proprietary price‑erosion curves; and supply‑chain lead‑time surveys. The base year for our consolidated market view is 2025, with historical trend tracking from 2020–2025 and scenario forecasts through 2032. We quantify uncertainty across key inputs and present alternative outcomes to support capital allocation and contingency planning.
How to use this insight in 90 days
- CTOs: Reassess procurement pipelines and prioritize early vendor qualification for long‑lead components.
- CPOs: Renegotiate supplier contracts to incorporate flexible pricing and lead‑time commitments; pilot a mixed‑sourcing strategy.
- Product leaders: Accelerate proof‑of‑concepts for micro‑cable and multicore designs where thermal and density gains create customer adoption paths.
- Investors: Use our vendor scorecard and M&A heatmap to identify targets for platform consolidation or strategic roll‑ups.
PW Consulting’s Worldwide Active Optical Cable and Extender Market report delivers the granular decision‑support tools executives need to navigate 2026’s rapid evolution—without overreliance on single vendors or brittle supply chains. The release functions as a practical playbook for converting a fast‑growing market into long‑term competitive advantage.
To access the full report, including detailed segmentation breakdowns, vendor matrices, downloadable financial models and scenario workbooks, visit the official PW Consulting report page or contact our industry team for a briefing. The summary presented here is intended to surface strategic priorities and actionable frameworks; the full dataset and vendor‑level analytics are available exclusively in the complete publication.
For detailed analysis of this topic, please visit the official page: Worldwide Active Optical Cable and Extender Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com