

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cloud IDS/IPS Market to Reach USD 7,673.8 Million by 2032, Growing at a 15.2% CAGR

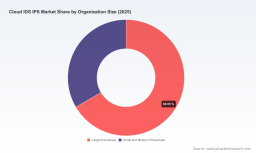
Worldwide Cloud IDS/IPS Market: Strategic Imperatives for Enterprise Decision-Making in 2026
PW Consulting’s latest market research on the Worldwide Cloud IDS/IPS Market offers a forward-looking roadmap for security, cloud, and infrastructure leaders planning investments through 2032. The study projects that the global market — measured on a USD Million basis — stood at approximately 2,850 (USD Million) in the base year 2025 and is expected to expand at a compound annual growth rate (CAGR) of 15.2% across the forecast window, reaching roughly 7,674 (USD Million) by 2032. For executives making 2026 budgetary and architecture choices, these aggregate dynamics translate into an urgent need to reconcile rapidly rising demand for cloud-native intrusion detection and prevention capabilities with operational cost pressures, supply-side consolidation, and evolving regulatory constraints.
Worldwide Cloud IDS IPS Market
Why this research matters to 2026 strategic choices
-
Timing: 2026 marks a transition point from experimentation to scale for many cloud IDS/IPS deployments. The market momentum our analysis captures signals that pilot projects should be evaluated against scalable architectures, automation, and measurable operational economics rather than feature checklists alone.
Worldwide Cloud IDS IPS Market -
Cost and capacity trade-offs: As cloud-native IDS/IPS moves from point solutions to platform-integrated services, decision-makers must weigh the economics of inline prevention versus out-of-band detection, factoring in rising hosting and energy costs across data centres.
Worldwide Cloud IDS IPS Market -
Vendor strategy: The vendor landscape is consolidating around a mix of large systems integrators, cloud providers, and security-native firms. Choosing partners that can offer both cloud-native telemetry integration and managed operational disciplines will materially reduce time-to-value.
Key market drivers and what they mean for investments
-
Cloud-native workload growth and east-west traffic visibility. As workloads migrate and microservice architectures proliferate, network-level threat surfaces change. Organizations must prioritize IDS/IPS solutions that provide contextualized, workload-aware detection and can be deployed without heavy network re-architecture.
-
Automation and AI-enabled rule management. Our research highlights that automation — including AI-driven rule tuning and managed rule groups — is becoming table-stakes. Security operations centers (SOCs) that embrace automated rule lifecycle and anomaly triage will see materially higher alert fidelity and lower mean time to remediation.
-
Energy and operational costs. The continued surge in data centre electricity demand — driven in part by AI and high-performance workloads — is raising the hosting economics for inline security. Security architects should incorporate energy and throughput cost modeling into total cost of ownership (TCO) evaluations for IDS/IPS deployments.
-
Regulatory friction and data sovereignty. Cross-border data flow restrictions and localization requirements are shaping deployment topology choices. Enterprises in regulated industries must plan for hybrid architectures that separate telemetry analysis from sensitive-data residency requirements.
Competitive landscape — pragmatic positioning of leading vendors
The market features a blend of cloud providers, traditional network-security vendors, and security-native players. Rather than presenting a ranking by revenue, our report examines capability clusters and go-to-market motions so buyers can align vendor selection with their operating model.
-
Cloud providers (AWS, Microsoft, Google Cloud): These firms embed detection capabilities into platform services and leverage massive telemetry footprints. Their advantage is native integration and scale; the trade-off is the need for multi-cloud orchestration when enterprises span providers.
-
Network and security incumbents (Cisco, Palo Alto Networks, Fortinet, Check Point): These vendors are extending firewalls and cloud security platforms with cloud-native IDS/IPS capabilities, emphasizing hybrid deployments and integration with existing networking stacks.
-
Security-native and endpoint-centric firms (CrowdStrike, Trend Micro, Zscaler, Sophos): These companies bring behavioral analytics, endpoint telemetry fusion, and managed service models. Their strength lies in detection sophistication and rapid incident response workflows.
-
Infrastructure and specialist vendors (Juniper, IBM Security): These providers focus on integration with SD-WAN, managed services, and enterprise-grade support for complex hybrid environments.
Recent vendor activity underscores two practical themes: deeper platform integration and managed rule automation. For example, Trend Micro’s 2025 partnership to deliver one-click managed rule groups in marketplace environments exemplifies how automation reduces operational friction for cloud IDS/IPS. Similarly, regional cloud and telecom providers are embedding firewall and IDS/IPS functions more directly into their stacks, reflecting demand for turnkey protection across both north-south and east-west flows.
Operational risks and regulatory dynamics to factor into 2026 plans
-
Certification pathways are shifting: The wind-down and transition of certain governmental approval programs have implications for how vendors pursue certifications and how buyers validate solutions for regulated environments. Procurement cycles may lengthen if certification windows are in flux.
-
Data localization is non-negotiable in some markets: The practical consequence for architecture is a preference for hybrid deployments and regional processing nodes that can host IDS/IPS workloads without violating sovereignty rules.
-
Energy cost volatility: Rising electricity demand from data centres (and projections of continued growth) will make deployment economics more sensitive to throughput efficiency and energy-optimized processing. Inline prevention strategies that significantly increase processing burden must be evaluated against energy-driven OPEX increases.
How to use this market research in procurement and architecture conversations
-
Define outcomes, not features: Use the report’s scenario-based TCO models and detection efficacy metrics to specify procurement outcomes (e.g., acceptable false-positive rate, time-to-detect, automated rule coverage) that map to business risk tolerances.
-
Stress-test hybrid and multi-cloud plans: Apply the vendor capability matrices and integration playbooks in the report to validate whether proposed solutions support consistent policy enforcement and telemetry correlation across providers.
-
Embed energy and operational costs into TCO: Leverage the included cost-model templates to compare deployment options on normalized energy and throughput bases, not just subscription pricing.
-
Prioritize managed automation: Where internal security operations are capacity-constrained, the report’s managed-service evaluation framework helps quantify the trade-offs between managed rule groups, one-click integrations, and in-house rule tuning.
Report contents — what PW Consulting delivers (practical, action-oriented)
-
Market sizing and trajectory: comprehensive topline projections through 2032 (aggregate market trajectory and CAGR), supporting scenario analyses for conservative, base, and aggressive adoption curves.
-
Vendor capability maps: pragmatic assessments of integration depth, detection techniques, managed services, and multi-cloud operability for the major public cloud, network-security, and security-native vendors.
-
Operational playbooks: templates for policy migration, rule lifecycle automation, and SOC playbooks tuned to cloud-native telemetry sources.
-
TCO and energy cost models: modular spreadsheets and sensitivity analyses to quantify the impact of rising data centre power consumption and throughput economics on IDS/IPS hosting choices.
-
Compliance and procurement guidance: step-by-step checklists addressing data residency, certification pathways, and procurement clauses that accelerate vendor evaluation in regulated sectors.
-
Executive dashboards and decision matrices: concise tools to support board-level investment sign-offs and business case prioritization.
Strategic recommendations for 2026
-
Accelerate investments that reduce manual rule management through automation and marketplace integrations; time-to-protection is now a competitive differentiator.
-
Design for hybrid resilience: enforce detection and prevention policies close to workloads while ensuring telemetry aggregation complies with sovereignty requirements.
-
Quantify energy sensitivity: include energy and throughput scenarios in any TCO comparison, particularly for inline prevention technologies that materially increase processing workloads.
-
Favor partners that offer platform integration and managed operations; this reduces operational risk and shortens the path from deployment to effective threat prevention.
Next steps
PW Consulting’s full Worldwide Cloud IDS/IPS Market report provides the detailed segment-level analysis, regional forecasts, and vendor scorecards that CIOs, CISOs, and procurement leads need to finalize 2026 budgets and multi-year roadmaps. This release intentionally highlights the strategic contours and operational levers while reserving the granular segmentation and proprietary scoring matrices for the full report — available through our research portal.
Contact PW Consulting to schedule a bespoke briefing where our analysts will walk your team through tailored scenarios, rapid TCO comparisons, and vendor shortlists aligned to your cloud topology and regulatory footprint.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud IDS IPS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com