

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Tasigna Market to Contract at -11.45% CAGR, Falling from USD 1,550 Million in 2025 to USD 660 Million by 2032

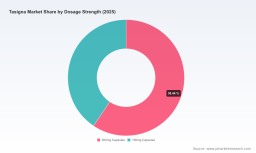
Worldwide Tasigna (nilotinib) Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Tasigna market is designed as an operational playbook for executives, portfolio strategists, investors, and payer teams who must make consequential decisions in 2026. Anchored to a 2025 base year and projecting through 2032, the analysis combines a rigorous historical reconstruction (2020–2025) with scenario-driven forecasts. The market is entering a structural contraction phase: total market value fell from approximately USD 2.0 billion in 2020 to USD 1.55 billion in 2025 and is projected to decline further under our baseline scenarios, reaching an estimated USD 660 million by 2032, driven by an expected compound annual decline of roughly 11.45% across the 2026–2032 forecast window. This release frames the strategic implications of that transition without disclosing the granular segmentation data reserved for the full report.
Worldwide Tasigna Market
Executive summary — why this matters in 2026
Tasigna’s market is no longer dominated solely by clinical choice—structural commercial forces increasingly determine outcomes. Patent expiries and generic entrants have re-ordered pricing, reimbursement, and channel dynamics, compressing addressable revenues for originators and redirecting incentives across stakeholders. For leadership teams assessing R&D prioritization, lifecycle spend, go-to-market investments, or potential M&A, the timing and magnitude of revenue contraction make 2026 a pivotal inflection year for decisions that will reverberate through the decade.
Worldwide Tasigna Market
Core signals shaping the market
- Commercial erosion is measurable and persistent. Historical market sizing shows a clear downward trajectory in total market revenue from 2020 through 2025. Our modeling indicates continued contraction under most plausible scenarios absent material changes in clinical practice, regulatory reopening, or new label expansions.
- Patent and generic dynamics have changed the competitive baseline. The key compound patent lapsed in the U.S. in March 2023, and generic versions entered major markets shortly thereafter. The originator has already reported meaningful top-line pressure; publicly reported figures indicate a notable decline in branded net sales following the onset of generic competition.
- Payer and channel pressures are intensifying. Reimbursement adaptations—including shifts to average sales price and formulary management under programs such as Medicare Part D—have accelerated price erosion for branded supply, while tendering and preferred contracting have amplified unit-level margin compression in several markets.
- Clinical and safety considerations remain material to adoption and prescribing patterns. Tasigna’s risk profile, including boxed safety warnings for cardiac events, underscores that clinical stewardship and monitoring regimes will continue to shape switching behavior and utilization, especially where payers and hospitals tighten access.
Competitive landscape — concentrated, but contested
The Tasigna market remains highly concentrated at the top: a small set of firms continue to command the overwhelming share of remaining branded and generic volumes. Our concentration metrics show that the combined share of the three largest suppliers remains above 90%, with the top five firms covering over 96% of market activity—a concentration level that creates both strategic inevitability and opportunity. Novartis, as the originator and global marketer of branded Tasigna, remains central to competitive dynamics, but generic entrants (notably immediate first movers in key markets) have reconfigured price and access levers.
Worldwide Tasigna Market
Recent developments illustrate this shift: a major generic manufacturer launched approved generic nilotinib products in the U.S. market following patent expiry, and Novartis publicly disclosed a significant decline in Tasigna sales following the entry of generics. These moves have accelerated payer-led substitution, incentivized broader use of lower-cost alternatives, and increased the importance of non-price differentiation.
What the full report delivers — practical, actionable modules
The PW Consulting report is designed as a workbench for decision-makers rather than an academic monograph. Its primary deliverables include:
- Transparent market-sizing and forecasting methodology, with reconciled historical data (2020–2025), scenario construction for 2026–2032, and sensitivity testing against key variables such as generic uptake speed, pricing erosion rates, and changes in prescribing guidelines.
- Competitive playbooks and benchmarking: detailed dossiers on incumbent and emerging suppliers, their commercial strategies, biosimilar/generic entry sequencing, and identified strengths-to-threat matrices for originator and follower firms.
- Regulatory and reimbursement risk matrix: jurisdiction-specific impact assessments, pathway timelines, and contingency plans for accelerated genericization, formulary delisting risk, and coverage-policy shifts.
- Clinical and safety landscape: synthesis of label changes, black-box safety considerations that influence market access, and recommended risk mitigation and compliance investments to sustain utilization where clinically justified.
- Channel and pricing playbooks: tactics for preserving share through contracting, tender strategies, specialty-distribution optimization, and payer-engagement templates aligned to the new competitive baseline.
- Operational readiness checklist: manufacturing capacity and supply-chain adaptations for firms repositioning to competitive price points, and factory-repurposing options for companies transitioning away from high-volume nilotinib production.
- Deal and portfolio guidance: valuation frameworks for M&A and licensing transactions in a contracting market, including multiples stress-tested against the forecast decline trajectory and scenarios where upside is possible (e.g., label expansion or new formulations).
Actionable recommendations for 2026 — prioritize decisively
- Reallocate lifecycle investment with discipline. Firms should triage near-term spend: prioritize actions that directly protect clinical continuity and differentiated access (for example, adherence programs tied to safety monitoring) while deferring lower-return promotional activities.
- Deploy a tiered generic-defense strategy. Where legal recourse or supply agreements can materially delay or blunt generic penetration, pursue those options; where not, pivot quickly to differentiated support services and authorized-generic approaches that preserve net revenue.
- Target payer negotiations around outcomes and monitoring. Rather than competing only on price, originators should emphasize packages that reduce total cost of care—structured monitoring programs, bundled service offerings, and data-sharing arrangements that mitigate safety-related hospitalizations.
- Optimize channel mix and specialty distribution. With unit margins compressing, channel economics matter. Reassess distribution partners, rebates, and co-pay assistance programs to align with a lower-price environment while safeguarding patient access.
- Revisit portfolio strategy and R&D cadence. Given the contraction trajectory, prioritize indications and assets where clinical differentiation can justify premium pricing, and consider redeploying resources into adjacent molecules or modalities with better growth prospects.
- Prepare the supply chain for volume declines. Rationalize capacity to avoid excess fixed-cost burdens, evaluate contract manufacturing partnerships, and pursue cost-to-serve reductions without compromising product quality or regulatory compliance.
- Use real-world evidence as a lever. Invest in post-marketing evidence programs that demonstrate value in routine care settings—these data can be decisive in securing formulary positioning in tightly contested payer markets.
- Stress-test M&A and licensing options now. With valuations contracting in parallel with revenues, 2026 may offer attractive acquisition windows for strategic assets; however, models must incorporate the secular decline reflected in our forecast scenarios.
How to read and apply the scenarios
Our scenario framework is constructed to help executives run fast “what-if” analyses against realistic inflection points: a base-case reflecting continuation of current generic uptake and reimbursement trends; an accelerated-case driven by rapid substitution and tendering pressure; and a resilient-case in which clinical differentiation or favorable policy interventions slow down erosion. Each scenario is accompanied by clearly articulated trigger events, financial sensitivities, and tactical playbooks mapped to short-, medium-, and long-term actions. The scenarios are designed to feed capital allocation, commercial planning, and legal/market-access decisions in the critical 12–24 month window starting in 2026.
Who should use this report
- Originator pharmaceutical teams (brand strategy, market access, commercial operations)
- Generic and biosimilar manufacturers evaluating entry timings and pricing strategies
- Private equity and strategic investors assessing valuation and deal structures
- Payer and provider systems optimizing formularies and care pathways
- Consultancies and legal advisors supporting lifecycle and litigation strategy
Final note — depth without compromise, detail behind the portal
This public summary is intentionally structured as a strategic “preview”: it explains the directional forces, the forecasted magnitude of change at the market level, and the major levers available to stakeholders—while preserving the granular segmentation, jurisdictional breakdowns, and proprietary scenario tables that comprise the transaction-grade intelligence reserved for the full report. For teams that need executable playbooks, precise market slices, and downloadable model files to incorporate into board-level decision-making, the complete PW Consulting report contains the full dataset, methodological appendices, and customizable forecasting templates.
To secure the full analysis and access the workbook and playbooks that operationalize these recommendations for 2026, consult PW Consulting’s Worldwide Tasigna Market report page or contact our industry practice team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Tasigna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com