

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Metal Cutting Gas Market Set to Reach USD 7,008.51 Million by 2032, Expanding at a 5.4% CAGR

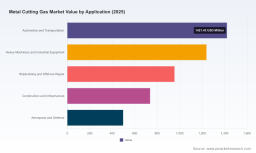
Worldwide Metal Cutting Gas Market: Strategic Outlook for 2026 Decision‑Making
PW Consulting's latest market study on the Worldwide Metal Cutting Gas Market delivers a focused, decision‑grade view for executives planning capital allocation, procurement strategies, and M&A activity in 2026. Built on a 2020–2025 historical foundation with 2025 as the base year and a 2026–2032 forecast horizon, our model projects steady expansion at a compound annual growth rate (CAGR) of 5.4%. The total market reached roughly USD 4.85 billion in 2025 and our scenario worktracks recovery and selective acceleration across the forecast window. This release is a strategic preview: we surface the analytic logic, actionable implications, and competitive currents while reserving the full, segment‑level tables and vendor‑score matrices for report subscribers.
Worldwide Metal Cutting Gas Market
Why this matters for 2026
- Metal cutting gases remain a small but strategically visible cost pool for fabricators, shipyards, OEMs, and MRO providers. Even mid single‑digit shifts in price or substitution patterns materially affect unit economics of fabrications and repairs.
- Supply‑side signals—feedstock prices, regulatory tightening for hazardous emissions, and transportation safety rules—are converging in 2026 to create both procurement risk and pockets of margin opportunity.
- Industry concentration is meaningful: our concentration metrics indicate a moderately consolidated supplier landscape, with roughly half the market controlled by the five largest providers. That structure favours tier‑one vendors on long‑term contracts but leaves room for selective regional winners and technology disruptors.
Market performance and near‑term outlook
Following pandemic volatility, the metal cutting gas market stabilized through 2023–2025 and reached an estimated USD 4.85 billion in 2025. Our base case projects continued growth in 2026 and beyond, consistent with a 5.4% CAGR for 2026–2032 driven by industrial restart cycles, infrastructure spending, and steady demand from transport, heavy equipment, and energy sectors. The forecast embeds alternative scenarios (conservative, base, upside) that reflect different assumptions on raw material inflation, tariff impacts, and capital intensity across fabricating industries.
Worldwide Metal Cutting Gas Market
Practical implication: companies should treat 2026 as a planning year for hedging and operational changes rather than a period for reactionary contract resets. Tactical actions taken now—contract structuring, feedstock hedges, and supplier profiling—will lock in cost differentials through much of the forecast.
Worldwide Metal Cutting Gas Market
Key dynamics shaping 2026 decisions
- Feedstock and price volatility : Acetylene and LPG‑based feedstocks showed regionally divergent price moves into 2026, reflecting calcium carbide supply cycles, LNG feedstock flows, and varying downstream demand. These moves increase the value of flexible fuel strategies and blended formulations.
- Regulatory and transport oversight : U.S. and international regulators are tightening emission and transport rules affecting integrated steel and metal fabrication operations. For example, U.S. NESHAP standards and PHMSA hazardous materials oversight raise compliance costs for large fabricators and carriers and favor suppliers who can demonstrate robust safety and emissions controls.
- Trade policy and tariffs : Recent restructuring of import measures on finished metal products increases input cost volatility for domestic fabricators and can shift demand among regional suppliers. Procurement teams should model tariff pass‑through and consider multi‑sourcing to mitigate single‑market exposures.
- Technology and substitution pressure : Growth in high‑precision plasma and laser cutting, together with specialty fuel blends, is changing the buyer value equation. Fabricators invest to reduce oxygen consumption and improve cut quality, creating opportunities for vendors that bundle gases with process optimization services.
Competitive landscape — leaders, challengers, and regional plays
The market is characterized by global industrial gas majors and strong regional energy and distributor players. Leading industrial gas companies bring scale, logistics networks, and product portfolios that span oxy‑fuel, plasma, and specialty blends; they are well positioned to capture long‑term, large‑volume contracts and to offer integrated cutting solutions. Regional energy companies and national oil companies leverage local feedstock advantage and distribution reach to compete on price and service for mid‑market customers.
- Global majors (examples): Providers with integrated global operations offer advanced gas formulations, contracted logistics, and equipment integration capabilities that are attractive to large fabricators and OEMs. Their strengths lie in product breadth, global delivery platforms, and the ability to underwrite multi‑year supply agreements.
- National and regional players : State or regionally‑anchored suppliers can be highly competitive on price and responsiveness, especially where feedstock availability (e.g., LPG or local acetylene production) is favorable. They can also act as acquisition targets for global players seeking footprint expansion.
- Equipment and consumable specialists : Companies supplying cutting equipment and consumables remain critical partners. Their co‑selling and technology bundling strategies (e.g., delivering optimized gas + nozzle + process parameters) are a differentiator in high‑value segments.
For procurement and strategy teams, the key takeaway is to map vendor capabilities not only to price but to delivery reliability, emissions compliance, and process optimization services. Our market concentration indicators suggest room for both consolidation and targeted bolt‑on M&A: global players will continue to defend large accounts while regional champions may be attractive targets for roll‑ups focused on logistics and feedstock arbitrage.
What the PW Consulting report contains (practical deliverables)
To support 2026 decision cycles, the full report provides a suite of practical tools and templates designed for operators, procurement leaders, and corporate strategists. Highlights include:
- Proprietary demand model and scenario suite for 2026–2032, enabling stress‑testing of procurement strategies under varying feedstock and regulatory paths.
- Supplier scorecards and a negotiated contract playbook (pricing levers, service KPIs, escalation mechanics) that procurement teams can adapt to tender processes.
- Cost‑per‑cut and total cost of ownership frameworks that incorporate fuel mix, oxygen consumption, consumable life, and labor—designed to compare oxy‑fuel, plasma, and laser options on a consistent basis.
- Regulatory risk matrix tying NESHAP, transport rules, and emerging regional emission requirements to probable compliance costs and operational adaptations.
- Scenario‑based M&A use cases and valuation heuristics for acquiring regional suppliers or forming JV distribution platforms.
- Supply chain resilience checklists and supplier due‑diligence templates emphasizing safety, leak detection, and end‑to‑end logistics performance.
Note: detailed tables breaking performance down by region, gas type, and application are intentionally reserved for the full report to preserve the analytic value of our primary research and to facilitate tailored client briefings.
Actionable recommendations for executives in 2026
- Procurement playbook : Implement multi‑tiered contracts with optionality—fixed minimum volumes, indexed incremental pricing, and embedded cost pass‑through clauses tied to recognised feedstock indices. Use our scenario model to size hedges for 12–24 month windows.
- Feedstock diversification : Where feasible, qualify alternative fuels and specialty blends that reduce oxygen consumption and exposure to volatile acetylene markets. Pilot programs for blended formulations should be initiated in Q1–Q2 2026 with defined KPIs.
- Compliance and safety upgrades : Prioritise supplier partners who can demonstrate compliance with tighter emission and transport regimes (e.g., NESHAP and PHMSA expectations). Investing in leak detection and safety training yields immediate insurance and operational benefits.
- CapEx and process optimization : For high‑volume fabricators, evaluate capital investments in plasma/laser substitution where lifecycle costs are attractive. Use our cost‑per‑cut model to justify capex versus long‑term fuel purchase commitments.
- M&A and partnerships : Target regional providers with strong logistics and feedstock access for bolt‑on acquisitions; pursue JV structures where regulatory or market entry barriers exist.
- Commercial differentiation : Suppliers should bundle gas supply with process consulting and digital monitoring; buyers should require these capabilities in RFPs to capture value beyond price.
How to apply this intelligence
Use the report to underpin three immediate 2026 workstreams: (1) procurement renegotiation—prepare indexed contract templates and shortlist compliant suppliers; (2) capital planning—run our cost‑per‑cut scenarios before committing to new cutting technology; (3) M&A screening—apply our valuation heuristics to shortlist regional targets.
PW Consulting’s research is intentionally designed as a practical toolkit: models that feed spreadsheets, templates that slot into RFPs, and a regulatory matrix that can be dropped into compliance planning. The full dataset and segment‑level analytics—critical for precise tendering and valuation—are available through the report subscription and tailored client briefings.
Next steps
- If you are a buyer: use the preview above to prioritise which facilities and product lines to pilot fuel diversification in the first half of 2026.
- If you are a supplier: benchmark your offerings against the criteria in our vendor scorecard and prepare bundled commercial proposals for large OEMs and shipyards.
- If you are an investor: request our M&A appendix for target lists, valuation drivers, and sensitivity to feedstock price scenarios.
For access to the full Worldwide Metal Cutting Gas Market report—including our proprietary models, full regional and application breakdowns, and vendor scorecards—visit the PW Consulting report page or contact our market intelligence team for a tailored briefing. Our clients use these insights to turn 2026 uncertainty into strategic advantage.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Worldwide Metal Cutting Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com