

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Elemental Fluorine Market to Grow from USD 928.5 Million in 2025 to USD 1,412.8 Million by 2032 at a 6.18% CAGR — Asia Pacific Leads with USD 443.2 Million, Top‑3 Firms Hold 64.2%

Worldwide Elemental Fluorine Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Elemental Fluorine Market delivers a focused strategic playbook for executives planning through 2026 and beyond. The market reached approximately USD 928.5 Million in our base year (2025) and, under our central forecast, expands at a compound annual growth rate of 6.18% through 2032 — reaching roughly USD 1,412.8 Million by the end of the forecast window. These headline metrics underline a market that is growing steadily but remains narrow, concentrated, and highly sensitive to upstream raw materials, regulatory shifts, and episodic supply disruptions.
Worldwide Elemental Fluorine Market
Why this report matters to 2026 corporate strategy
-
Supply security is a strategic differentiator. For semiconductor manufacturers, specialty chemicals producers, and nuclear fuel processors, uninterrupted access to high-purity elemental fluorine (F2) is increasingly a business-critical factor.
Worldwide Elemental Fluorine Market -
Price and input-cost risk are material. Producers and buyers must quantify exposure to fluorspar and anhydrous hydrogen fluoride (HF) volatility, and determine whether costs can be passed through or absorbed within product architectures.
Worldwide Elemental Fluorine Market -
Regulatory complexity is non‑negotiable. Transport, classification and chemical authorization regimes materially affect logistics, inventory strategy, and capex timing for greenfield production assets.
-
Concentration and disruption risk create deal opportunities. Market concentration implies that strategic moves by one major supplier can cascade across the value chain — presenting both risk and consolidation opportunities for investors and incumbents.
Market dynamics that will shape boardroom decisions in 2026
-
Feedstock and cost pressure: Spot and contract prices for fluorspar and HF rose meaningfully in recent years, increasing production unit costs for F2 and squeezing margins for less integrated suppliers. Our cost‑curve analysis quantifies the sensitivity of operating margins to HF feedstock and offers hedging thresholds for buyers.
-
Regulatory and logistics constraints: Elemental fluorine is governed by hazardous‑materials transport regimes and chemical authorization systems that drive higher compliance costs and add operational friction. Firms must factor cylinder approvals, cross‑border transport restrictions, and regional authorization timelines into supply-chain design.
-
Supplier concentration and systemic risk: A highly concentrated supply base means that the top global producers exert significant pricing and capacity influence. That structure heightens the impact of site‑level incidents, force majeure events, and planned maintenance on global availability.
-
Geopolitical and trade policy influence: Export controls and raw‑material policy in key producing countries have created trade flow uncertainty. Buyers should expect episodic disruptions tied to policy shifts rather than smooth, gradual price trends.
-
End‑market demand drivers: Semiconductor roadmap inflections, new battery materials, and specialty fluorinated organic intermediates are the primary growth levers. These demand vectors differ in purity needs and contract structures — a critical point when aligning supplier capabilities with product requirements.
What PW Consulting’s report delivers — practical, decision‑ready content
-
An audited historical series (2020–2025) and a granular 2026–2032 forecast built on bottom‑up demand drivers and supply‑side constraints.
-
Integrated cost‑curve models that allow users to run sensitivity scenarios on key inputs (HF and fluorspar spot and contract prices) to assess margin break‑even points for producers and price thresholds for industrial buyers.
-
Supply‑chain risk maps and trade‑flow analytics highlighting geographic chokepoints, modal constraints, and cylinder/transport bottlenecks under current regulatory regimes.
-
Regulatory risk matrix covering transport classifications, regional chemical authorization regimes, and anticipated compliance timelines — with practical mitigation playbooks.
-
Company-level intelligence and strategic profiles of the major producers, including capability matrices, single‑site exposures, and M&A vigilance indicators.
-
Scenario toolset: baseline growth, supply‑constraint shock, and accelerated‑demand scenarios tied to semiconductor or battery buildouts, providing probabilistic outcomes for planning and contingency budgets.
-
Procurer playbooks: contracting templates, force‑majeure language recommendations, inventory policy guidance, and structured offtake strategies for mid‑ to long‑term procurement.
Competitive landscape: who shapes supply and why it matters
The market’s structure is dominated by a small set of specialized producers whose technological capabilities, geographic footprint, and integration with upstream or downstream value chains determine both near‑term availability and strategic negotiating power. Our report provides focused profiles of the leading companies and assesses their strategic postures:
-
Air Products and Chemicals, Inc. (Lehigh Valley, Pennsylvania, USA — www.airproducts.com): A leader in supplying ultra‑high‑purity F2 for semiconductor etching and specialty synthesis. Their scale in ultra‑pure gases and customer‑proximate logistics make them a preferred partner for high‑reliability buyers.
-
Solvay SA (Brussels, Belgium — www.solvay.com): A global electrolysis‑based producer with integrated HF capabilities. Solvay’s operations illustrate how single‑site incidents can ripple through supply chains; a force majeure event in mid‑2022 demonstrates the market sensitivity to plant outages.
-
Pelchem SOC Ltd (Pelindaba, South Africa — www.pelchem.com): One of the world’s dedicated F2 producers with specialized capacity for enrichment and pharmaceutical intermediates. Their operational cadence and restart history are indicative of the sector’s maintenance‑driven availability profile.
-
Kanto Denka Kogyo Co., Ltd. (Tokyo, Japan — www.kanto-denka.co.jp): Specialist in high‑purity F2 for electronics and advanced materials, offering capability differentiation that supports premium pricing in electronics applications.
-
Stella Chemifa Corporation (Osaka, Japan — www.stella-chemifa.co.jp): Focused on F2 and fluorinated compounds for semiconductor cleaning and emerging battery materials, representing the supplier segment most closely tied to fab and battery‑materials demand growth.
Our competitive concentration metrics show that the top three suppliers account for roughly two‑thirds of market share, and the top five capture close to four‑fifths of the market — a structural reality that concentrates both pricing power and disruption risk among a few players. For executive teams, this underscores the importance of counterparty due diligence and strategic redundancy in sourcing.
Actionable strategic recommendations for 2026
-
For downstream buyers: Secure staged offtake agreements with price‑escalator protections tied to transparent HF indices; include explicit contingency commitments for emergency supply; and co‑invest in upstream resilience where supply is mission‑critical.
-
For producers: Evaluate vertical integration into HF feedstocks or fluorspar supply agreements; prioritize redundancy for single‑site critical assets; and develop modular, rapidly commissionable capacity options to capitalize on premium shortages.
-
For investors: Target bolt‑on assets that add feedstock security or geographic diversification, and prioritize targets with clean regulatory records and multi‑market customer bases to mitigate demand shocks.
-
For policy and compliance teams: Proactively engage with regulators on transport and authorization timelines, and adopt compliance workflows that shorten lead times for cross‑border moves and cylinder certifications.
-
Operational risk monitoring: Track a short list of early‑warning indicators we identify — spot HF prices, producer maintenance calendars, export‑policy announcements in key producing countries, and reported force‑majeure incidents — to trigger contingency protocols.
Using this report as a decision‑support asset
PW Consulting’s study is engineered to be more than a read‑only market narrative. It includes interactive models and scenario engines that allow strategy teams to stress‑test procurement policies, evaluate capex timing, and model the financial impact of different supply‑shock scenarios on unit economics. For boards and executive committees preparing 2026 budgets, the report provides the data, risk maps, and tactical templates needed to translate market intelligence into executable plans.
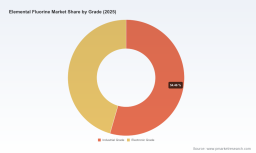
In keeping with the “trailer” principle, this release highlights the analytical depth and strategic relevance of our work while intentionally withholding the complete set of regional, application, and grade split tables that underpin our forecast. Detailed segmentation tables, price curves, and company‑level capacity maps are accessible in the full report and accompanying data packs — the materials that procurement, M&A, and strategy teams will use to operationalize the recommendations described above.
Next steps
-
Contact PW Consulting for a tailored briefing and model walkthrough to align our scenario outputs to your specific exposure.
-
Commission an executive workshop to translate the report’s recommendations into a 90‑day action plan for procurement, operations, and investor relations.
-
Download the full report to obtain the detailed segmentation and raw datasets required for contract negotiations, capex business cases, and regulatory filings.
Elemental fluorine’s role as a niche but strategically essential commodity means that 2026 planning cannot be deferred. Companies that translate the market’s structural realities into contractual certainty, upstream resilience, and regulatory readiness will capture disproportionate advantage. PW Consulting’s Worldwide Elemental Fluorine Market study is designed to be the operational intelligence that makes that advantage real.
For detailed analysis of this topic, please visit the official page: Worldwide Elemental Fluorine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com