

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Rugged Servers Market to Grow at a 7.4% CAGR Through 2032

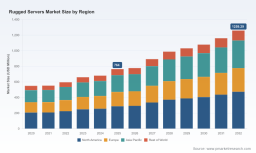
PW Consulting: Strategic Brief — Worldwide Rugged Servers Market Outlook and the 2026 Decision Playbook
As organisations accelerate edge compute deployments and defence procurements adapt to renewed great-power competition, rugged servers have moved from niche equipment to a strategic infrastructure category. PW Consulting's new Worldwide Rugged Servers Market report (base year 2025, historical coverage 2020–2025, forecast 2026–2032) translates market dynamics into executable guidance for 2026 planning cycles. Our analysis shows the global rugged servers market expanding at a 7.4% CAGR across the forecast window, rising from roughly USD 764 million in 2025 to an anticipated USD 1.26 billion by 2032. This brief outlines the report’s practical value, the competitive contours decision-makers must track, and the regulatory and energy considerations that will shape procurement and product strategy next year.
Worldwide Rugged Servers Market
Why this report matters to C-suite and build/buy decision-makers in 2026
-
Investment prioritisation: The report isolates the economic and operational drivers that justify capital allocation into ruggedised compute — from mission-critical defence systems to industrial edge automation — enabling CFOs and CTOs to rank initiatives by expected ROI under realistic energy and compliance constraints.
Worldwide Rugged Servers Market -
Product and platform roadmaps: Engineering and product leadership gain a clear view on where compute density, thermal tolerance, shock/vibration qualifications, and compute/accelerator balance must evolve to remain competitive across the forecast horizon.
Worldwide Rugged Servers Market -
M&A and partnership screening: For corporate development teams, the analysis highlights strategic gaps at the platform and services level that make acquisition targets attractive, and models how consolidation could change supplier leverage.
-
Supply chain and sourcing: The report provides decision-ready guidance on supplier diversification, in-country assembly trade-offs, and compliance-driven sourcing constraints that are especially relevant for defence and critical infrastructure buyers.
-
Procurement and RFP design: Procurement teams receive reproducible templates to include energy, lifecycle, and data sovereignty clauses in RFPs — moving beyond price-per-unit to a TCO and mission-assurance framework.
What the PW Consulting report delivers (practical toolkit)
-
A calibrated market model covering 2020–2025 historical performance and 2026–2032 forecasts, enabling scenario planning for conservative, baseline, and accelerated demand environments.
-
Decision matrices that map form-factor, processor class, and thermal/EMC qualifications to typical mission profiles — ready for use in product requirements documents.
-
A Total Cost of Ownership (TCO) and energy-sensitivity module that quantifies the operational importance of server-level efficiency when deployed in distributed edge sites with constrained power budgets.
-
Vendor scorecards and capability heatmaps combining product, certifications (e.g., environmental and EMI/EMC standards), manufacturing footprint, and aftermarket service offerings—configured to support supplier shortlists without exposing raw segmentation tables in this summary.
-
Compliance and data sovereignty playbooks, including recommended contract language and mitigations for transnational data access regimes that affect deployments of U.S.-based suppliers.
-
Commercial scenarios and playbooks for new entrants and incumbents: practical go-to-market tactics, pricing levers, and bundling opportunities (hardware + managed services) tailored for defence primes, telecom operators, and industrial integrators.
Market structure and competitive dynamics: what to watch in 2026
The rugged servers market demonstrates a moderate concentration profile. Leading vendors together control a meaningful portion of the market, but the sector remains open to disruption by specialised system integrators and component-level innovation. For corporate strategists and procurement leads, the competitive landscape can be understood in three layers: tier-one diversified defence/IT OEMs, specialised rugged-systems manufacturers, and adaptable industrial/embedded platforms providers.
-
Tier-one diversified OEMs: Established technology conglomerates with broad portfolio capabilities continue to leverage scale, channel reach, and integrated services to capture large enterprise and telecom deployments. Their strength lies in systems integration and global service footprints — important where lifecycle support, warranties, and rapid field replacement are decisive.
-
Specialised rugged-systems manufacturers: Companies focused exclusively on ruggedised compute bring deep MIL-standard experience, customisation agility, and faster qualification cycles for high-shock, maritime, and airborne environments. These vendors are favoured in mission-critical defence procurements where MIL-STD and MIL-S specifications are mandatory.
-
Embedded and industrial platforms providers: Firms originating from the embedded computing market are increasingly competitive at the edge, leveraging modern processor families and modular architectures to offer energy-efficient, high-density options for industrial automation and telecom edge racks.
Representative players across these layers include companies known for MIL-STD compliance and high-reliability servers, firms bringing high-density modular designs for constrained platforms, and industrial computing vendors integrating the latest processor families for energy-sensitive deployments. Recent product introductions and refreshes underscore how vendors are racing to combine compute density, thermal performance, and certified ruggedness to win next-generation contracts. Our full report contains vendor-level benchmarking, procurement scorecards, and a curated list of vendor strengths and weaknesses designed for shortlisting — the data that will directly inform RFP scoring in 2026.
Recent vendor moves and what they imply
-
Several suppliers have refreshed portfolios with higher compute density and extended operating-temperature ranges to support edge AI workloads — signalling that customers will increasingly value on-device inference capability rather than backhaul-centric models.
-
New product launches emphasise modularity and configurability, reducing lead times for bespoke defence configurations and enabling more predictable supply chains through configurable subassemblies.
-
Announcements from both specialist and large OEMs show a parallel push toward energy-efficient processor platforms, reflecting the broader market imperative to reduce site-level power consumption and cooling needs.
Regulatory, energy, and data-sovereignty headwinds
Three cross-cutting dynamics will materially affect procurement and product strategy in 2026:
-
Standards and qualification: Environmental and electromagnetic standards remain a gating factor. Qualification regimes (including maritime shock standards and MIL-STD families) impose design and test overhead that can lengthen time-to-contract and raise entry costs for new vendors.
-
Energy and operational costs: Data centre and edge power consumption continues to be a primary cost driver. Recent analyses show U.S. data centre electricity consumption in the order of hundreds of terawatt-hours annually, and global consumption nearing projected multi-hundred-TWh levels — a trend that directly impacts TCO models for edge-deployed rugged servers.
-
Data sovereignty and legal risk: Cross-border legal frameworks that permit compelled access to data held by certain national suppliers complicate sourcing decisions for governments and operators that require strict in-country control over mission data. These legal considerations are now standard items in supplier risk assessments.
Strategic takeaways for executives preparing 2026 plans
-
Shift procurement metrics from unit price to lifecycle assurance: require energy, availability, service response, and compliance metrics in contracts.
-
Invest in modularity and configurability: shorten qualification cycles by adopting modular subassemblies that map to common environmental profiles.
-
Prioritise supplier diversity with scenario-tested buffers: maintain dual-sourcing paths for critical boards, power/thermal subsystems, and connectors to mitigate geopolitical and logistics risks.
-
Embed data-sovereignty clauses where mission sensitivity warrants: consider in-country assembly or managed hosting to reduce legal and operational exposure.
-
Factor energy cost risk into product roadmaps: push development towards processors and architectures that maximise performance-per-watt for the most energy-constrained deployment profiles.
Next steps — where to get the full operational playbook
PW Consulting’s report is structured as a decision toolkit: reproducible TCO models, vendor scorecards, procurement templates, and scenario-driven market forecasts calibrated to support 2026 budget cycles. This summary surfaces the strategic contours and highlights the near-term implications for planners; the full report contains the granular vendor benchmarking, qualification checklists, and downloadable datasets you will need to operationalise these insights. To access the complete intelligence package, including the validated market model and procurement templates, visit our report page or contact PW Consulting’s industry desk for a tailored briefing.
PW Consulting — turning market intelligence into executable strategy for organisations that cannot afford to be second-best at the edge.
For detailed analysis of this topic, please visit the official page: Worldwide Rugged Servers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com