

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 4.51% CAGR in Worldwide Water Tube Industrial Boilers Market Through 2032

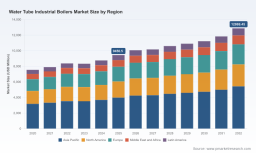
Worldwide Water Tube Industrial Boilers Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence brief provides a forward-looking strategic compass for executives, plant managers, and investors navigating the industrial water-tube boiler landscape in 2026. Drawing on a consistent historical dataset (2020–2025) and a seven-year forecast horizon (2026–2032), the study quantifies recent recovery and the medium-term growth runway while translating technical and regulatory shifts into actionable choices for capital allocation, procurement, and technology road‑maps.
Worldwide Water Tube Industrial Boilers Market
Market trajectory at a glance
- The market expanded from USD 7,550.0 Million in 2020 to USD 9,450.5 Million in 2025, reflecting resilient demand through supply‑chain disruptions and shifting fuel economics.
- PW Consulting projects the market to grow to USD 12,869.45 Million by 2032, reflecting a 4.51% compound annual growth rate across the 2026–2032 forecast window.
- Market concentration is moderate: the top three players account for roughly one‑third of global revenue, while the top five capture just under half — a structure that sustains local engineering specialists and supports continued consolidation and niche differentiation.
Why this matters for 2026 strategy
2026 is a junction year. Many asset owners approved decarbonization plans in prior cycles and are now executing capital projects, piloting low‑carbon fuels, or reassessing installed-capacity economics. The choices made this year — to retrofit, convert, repower, or replace — will set cost and emissions trajectories for decades. The report is designed to support those decisions by converting macro forecasts and evolving technical standards into procurement criteria, TCO models, and risk mitigants that are immediately usable by commercial and technical teams.
Worldwide Water Tube Industrial Boilers Market
Key decision levers addressed in the report
- Capital deployment: prioritization frameworks that balance short‑term plant efficiency gains against long‑term decarbonization readiness (hydrogen‑ready designs, oxy‑combustion compatibility).
- Procurement and supply resilience: supplier scorecards, lead‑time heatmaps, and vendor differentiation by modularization, spare‑parts inventory, and local service footprint.
- Fuel strategy: comparative economics and retrofit pathways for gas, oil, biomass, and blends, including regulatory tailwinds and grant programs that materially alter payback profiles.
- Operational risk and compliance: emissions control options, flue‑gas cleaning roadmaps, and scenario analyses to stress‑test projects against tightening regional regulations.
What the PW Consulting report delivers (practical, executable content)
- Concise executive dashboards: market size, growth scenarios, and sensitivity to fuel and steel cost movements for board-level briefings.
- Tactical procurement toolkit: RFx templates, technical acceptance checklists, warranty and service‑level negotiation playbooks, and a supplier due‑diligence matrix.
- Investment-grade modelling: capex and total cost of ownership (TCO) templates with customizable inputs for fuel mix, carbon price, availability, and ramp rates.
- Technology and retrofit playbooks: hydrogen‑readiness, oxy‑combustion accommodation, biomass conversions, and the retrofit engineering checklist for phased upgrades.
- M&A and partnership guidance: target screening criteria, valuation drivers for strategic buyers, and integration pitfalls for acquiring boiler OEMs or service specialists.
- Regulatory and incentive tracker: mapped by jurisdiction and linked to practical project implications and grant capture tactics.
- Risk matrix and mitigation strategies: supply chain bottlenecks, commodity volatility, skilled‑labour gaps, and accelerated depreciation considerations for tax planning.
Competitive landscape — who matters and why
The market combines global OEMs with deep engineering benches and a dispersed set of regional specialists. Below we summarize the strategic positioning of core vendors covered in the report; PW Consulting’s proprietary vendor scorecards provide deeper contract‑level comparisons in the full product.
Worldwide Water Tube Industrial Boilers Market
- Babcock & Wilcox (Akron, Ohio, USA) — Known for engineered water‑tube package boilers (FM, Stirling, Towerpak variants). Their strength lies in tailored solutions for power and process industries and long track records delivering reliability for demanding duty cycles.
- Cleaver‑Brooks (Thomasville, Georgia, USA) — Focuses on packaged watertube systems as part of integrated steam solutions. Their market appeal centers on system integration, energy‑efficiency retrofits, and aftermarket services.
- Miura Boiler Co., Ltd. (Osaka, Japan) — A specialist in modular, high‑efficiency boilers with a low‑NOx orientation. Miura’s modularity and fast startup characteristics are valuable where part‑load cycling and emissions constraints dominate.
- Indeck Power Equipment Company (Wheeling, Illinois, USA) — Offers a broad inventory of 'A', 'O', and modular 'D' type boilers for rapid deployment. Their distribution footprint is a strategic asset for projects needing compressed schedules.
- Hurst Boiler & Welding Co. (Coolidge, Georgia, USA) — Supplies engineered packaged units with a strong manufacturing base in the U.S. Their approach targets global industrial steam demand with robust engineering support.
- Unilux Advanced Manufacturing (Schenectady, NY, USA) — Positions on material quality and precision manufacturing (Evolv series). Their value proposition is reliability, long life‑cycle cost advantage, and fit for precise process applications.
- Victory Energy (USA) — Emphasizes efficiency and sustainability across industrial and institutional markets; competitive in retrofit projects and projects seeking integrated emissions reductions.
- Rentech Boiler Systems (Abilene, Texas, USA) — Specializes in rugged packaged systems for demanding industrial environments; appeals to heavy‑duty users and process industries.
- Thermax Limited (Pune, India) — Integrates boilers with energy & environment solutions; strategically positioned for emerging‑market industrialization and decarbonization financing packages.
- ZOZEN Boiler Co., Ltd. (Wuxi, China) — Produces SZS series units across fuel types, including biomass. Their cost‑competitive manufacturing and broad fuel compatibility make them a frequent choice for industrial steam rollouts.
- Bryan Boilers (Peru, Indiana, USA) — Offers flexible high‑efficiency solutions for commercial and industrial users; strong in applications that require packaged flexibility.
- Parker Boiler Co. (Los Angeles, CA, USA) — Brings water‑tube hot water and steam products emphasizing maintainability and reliability for long operational life.
- Babcock Wanson (Chevilly‑Larue, France) — Serves European process and manufacturing clients with a mix of water tube and other boiler technologies, often integrated with environmental controls.
Recent signals and market “noise” that should influence 2026 plans
- Decarbonization demonstrations and fuel conversions are accelerating: recent projects include oxy‑combustion demonstrators and full hydrogen conversions — tangible proof points that low‑carbon pathways are transitioning from R&D to commercial pilots.
- Biomass adoption is showing concrete traction in paper and packaging segments, supported by targeted public grants in some jurisdictions. For corporates with decarbonization targets, biomass and waste‑fuel options now sit in the feasible toolbox rather than being purely theoretical.
- Raw material inflation remains a constraint: hot‑rolled coil prices have shifted upward in early 2026 compared with the prior year, creating meaningful cost pressure on new units and spare‑parts procurement. This amplifies the value of procurement timing and forward buying strategies embedded in our TCO models.
- Exhibitions and vendor activity continue to reveal product roadmaps — from eco‑focused launches to modular, quickly deployable packaged units — signaling that vendors are competing on emissions profile, modularity, and service networks as much as on upfront price.
How to use this intelligence in boardroom and plant‑floor decisions
- Prioritize pilots this year: validate hydrogen‑ready combustion systems or biomass conversions on single‑line assets before broad rollouts. Our scenario models show pilot results materially reduce uncertainty for full‑scale CAPEX decisions.
- Lock in critical procurement levers: where spares or fabricated pressure parts have long lead times, use phased contracting and strategic inventory to avoid extended downtime risk.
- Embed emissions options into procurement specs: require modular upgrade paths (hydrogen burners, oxy‑compatibility, flue‑gas capture interfaces) to protect asset value against tightening regulations.
- Use the vendor scorecards to select partners not only on equipment price, but on lifecycle service economics—availability of local technicians, spare‑parts lead time, and retrofit experience are often the largest determinants of realized OPEX.
Report access and next steps
This preview demonstrates the type of decision‑grade analysis PW Consulting provides. The full Worldwide Water Tube Industrial Boilers Market report contains detailed segment and regional tables, vendor scorecards, downloadable TCO templates, RFx language, and scenario decks — all designed to accelerate funding approvals and shorten the time between decision and execution.
To obtain the complete dataset, granular segmental breakdowns, and the hands‑on toolkits referenced here, please visit the PW Consulting report landing page. For immediate advisory support — including bespoke TCO runs or procurement workshops timed to 2026 project pipelines — contact our industrial energy practice for a prioritized briefing.
PW Consulting: transforming market forecasts into executable industrial strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Water Tube Industrial Boilers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com