

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
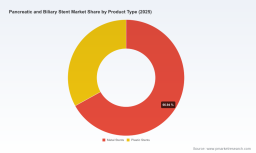
PW Consulting: Worldwide Pancreatic & Biliary Stent Market Poised to Reach USD 886.58 Million by 2032 at a 6.45% CAGR — Base Year 2025 Revenue USD 572.4 Million; Metal Stents Lead at USD 383.19 Million

Worldwide Pancreatic and Biliary Stent Market — Strategic Outlook for 2026: How PW Consulting’s New Report Shapes High‑stakes Decisions
The pancreatic and biliary stent market is at an inflection point. After a five‑year historical tracking window and a refreshed forecasting run, PW Consulting’s new Worldwide Pancreatic and Biliary Stent Market report projects continued growth through 2032, underpinned by steady procedure volumes, device innovation and shifting reimbursement and regulatory dynamics. Our base year is 2025, with the market recorded at USD 572.4 Million and a projected near‑term increase to USD 613.85 Million in 2026. Across the 2026–2032 forecast horizon PW Consulting models a compound annual growth rate (CAGR) of 6.45%—a robust trajectory that supports both defensive and offensive strategic postures for manufacturers, investors, and healthcare providers heading into 2026.
Worldwide Pancreatic and Biliary Stent Market
Why this report matters to 2026 corporate strategy
-
Capital allocation and M&A: The sector’s concentration metrics (CR3 and CR5 indicators) demonstrate material market power among leading OEMs. These dynamics influence valuation multiples, due‑diligence focus areas and the type of assets that create strategic fit — from complementary delivery systems to biodegradable polymers and niche distribution agreements.
Worldwide Pancreatic and Biliary Stent Market -
R&D and product prioritization: Our analysis distinguishes between incremental product enhancements (e.g., deliverability and anti‑migration features) and platform breakthrough opportunities (biodegradable stents, coated nitinol alloys). The report helps prioritize high‑ROI development pathways aligned with regulatory and reimbursement timelines.
Worldwide Pancreatic and Biliary Stent Market -
Regulatory and reimbursement timing: For companies planning US or EU launches in 2026, understanding the 510(k) pathway, sterility and packaging expectations, and outpatient reimbursement codes is essential for go‑to‑market sequencing and cash‑flow modelling.
-
Supply chain resilience: Nitinol and polymer supply dynamics—central to self‑expanding metal stents and plastic stents respectively—are modelled for price volatility and lead times, informing procurement strategies and potential backward integration decisions.
What’s inside the report — practical, executable analysis (not just high level)
-
Market sizing and trend validation: A transparent methodology that reconciles primary interviews, hospital procedure datasets, and device shipment analyses across 2020–2025 to produce a defensible 2026 baseline and 2026–2032 forecast scenarios.
-
Clinically informed demand drivers: Procedure mix analysis, ERCP utilization trends, KOL interviews and an assessment of how oncologic practice patterns and chronic pancreatitis pathways will influence device demand.
-
Regulatory playbook: Step‑by‑step guidance on the 510(k) pathway, sterility documentation expectations (including ISO 11607‑1 considerations), and strategic filing recommendations to minimize time‑to‑reimbursement.
-
Reimbursement mapping: Practical mapping of outpatient procedure codes and APCs affecting hospital economics for stent placement—critical for pricing strategy and hospital contracting.
-
Commercial execution toolbox: Segmented go‑to‑market options (direct, distributor, hybrid), channel economics, pricing scenarios and sample contracting terms for hospital systems and group purchasing organizations.
-
Supply chain diagnostics: Raw material exposure analysis (nitinol and polymer supply), manufacturing bottlenecks, packaging and sterilization capacity constraints, plus mitigation playbooks.
-
Competitive and M&A landscape: Strategic profiles and capability gap assessments for leading manufacturers, with playbooks for partnerships, licensing and bolt‑on acquisitions.
-
Scenario modelling suite: Base, upside and downside scenarios that stress test assumptions such as clinical uptake of biodegradable stents, pricing pressure from commoditization, and regulatory delays.
Market dynamics shaping 2026 strategy
Three structural forces will dominate near‑term decision making. First, clinical adoption is being reshaped by new device types: fully biodegradable stents are moving from concept to clinical use, evidenced by recent regulatory clearances and early US procedures. Second, materials science remains pivotal—self‑expanding metal stents continue to rely on nitinol for its shape‑memory and biocompatibility properties, while polyethylene and polyurethane remain common for plastic stents. Third, regulatory and reimbursement frameworks are exerting outsized influence on launch sequencing: biliary and pancreatic stents are regulated as Class II devices in the US, generally following a 510(k) clearance route, and ERCP procedures are commonly coded under CPT codes with specific APC payments in outpatient settings. Collectively, these forces determine not just unit demand but pricing power, margin corridors and the timeline to commercial scale.
Competitive landscape — implications for incumbents and challengers
The market is competitive but concentrated. A handful of multinational medtech firms have established portfolios spanning plastic and metal biliary stents, endoscopy platforms and complementary disposables, while a growing set of innovative small and mid‑sized firms target niche differentiation with biodegradable materials or unique delivery systems. Key industry participants profiled in the report include:
-
Boston Scientific Corporation — broadly diversified device portfolio and recent regulatory wins for improved plastic stents underscore a dual focus on product refinement and geographic rollout.
-
Cook Medical — entrenched ERCP‑compatible product set with a history of clinician‑focused iterative improvements; a resilient supply and clinician engagement model.
-
Olympus Corporation — platform reach and recent distribution agreements broaden access to proprietary prostheses, aligning endoscope OEM strength with third‑party stent offerings.
-
Medtronic Plc and CONMED Corporation — integrated GI endoscopy portfolios and channel strength in hospital systems that shape procurement dynamics.
-
Q3 Medical Devices and Medi‑Globe — notable recent regulatory milestones for biodegradable and conventional stents respectively; these approvals signal the practical arrival of alternative material strategies into the US market.
-
Abbott, BD and select emerging players — competing on niche clinical features, pricing and distribution agility, particularly in price‑sensitive or emerging markets.
For strategic planners, the competitive takeaway is clear: incumbent scale and channel control remain powerful, but targeted clinical differentiation (e.g., temporary biodegradable solutions, improved deliverability) paired with smart distribution partnerships can accelerate adoption and justify premium pricing in defined clinical pathways.
Recent developments investors and strategists can’t ignore
-
Regulatory momentum for biodegradable technology — multiple 510(k) clearances and the first US clinical procedures for compostable pancreatic stents have moved the technology category from “emerging” to “commercially available.”
-
Strategic distribution partnerships — agreements to distribute established prostheses internationally underscore the value of channel reach as a near‑term accelerant for new product adoption.
-
Ongoing regulatory expectations — sterility documentation and packaging standards are non‑negotiable for market entry and are front‑loaded cost drivers in launch plans.
Actionable recommendations for 2026
-
For OEMs: prioritize a dual‑track investment—sustain core SEMS and plastic stent improvements while allocating discrete R&D funding to biodegradable and anti‑biofouling coatings. Build regulatory dossiers early, aligning clinical endpoints to reimbursement pathways.
-
For investors and M&A teams: target assets that close capability gaps (delivery systems, biodegradable polymer expertise, or hospital service contracts) rather than chasing broad product portfolios that duplicate incumbent strengths.
-
For hospital procurement and GPOs: leverage the predictable coding environment to negotiate bundled pricing tied to total cost of care metrics, and run limited pilots for biodegradable stents to capture real‑world economics.
-
For startups: focus on clinical differentiation that can be proven in small, high‑quality registries; partner with established distribution players to accelerate market access and reduce capital burn.
-
Across the value chain: de‑risk nitinol and polymer exposure by qualifying multiple suppliers and considering vertical integration where economics justify it.
Why PW Consulting’s report is the strategic asset for your 2026 playbook
This report is built to be operational: a transparent historical dataset (2020–2025), a defensible 2026 base, and scenario‑driven projections through 2032 with a 6.45% CAGR. It combines primary clinical interviews, device shipment analytics and regulatory/reimbursement intelligence to produce pragmatic growth and risk mitigations strategies. To preserve the tactical value for clients executing market entry and competitive plays, we intentionally withhold certain granular segmentation figures in public summaries; the full dataset, interactive dashboards and downloadable model are available through the report’s source page.
Contact PW Consulting to obtain the complete report and the accompanying forecast model if you are planning product launches, M&A activity, or strategic investments in 2026. The decisions you make this year will determine who wins the next wave of adoption in a market shaped by materials innovation, regulatory clarity and shifting care pathways.
For detailed analysis of this topic, please visit the official page: Worldwide Pancreatic and Biliary Stent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com