

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Skin Care Products Tubes Market Set to Expand at a 5.45% CAGR

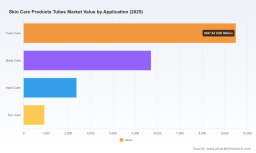
Worldwide Skin Care Products Tubes Market — Strategic Outlook for 2026: Executive Preview
PW Consulting’s latest market study on the Worldwide Skin Care Products Tubes market provides a strategic playbook for manufacturers, brand owners, private equity sponsors, and procurement leaders preparing for 2026 and beyond. Built on a 2025 base year and a 2026–2032 forecast horizon, the report combines empirical market-sizing with forward-looking scenario analysis to translate packaging trends into commercial imperatives. At the aggregate level, the global market was estimated at USD 18,502.21 Million in 2025 and is projected to reach USD 20,132.63 Million in 2026, with a compound annual growth rate (CAGR) of 5.45% across the 2026–2032 forecast period.
Worldwide Skin Care Products Tubes Market
What this report delivers — practical outputs for 2026 decision cycles
- Robust market sizing and forecasting. Transparent methodology, confidence intervals and an integrated topline model that links macro demand drivers to revenue outcomes across 2026–2032.
- Actionable segmentation logic. Material and application lenses, regional demand drivers and channel dynamics mapped to product development and sourcing strategies (detailed splits and downloadable tables are available in the full report).
- Competitive benchmarking. Deep profiles of leading tube and dispensing suppliers, supplier scorecards, manufacturing footprints and qualification timelines to accelerate supplier selection and dual-sourcing strategies.
- Procurement and cost-to-serve playbooks. Raw material sensitivity tools (including resin price scenarios), freight and tariff impact runs, and guidance on hedging, contract structures and nearshoring trade-offs.
- Sustainability compliance roadmap. Regulatory checklists and material substitution pathways aligned to EU recycled-content mandates and common retailer requirements.
- M&A and partnership scanner. Screening matrices for tuck-in candidates and strategic JV partners—prioritized against technical capabilities (e.g., airless systems), sustainability credentials and margin uplift potential.
- Interactive scenario models. User-configurable dashboards that stress-test outcomes under alternative trajectories for raw-material prices, regulatory tightening and premiumization velocity.
Why this matters for 2026 strategy — six implications for leaders
- Sustainability is now table stakes, not a differentiator. Regulatory momentum—most notably the EU’s requirement for recycled content and retailer sustainability commitments—means material choices must balance recyclability, barrier performance and cost. Companies that delay material transitions will face both compliance friction and increasingly onerous retailer acceptance processes.
- Innovation in dispensing unlocked premiumization. Airless and premium dispensing systems are driving margin expansion in the upper tiers of skincare. Brands that align formulation R&D with dispenser development can capture share at higher ASPs while improving shelf differentiation.
- Raw-material volatility has direct margin implications. HDPE and other resin price swings materially affect tube economics; our modelling uses recent benchmarks (for example, Q4 2025 HDPE averages reported in Europe) to quantify margin squeeze under multiple scenarios. Active hedging, multisourcing and gradual conversion to mono-material recyclables are effective mitigants.
- Fragmentation creates opportunity for consolidation and specialization. The market concentration metrics indicate a moderately fragmented landscape (CR3: 28.45%; CR5: 39.12%). This structure favors targeted M&A—particularly acquisitions that add barrier technology, mono-material know-how or regional manufacturing capacity to shorten lead times.
- Trade policy and tariffs are a supply-chain stressor. Persistent trade measures—such as ongoing applicable tariffs on certain imports—require that sourcing strategies incorporate landed-cost modelling and alternative manufacturing nodes. Nearshoring and regionalization of supply chains will accelerate for players with thin margins or critical time-to-market needs.
- Regulatory nuance affects product design. Specific compliance rules (for example, volume-triggered child-resistant requirements in certain jurisdictions) influence capex decisions and SKU rationalization; packaging design must be coordinated with regulatory and commercial teams early in the NPI cycle.
Competitive landscape — positioning the major players
The industry features a blend of global platform suppliers and regional specialists. Leading players offer distinct combinations of scale, technology and sustainability credentials:
Worldwide Skin Care Products Tubes Market
- Albéa Group (Gennevilliers, France) — A global leader in laminated, plastic and aluminum tubes with growing emphasis on mono-material recyclable formats. Recent product launches signal an intent to capture sustainability-led demand and to offer lower-friction retrofit options for existing production lines.
- Silgan Holdings Inc. (Stamford, CT, USA) — Through its dispensing division, Silgan combines tube supply with dispensing systems, which is attractive for brands seeking single-source suppliers that simplify qualification and inventory management.
- AptarGroup Inc. (Crystal Lake, IL, USA) — Known for airless and premium pump systems; Aptar’s visibility at industry shows underscores continued appetite from clean-beauty and premium skincare brands for advanced dispensing technologies.
- Amcor plc (Zurich, Switzerland) — Large flexible-packaging player with emphasis on recyclable and high-barrier solutions; well-positioned to deliver integrated packaging systems for brands looking to balance shelf life and sustainability.
- Berry Global Group Inc. (Evansville, IN, USA) — Offers a range of rigid and flexible tubes and has recently advanced its sustainability certifications—important for RFQs where third-party validation is required.
- Huhtamäki Oyj (Espoo, Finland) — Focused on mono-material laminate solutions and recyclability, attractive to European brands under progressive regulatory regimes.
- Virospack S.A. (Barcelona, Spain) — Specialist in premium airless systems; a natural collaborator for beauty houses pursuing high-end positioning.
- Intrapac International Pty Ltd (Keysborough, Australia) — Regional specialist with custom capabilities and fast turnaround—useful for Asia-Pacific and Australasian brand rollouts.
Recent vendor moves—from product launches of recyclable snap-top tubes to sustainability certifications and airless innovations—validate the twin market forces of sustainability and premiumization. For procurement and innovation teams, the strategic question is whether to partner with scale players for global consistency or to co-develop with specialists for differentiated shelf appeal.
Worldwide Skin Care Products Tubes Market
Scenario planning and sensitivity analysis — how to stress-test 2026 plans
- Sustainability acceleration scenario. Faster-than-expected uptake of recyclable mono-materials increases development lead-times and short-term costs but preserves access to major retail chains. Our scenario engine quantifies the investment pacing required to remain compliant and commercially competitive.
- Raw material shock scenario. Step-changes in resin pricing (modeled against recent HDPE benchmarks) require rapid supplier negotiation, substitution pathways and possible list-price adjustment strategies to protect margin.
- Trade disruption scenario. Tariff persistence and logistic constraints materially alter landed-cost optimization. The model supports breakpoint analysis to decide when to invest in regional capacity versus absorbing higher import costs.
Each scenario is paired with recommended tactical moves (procurement levers, NPI accelerators, capex trigger points) so leadership teams can translate market theory into near-term operational plans.
How to use this report in your 2026 planning cycle
- Integrate our topline models into your commercial planning and SKU rationalization exercises to align packaging spend with product-level margins.
- Use supplier scorecards to prioritize RFPs and to design dual-sourcing strategies that hedge raw-material and geopolitical risks.
- Adopt the sustainability roadmap as the baseline for 2026–2028 material transition planning and capital allocation.
- Deploy the M&A scanner to filter candidates that accelerate capability gaps (e.g., barrier tech, airless expertise, regional footprint).
- Leverage the regulatory checklist to align product development timelines with compliance milestones, reducing time-to-shelf risk.
Next steps and where to find the full intelligence
This executive preview highlights the strategic choices and operational levers that will determine winners in 2026. The full PW Consulting report contains the complete segmentation matrices, downloadable data tables, supplier scorecards, and the interactive scenario workbook referenced throughout this brief—information we intentionally reserve for the full release to ensure clients obtain the end-to-end models and proprietary assumptions needed to execute.
For immediate access to the complete dataset, supplier briefings, and our live forecasting dashboard, visit the PW Consulting report page or contact our advisory team to arrange a tailored briefing. As packaging ecosystems evolve rapidly, the cost of delayed strategic response is measurable; our clients use this research to convert regulatory and market signals into tangible advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Skin Care Products Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com