

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Automotive Optoelectronic Market Set to Grow at a 13.85% CAGR During 2026–2032

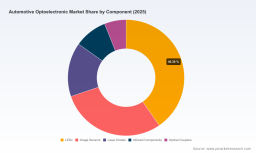
Worldwide Automotive Optoelectronic Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
PW Consulting’s latest market study on the Worldwide Automotive Optoelectronic Market synthesizes technological, regulatory, and supply-chain forces that will shape supplier and OEM strategy through 2032. After a period of rapid adoption between 2020 and 2025, the market entered 2026 on a steeper growth trajectory. Our base-year analysis shows the market roughly doubling over the first half of the decade; our forecast period (2026–2032) projects a compound annual growth rate (CAGR) of 13.85%, driving the industry toward a multibillion-dollar opportunity by the end of the decade. Market concentration remains meaningful: the top three firms control roughly 38.5% of industry revenues and the top five about 52.4%, underscoring both the presence of global champions and room for specialist entrants and regional champions.
Worldwide Automotive Optoelectronic Market
Why this report matters for 2026 decision-makers
- Timing: 2026 is a pivotal year for capital allocation. Component roadmaps (VCSELs, GaN LEDs, CMOS image sensors, and laser diodes) are moving from pilot to scaled production, meaning near-term investments will lock in technology and capacity for the early 2030s.
- Regulatory momentum: Safety and functional-safety mandates are forcing OEMs to standardize camera- and sensor-based systems. Understanding certification pathways, test vectors, and how they translate into supplier requirements is an immediate procurement and engineering priority.
- Supply resilience: Recent geopolitical and natural-disaster shocks exposed brittle supply chains for wafers and imaging sensors. Firms must balance cost, lead time, and geopolitical risk when selecting suppliers and deciding on localization vs. global sourcing.
High-level market dynamics
The market’s elevated growth is driven by convergence across lighting, sensing, and perception systems. Solid-state lighting for exterior and adaptive headlights continues to converge with active-sensing components used in ADAS and autonomous functions. Meanwhile, sensor performance improvements — driven by stacked CMOS architectures, global-shutter designs, and VCSEL-based illumination — are expanding both capability and cost-efficiency for safety-critical and comfort applications.
Worldwide Automotive Optoelectronic Market
These dynamics create a two-track competitive landscape: system integrators and Tier 1 suppliers who combine optics, electronics, and software to deliver turnkey modules; and component specialists who supply highly optimized LEDs, laser diodes, image sensors, and optical subsystems. Both tracks will compete on speed-to-certification, thermal and reliability performance, and the ability to provide system-level diagnostics that satisfy ISO 26262 requirements.
Worldwide Automotive Optoelectronic Market
Practical contents of the PW Consulting report
- Market sizing and forecasting: granular total-market forecast through 2032, scenario analyses (base, upside, downside) and sensitivity testing tied to regulatory and technology adoption timelines.
- Technology and product roadmaps: technology diffusion curves for VCSELs, GaN-on-Si LEDs, laser diodes for short- and mid-range LiDAR, and advances in stacked/global-shutter CMOS imaging.
- Supply-chain and manufacturing intelligence: capacity maps, fab location analysis, single-point-of-failure identification, and recommended dual-sourcing strategies aligned to CHIPS-era incentives and regionalization pressures.
- Commercial playbooks: go-to-market frameworks for suppliers (direct OEM, Tier-1 channel, co-development), pricing models, and contract structures that manage performance, certification, and long-tail warranty exposure.
- Regulatory and certification pathways: practical checklists for ISO 26262 compliance at different ASIL levels, EU General Safety Regulation implications, and testing requirements for sensor fusion systems.
- M&A and partnership targets: screened lists of acquisition candidates and technology partners across verticals, with integration risk scoring and expected time-to-value analyses.
- Financial models and KPIs: downloadable templates for NPV, payback, and CapEx/Opex scenarios tied to production ramp profiles and yield improvement programs.
Competitive landscape — who is shaping the next wave
The sector is populated by established semiconductor and optoelectronic players as well as LED specialists and system-focused component suppliers. Our competitor profiles combine commercial footprint, technical focus, and recent strategic moves to reveal where each firm is likely to double down or pivot.
- ams-OSRAM AG: Leading in automotive lighting and sensing, now advancing matrix laser sources for dynamic high-beam and projection-style functions. Recent product introductions reflect a deliberate push into high-resolution, multi-pixel light engines that enable new UX and safety features.
- Infineon Technologies AG: Focused on automotive-grade optoelectronic semiconductors, Infineon’s mix of detectors and IR emitters positions it as a bridge between power/logic control and sensing subsystems — an attractive profile for OEMs seeking integrated safety stacks.
- STMicroelectronics N.V.: Automotive-qualified image-sensor and ToF capabilities give ST a strong position in ADAS sensing. Recent launches underscore a focus on global-shutter performance critical to high-speed perception and robotics-style applications.
- Nichia Corporation: With leadership in high-power blue LEDs and laser diodes, Nichia is a strategic name to watch for short- to mid-range LiDAR emitters and high-efficiency headlight sources.
- Seoul Semiconductor Co., Ltd.: Innovations in compact high-density LED modules and digital micro-mirror-based adaptive headlights highlight the company’s role in next-generation smart beam systems.
- Lumileds, OmniVision, Sony, onsemi, ROHM, TE Connectivity, Everlight: Each name brings differentiated strengths — from high-power forward lighting, ultra-low-light image sensors, stacked CMOS innovation, VCSEL and driver integration, to optical connectors and interior sensing — creating an ecosystem of complementary and competitive offers.
Recent industry moves — from multi-pixel laser light sources to new global-shutter image sensors — demonstrate a healthy mix of incremental product improvement and step-change innovation. These trends favor players that can pair optics with high-bandwidth electronics and robust software stacks for perception and diagnostics.
Implications for purchasing, R&D and corporate strategy in 2026
- Balance scale with specialization: Given the current market concentration and accelerating demand, large OEMs and Tier 1s should hedge between partnering with scale players for commodity modules and investing with niche innovators for differentiation.
- Invest in certification early: Certification and ASIL compliance will be a gating factor for adoption. Early investment in verification infrastructure dramatically reduces time-to-production and warranty exposure.
- Supply-chain de-risking is non-negotiable: Build capacity buffers, diversify wafer and sensor sourcing, and evaluate near-shore options aligned to government incentives to reduce geopolitical exposure.
- Monetize software and systems: Value is shifting from pure hardware to perception stacks and diagnostics. Suppliers that offer firmware, calibration services, and lifecycle updates capture higher long-term margins.
- Use M&A selectively to close capability gaps: Targeted acquisitions in laser diodes, VCSELs, or imaging IP can shorten time-to-market for critical subsystems; our report scores targets by integration difficulty and expected synergies.
How PW Consulting’s report helps you act in 2026
This report is built to move beyond descriptive market commentary into prescriptive guidance. It provides playbooks for procurement teams, R&D roadmaps tied to yield and cost curves, and M&A screens aligned to realistic integration timelines and regulatory milestones. The deliverable includes scenario-driven financial models you can apply directly to investment, sourcing, or divestiture decisions.
Because the most sensitive commercial intelligence drives competitive advantage, this press release intentionally omits the granular regional and application-level splits that are available in the full report. For teams that need transaction-grade data, supplier-level scorecards, and downloadable financial templates that map to your product and manufacturing timelines, the full PW Consulting Worldwide Automotive Optoelectronic Market report provides the complete dataset and consultancy support.
Next steps
- Procurement leaders: request the supplier consolidation and dual-sourcing playbook to align 2026 RFx timelines with projected wafer and module capacity ramps.
- R&D and systems teams: use our technology-diffusion models to prioritize investments in VCSEL illumination, global-shutter imaging, or GaN-on-Si lighting technologies.
- Corporate and M&A teams: consult the acquisition target shortlist and integration-risk profiles before initiating diligence.
For access to the full dataset, supplier scorecards, and executable templates that underpin these strategic recommendations, visit the PW Consulting report page and contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Optoelectronic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com