

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Military Floating Bridge Market Valued at USD 845.67 Million in 2025, Set for Strong Expansion During 2026–2032

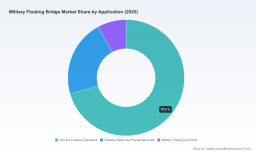
Worldwide Military Floating Bridge Market — Strategic Preview for 2026 Decision‑Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward‑looking briefing drawn from our new Worldwide Military Floating Bridge Market study. This executive preview synthesizes the forces reshaping capability acquisition for river crossing and wet‑gap mobility through 2032, and it explains why this niche — yet strategically critical — market deserves prioritization in 2026 planning cycles.
Worldwide Military Floating Bridge Market
Why this market matters in 2026
Military floating bridges are no longer a niche logistics concern: they are a force‑projection enabler that sits at the intersection of modernization, interoperability, and logistics resilience. Our analysis shows the global market had recovered and expanded through the mid‑2020s, with an approximate base market near USD 846 million in 2025 and a forecast compound annual growth rate of 5.12% across the 2026–2032 horizon. Under that trajectory, total market value approaches the USD 1.2 billion scale by 2032.
Worldwide Military Floating Bridge Market
For defense planners, procurement directors, and industrial strategists, the relevance is twofold. Operationally, modular floating bridging systems enable armored maneuver and logistics sustainment in complex terrain and degraded infrastructure. Strategically, demand is being driven by multilateral procurement programs, national modernization investments, and the increasing emphasis on expeditionary and dual‑use capabilities (disaster relief and humanitarian assistance alongside combat missions). That combination creates predictable procurement pipelines and program longevity — conditions that favor industrial investment, supplier consolidation, and capability upgrades.
Worldwide Military Floating Bridge Market
What our report delivers — practical, decision‑grade intelligence
- Comprehensive market sizing and scenario forecasts calibrated to defense procurement cycles and known program timelines, offering CFOs and program managers the time horizons needed to shape budget requests and production investments.
- Actionable procurement intelligence: an annotated pipeline of planned and announced programs, procurement milestones, and expected delivery windows tailored to 2026 decision points.
- Supplier capability matrices and technology scorecards that benchmark platform characteristics (deployment tempo, load classification performance, modularity, sustainment footprint), enabling rapid shortlisting of vendors against mission priorities.
- Supply‑chain risk and raw‑material sensitivity analyses, with mitigation playbooks for aluminum‑ and steel‑intensive platforms — a priority given prevailing material usage trends in modular pontoon and panel systems.
- Regulatory and interoperability checklists (including STANAG alignment) to reduce integration risk and accelerate coalition interoperability for NATO and partner force deployments.
- Investment and M&A advisory modules, including valuation heuristics for strategic acquisition targets, OEM‑tier partnerships, and diversification strategies for firms seeking to capitalize on stable defense demand.
Market dynamics you must factor into 2026 choices
Four dynamics dominate the near‑term strategic calculus:
- Programmatic demand and multilateral initiatives: Recent cooperative procurement projects underscore a trend toward joint investments to restore and enhance wet‑gap capabilities for armored brigades. These projects create predictable volumes and synchronized acquisition timelines that favor suppliers able to meet interoperability and sustainment requirements across partner nations.
- Material and manufacturing constraints: Aluminum alloy and high‑grade structural steel remain the principal materials for pontoon and panel systems due to their strength-to-weight and corrosion‑resistance characteristics. Our scenario work shows procurement and production risk is materially affected by raw‑material availability and lead times for specialized alloys — a critical input for 2026 sourcing plans.
- Standards‑driven design: Systems are generally engineered to comply with recognized Military Load Classification standards. For defense buyers, explicit alignment to these standards reduces certification friction and shortens fielding timelines; for suppliers, certification and test performance are entry barriers that shape competitive dynamics.
- Dual‑use demand and doctrine evolution: The growing emphasis on rapid disaster response and humanitarian assistance amplifies the non‑combat addressable market for floating bridging solutions. Procurement specifications increasingly privilege modularity and rapid reconfiguration, expanding the use cases beyond traditional combat engineering.
Competitive landscape — profiles and strategic implications
The market is populated by a mix of specialist bridge manufacturers and broader defense system integrators. Our qualitative assessments focus on product archetypes, operational performance, and program delivery track records rather than headline market shares (full firm‑level scorecards and supplier financial overlays are available in the full report).
- CNIM Systèmes Industriels (France) — A specialist with proven motorized floating bridge systems suited to modern armored fleets. Recent delivery and training activity with allied forces demonstrates fieldability and program execution capability; CNIM’s participation in national heavy/light crossing modernization programs highlights its strategic position in European re‑equip initiatives.
- General Dynamics European Land Systems (GDELS) — A prime integrator offering multiple amphibious bridging and ferry platforms with strong emphasis on deployment speed and high load‑capacity systems. GDELS’ involvement in cross‑national replacement programs illustrates the competitive advantage of broad product portfolios and systems integration expertise.
- Acrow (United States) — Focused on prefabricated steel modular bridge solutions and floating barge systems, serving line‑of‑communication and wet‑gap needs for heavier vehicle classes. Their portfolio is oriented toward robust engineering and logistics continuity.
- Mabey Bridge (United Kingdom) — The successor to historic modular bridging designs, offering configurable platforms that pair legacy interoperability with modern modular pontoons for both military and emergency response customers.
- East Asian manufacturers — A cohort of Chinese and regional producers provides competitive price points and proven modular pontoon technologies for certain markets; their role in the global supplier base underscores procurement tradeoffs between cost, sovereign sourcing, and lifecycle support.
- Specialist modular bridge suppliers — Boutique firms focusing on panel, ribbon, or motorized bridge variants remain relevant for tailored solutions, fast innovation cycles, and niche performance characteristics.
Taken together, the competitive field rewards suppliers that can demonstrate certified MLC performance, rapid deployment capability, sustainment infrastructure, and a clear path to interoperability with coalition partners.
Recent program milestones that matter to 2026 planners
- Consortia and national programs have moved from concept to contract and early delivery phases, signaling the start of multi‑year fleets replacement cycles. These initiatives accelerate modernization timelines and inform procurement pacing for allied forces.
- Deliveries and training events with user units validate field readiness and provide early operational feedback loops — valuable intelligence for buyers considering follow‑on orders or capability upgrades.
- Cross‑national projects are reducing duplication of R&D and enabling economies of scale in production and sustainment. For defense industrial planners, participation in such projects can provide market access and longer production runs.
How to use this insight in 2026 — nine strategic actions
- Prioritize procurement requests that align acquisition timing with confirmed program tenders to increase award probability and reduce obsolescence risk.
- Lock material supply agreements for aluminum and structural alloys now, using multi‑year contracts and hedging where appropriate to reduce production volatility.
- Assess interoperability by requiring vendor proof points aligned to recognized load classification standards during the RFP phase; make STANAG alignment a gating criterion where coalition operations are anticipated.
- Design pre‑positioning and logistics contracts that account for lifecycle sustainment rather than capital acquisition only — bridging systems’ operational value is highly dependent on rapid repair and spares accessibility.
- Explore industrial partnerships and parallel sourcing to balance sovereign supply concerns with cost‑effective procurement options.
- Consider targeted investment or M&A in specialist suppliers to secure technology differentiation in motorized systems or rapid‑deployment ribbon bridges.
- Incorporate dual‑use capability requirements (disaster relief adaptability) to broaden funding eligibility and public‑sector use cases.
- Build validation trials into procurement schedules to capture operational lessons and reduce fielding risk; prioritize vendors with demonstrable training and delivery history.
- Use scenario planning to stress‑test acquisition choices against market growth scenarios and supply‑chain shocks projected in our 2026–2032 outlook.
What the full PW Consulting report contains (and why you will need it)
The public preview above highlights the patterns and strategic implications. The full report is the operational toolset for program officers and C‑suite decision‑makers — it contains granular forecast scenarios, procurement timelines, vendor scorecards, supply‑chain heatmaps, R&D roadmaps, and near‑term bidding windows. We intentionally withhold the confidential segmentation and deep financials from this summary to preserve the competitive value of the dataset and to ensure that procurement teams and industrial partners access validated, proprietary intelligence via our distribution channels.
Conclusion — near‑term clarity, long‑term opportunity
The Worldwide Military Floating Bridge market is maturing into a predictable, policy‑driven domain with steady growth and programmatic longevity. For states and industrial participants alike, 2026 is a pivotal year: procurement decisions made now will determine industrial throughput, sustainment architectures, and coalition interoperability for the remainder of the decade. Our study quantifies the opportunity, maps the risks, and prescribes actionable pathways to turn capability requirements into operational outcomes.
For access to the full dataset, vendor scorecards, procurement timelines, and bespoke advisory support, please visit the PW Consulting report page or contact our lead analysts to schedule a private briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Military Floating Bridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com