

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
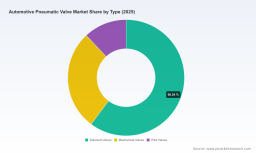
PW Consulting: Worldwide Automotive Pneumatic Valve Market to Reach USD 2,050.0 Million by 2032 (5.42% CAGR, 2026–2032) — Base Year 2025; Asia Pacific Leads at USD 547.6M, Solenoid Valves Top at USD 855.4M; CR3 45.5% (Historical 2020–2025)

Worldwide Automotive Pneumatic Valve Market — Strategic Outlook for 2026 Decision-Makers
As automotive manufacturers and tier suppliers enter 2026, decisions made this year will determine competitive positioning for the next decade. PW Consulting’s latest Worldwide Automotive Pneumatic Valve Market report (base year 2025; forecast 2026–2032) synthesizes five years of historical performance with forward-looking scenario analysis to equip executives with the actionable intelligence they need. The market is forecast to expand at a compound annual growth rate (CAGR) of 5.42% through 2032, growing from an estimated USD 1,420.0 Million in 2025 to approximately USD 2,050.0 Million by 2032. This briefing highlights the strategic takeaways and how the report can be used as a decision support tool — while reserving the granular segment-level datasets for those who access the full study.
Worldwide Automotive Pneumatic Valve Market
Market Snapshot: What the Macro Numbers Tell Us
The pneumatic valve market’s steady recovery and subsequent growth through to 2032 reflect multiple overlapping dynamics. After a period of modest volatility during the early 2020s, the market reached roughly USD 1,420.0 Million in 2025 and is projected to climb to about USD 1,449.9 Million in 2026 as short-term normalization gives way to technology- and regulation-driven demand. By 2032 the market is expected to reach approximately USD 2,050.0 Million — a trend that signals durable expansion rather than a temporary spike.
Worldwide Automotive Pneumatic Valve Market
- Growth drivers include ongoing automation of vehicle production lines, incremental advances in valve performance and materials, and regulatory pressure that is reshaping valve specifications across braking, air management, and emissions-related subsystems.
- Competitive dynamics are moderately concentrated: the top three players account for a meaningful share of the market, while the top five extend that concentration further, indicating that both scale and specialized engineering capabilities matter.
- Cost inputs and supply chain robustness will be decisive. Raw material pricing — notably aluminum and stainless steels — and geopolitical supply risks are persistent variables in product margin models and procurement strategies.
Why 2026 Is a Pivotal Year for Strategic Decisions
2026 is not merely another year in the forecast; it is the hinge between post-pandemic normalization and a multi-year transition driven by regulation, manufacturing modernization, and a focus on lighter, more efficient components. Several factors make 2026 a year where choices compound in importance:
Worldwide Automotive Pneumatic Valve Market
- Regulatory inflection points. New emission and particle monitoring standards have implications that ripple into pneumatic control systems used in braking and air management. Vehicle OEMs and suppliers must decide whether to accelerate investments in redesigned valve architectures or to adopt incremental upgrades.
- Production automation roadmaps. As OEMs continue to upgrade lines for higher throughput and increased flexibility, demand for modular valve platforms and intelligent valve terminals will rise. Suppliers that can offer compact, digitized valve solutions aligned with factory-of-the-future requirements will capture disproportionately more value.
- Supply chain and cost strategy. Material selection and procurement strategies determined in 2026 will influence product cost curves for several product generations. Decisions on hedging, nearshoring, and supplier diversification are therefore strategic rather than tactical.
Report Contents — Practical Tools for Executives
PW Consulting’s report is built to support executive decision cycles: investment approval, product roadmaps, procurement strategy, and M&A screening. Key practical elements include:
- Methodology and assumptions: transparent inputs, scenario frameworks (base, upside, downside), and sensitivity analyses tied to material prices and regulatory timelines.
- Market model and global rollout plan: top-line forecasts and an interactive model that lets users test assumptions against different production and regulation scenarios.
- Commercial playbook: go-to-market options for OEMs, tier suppliers, and component manufacturers, including recommended pricing strategies and preferred commercial partnerships for 2026 execution.
- Technology and innovation roadmap: assessment of modular valve terminals, solenoid innovations, lightweight materials, and integration pathways with vehicle electrification and ADAS testing systems.
- Supply chain and procurement workbook: risk heatmaps, dual-sourcing templates, and cost-to-serve analyses for implementing resilience without sacrificing competitiveness.
- Corporate intelligence suite: profiles, strategic SWOTs, and capability maps for the leading global suppliers — ideal for sourcing, alliance hunting, or acquisition screening.
Competitive Landscape — Who Matters and Why
The market is shaped by a mix of global engineering leaders and focused specialists. Scale and product breadth are important for serving global OEMs, while agility and customization matter for niche automotive systems. Leading firms profiled in the report include legacy industrial powerhouses and specialized valve companies. Their differing strengths create distinct routes to market:
- Parker Hannifin — a broad portfolio across fluid power and control systems; strong in vehicle-integrated and factory automation solutions.
- Bosch Rexroth — deep systems integration capabilities and ties into large automation ecosystems; positions itself where pneumatics intersect with broader drivetrain and vehicle systems.
- SMC Corporation — recognized for its extensive automated manufacturing components and precise control products; excels in high-volume assembly-line deployments.
- Festo — emphasis on modular, scalable valve terminals and systems that map well to flexible production lines.
- Emerson (Aventics) — offers modular platforms and a focus on automotive production environments where standardization and uptime are prioritized.
- Specialists such as Automatic Valve (Ross), Humphrey Products, MAC Valves, WABCO (ZF), and Metal Work — provide targeted solutions for vehicle systems, braking controls, and custom fluid power needs.
Recent corporate moves reinforce broader themes: modular automation platforms (product launches), consolidation to broaden compressed air and valve portfolios (strategic acquisitions), and ecosystem partnerships linking pneumatics to larger automation networks. These developments underline the importance of both organic product development and inorganic growth paths in 2026.
Technology and Materials: Where R&D Budgets Should Flow
Two engineering priorities will define winners in the next five years: weight-to-performance optimization and digital enablement. Regulations and OEM targets push for lighter valve architectures and materials engineering that preserve reliability while reducing mass. Simultaneously, digital-native valve terminals with embedded diagnostics and networked I/O are becoming a manufacturing standard.
- Lightweight materials and advanced alloys: investing in alternative materials and joining techniques reduces vehicle mass and supports emissions targets.
- Electronics integration and predictive maintenance: valves with condition-monitoring capabilities unlock service contracts and reduce downtime for OEM assembly plants.
- Standardized, modular platforms: modularity shortens engineering cycles and enables faster deployment across global production footprints.
Strategy Playbook: Four Actions for 2026
For executives planning resource allocation in 2026, PW Consulting recommends four prioritized actions:
- Align R&D spend to modular and digital platforms. Redirect a portion of valve engineering budgets to embedded controls and lightweight designs, ensuring compatibility with OEM automation protocols.
- Stress-test supply chains using scenario models. Use the report’s procurement workbook to map single-source exposures and implement tiered mitigation strategies (nearshoring, inventory buffer design, strategic partnerships).
- Pursue targeted M&A or partnerships to fill capability gaps. Consider bolt-on acquisitions that add modular valve technology, regional manufacturing capacity, or distribution networks in priority production hubs.
- Negotiate multi-year agreements anchored in performance metrics. Long-term contracts with price-adjustment mechanisms tied to material indices can stabilize margins while signaling commitment to major OEMs.
Market Concentration and Implications for Competition
The market exhibits moderate concentration: the top three companies capture a significant share, and the top five increase that concentration materially. This structure favors established players with scale and engineering depth but leaves room for specialized entrants to capture niches through innovation and bespoke solutions. For buyers, that means a dual procurement strategy — leverage the reliability and coverage of large vendors while maintaining a pipeline of specialized suppliers for differentiated applications.
Final Word — How PW Consulting’s Report Supports Your 2026 Decisions
PW Consulting’s Worldwide Automotive Pneumatic Valve Market report is designed as an executive-grade decision support package: it combines a clear macro forecast (CAGR of 5.42% across 2026–2032 and a top-line projection from roughly USD 1,420.0 Million in 2025 to about USD 2,050.0 Million by 2032) with practical tools for procurement, R&D allocation, go-to-market planning, and M&A screening. The full report contains granular segmentation, regional and application breakdowns, and downloadable data tables that are intentionally reserved for report subscribers — this briefing is a strategic preview intended to demonstrate depth and promote targeted engagement.
If your 2026 strategy depends on understanding how ventilation, braking, emissions, and manufacturing automation requirements will reshape pneumatic valve demand, the full report provides the datasets, supplier profiles, and decision frameworks to act with confidence. PW Consulting’s team stands ready to run bespoke scenario sessions with your strategy, procurement, or product teams to translate these insights into executable roadmaps.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Pneumatic Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com