

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Acute Care EHR Market Set to Reach USD 50,570 Million by 2032, Growing at a 6.52% CAGR

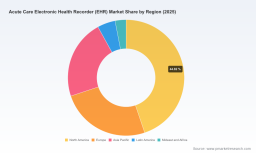
Worldwide Acute Care EHR Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
The acute care electronic health record (EHR) market is moving from modernization to optimization. Our latest market model — with a 2025 base year and a forecast through 2032 — shows the market expanding from roughly USD 32.5 billion in 2025 to more than USD 50.5 billion by 2032, at a compound annual growth rate (CAGR) of approximately 6.52%. For healthcare executives planning capital allocation, vendor selection, and digital transformation initiatives in 2026, the actionable intelligence in this report identifies not only where value is accruing today, but where risk and opportunity will concentrate over the next planning cycle.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
Why 2026 is a pivot year
Several converging forces make decisions taken in 2026 particularly consequential. First, enterprise capital plans continue to accommodate multi-year EHR programs even as overall hospital expenses rose sharply in 2025 (costs across labor, drugs, and supplies expanded materially). Second, technology spending priorities are shifting: AI-based clinical solutions top planned initiatives for 2026–2027, while explicit EHR optimization projects represent a smaller share of planned spend. Third, macro policy and reimbursement updates — including proposed inpatient prospective payment system (IPPS) revisions — are altering revenue and capital assumptions that underpin EHR investment cases.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
Finally, security and resilience are non-negotiable. Hospitals invested heavily in protecting digital infrastructure in 2025, with industry-level spending on cybersecurity and related services reaching into the tens of billions. These dynamics create a strategic inflection point: organizations must weigh upgrade and migration timing against the parallel need to integrate AI, harden systems, and manage constrained operating margins.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
Market dynamics that should shape boardroom conversations
- Persistent growth, evolving priorities: The EHR market is growing at a mid-single-digit CAGR. Growth will be driven by modernization, cloud migrations, and modules that enable operational efficiency and AI integration rather than by simple inpatient digitization alone.
- Consolidation and vendor concentration: The market remains concentrated at the top; the largest vendors account for a substantial share of revenues and implementations. This concentration amplifies strategic risks tied to vendor roadmaps, implementation capacity, and pricing leverage.
- Migration velocity: Momentum of platform changes and migrations continues — multiple hospitals announced EHR platform changes in early 2026 — which creates windows of opportunity for incumbents and challengers alike, but also raises switching-risk premiums for buyers.
- Capital and operating trade-offs: Health systems are balancing major capital outlays for core EHR projects against rising operating cost pressures and competing investments in AI, cybersecurity, and staffing.
- Regulatory pressure and reimbursement volatility: Payment model updates and compliance requirements are increasing the operational burden of EHR programs, particularly around documentation, quality reporting, and interoperability metrics.
Competitive landscape — how to read vendor positioning in 2026
Our coverage evaluates each major vendor across product depth, deployment scale, cloud maturity, implementation risk, and ecosystem openness. Market concentration metrics highlight that a handful of suppliers dominate installed bases and new wins — a reality that shapes negotiation dynamics and migration pathways.
- Epic Systems Corporation: A dominant force in large hospital systems and academic centers. Epic’s deep inpatient and enterprise-wide functionality, combined with recent net new wins, reinforces its role as a market consolidator. For systems prioritizing comprehensive clinical documentation and integrated care pathways, Epic remains the default contender.
- Oracle Health (formerly Cerner): Positioned at scale with a modernizing product portfolio and cloud integration efforts. Oracle Health faces strategic integration and partnership challenges even as it seeks to convert large-scale clients to its cloud-first roadmap.
- MEDITECH: A pragmatic platform for community and rural hospitals. MEDITECH’s Expanse remains attractive to organizations seeking cost-effective, stable inpatient solutions for smaller acute facilities.
- Evident (CPSI): Targeted at smaller acute care providers and affiliated clinics, Evident emphasizes turnkey solutions and operational support for community hospitals navigating constrained IT resources.
- Altera Digital Health: Offers an enterprise suite with flexibility for large hospitals and health systems that need extensible clinical and financial workflows with an emphasis on integration.
- Veradigm: Retains footprint in ambulatory and select acute settings with an emphasis on interoperability and third-party integrations following divestitures.
Recent industry events — including material net additions by some incumbents and ongoing migration announcements in 2026 — underscore that vendor momentum can materially influence competitive tension and pricing. Our report examines wins and losses, partnership strategies, and product roadmaps to help buyers anticipate vendor behavior during RFP and implementation cycles.
What PW Consulting’s report delivers (practical, procurement-ready)
This study is designed for executives and procurement teams who need executable recommendations, not just market narratives. At a glance, the report contains:
- Proprietary market sizing and forecast model through 2032, calibrated to real-world adoption and spend cycles.
- Vendor scorecards that benchmark product capability, cloud maturity, implementation risk, and ecosystem openness.
- Risk-adjusted total cost of ownership templates and scenario modelling for migrations, upgrades, and hybrid deployments.
- Decision frameworks for build vs. buy, cloud vs. on-premise, and phased migration paths aligned to clinical and financial KPIs.
- Procurement playbooks including RFP language, SLAs, rollback triggers, and contract negotiation levers tailored to acute care needs.
- Cybersecurity and resilience checklists, with benchmarking against industry spending patterns and hardening investments.
- Regulatory and reimbursement impact analysis that translates proposed policy changes into budget and deployment implications.
- Change management and ROI roadmaps linking clinical adoption levers to measurable outcomes in throughput, documentation quality, and coder productivity.
To preserve competitive value for our clients, the report purposely consolidates granular segment tables and tactical price schedules behind our full release. The high-level trends and vendor insights above are representative; the full dataset and regional, deployment, and hospital-type splits are available in the complete report.
Strategic recommendations for 2026 decision-makers
Based on our analysis, executives should prioritize the following actions in 2026:
- Align EHR roadmaps with a two-track technology agenda: Protect core clinical systems while selectively accelerating AI-enabled optimization. Prioritize integrations that can deliver near-term clinical decision support and coding automation without destabilizing operations.
- Adopt a migration staging strategy: If pursuing a platform change, split workstreams into stabilization, data migration, and optimization phases. This reduces operational risk and enables earlier realization of incremental value.
- Reassess vendor risk beyond feature parity: Evaluate vendors for implementation capacity, third-party partner ecosystems, and financial stability. Market concentration means a vendor’s ability to scale implementations is as important as product fit.
- Build cybersecurity and resilience into TCO: Quantify the incremental cost and timeline to meet modern security baselines; treat these costs as integral to any procurement decision, not as optional add-ons.
- Use procurement levers to codify outcomes: Tie a portion of payments and acceptance milestones to measurable operational outcomes (e.g., documentation completeness, ED throughput, coder turnaround) to align vendor incentives.
- Scenario-plan for reimbursement shifts: Integrate downside and upside cases for payment reforms into capital budgeting for EHR projects to avoid misaligned payback assumptions.
How to use our findings in your 2026 planning cycle
Boards and executive teams should treat our forecast and decision frameworks as inputs to three operational processes in 2026:
- Capital planning: Use the report’s TCO templates and scenario models to stress-test budgets under multiple cost and reimbursement assumptions.
- Vendor selection and contracting: Leverage vendor scorecards and procurement playbooks to shorten RFP cycles and reduce implementation surprises.
- Operational readiness: Apply the change management roadmaps to sequence training, data migration, and optimization so that clinical staff are supported throughout transitions.
Conclusion — the strategic choice facing health systems
The acute care EHR market in 2026 is less about base-digitization and more about orchestration: orchestrating vendors, clinical workflows, AI enablers, and security investments to deliver measurable improvements in care, cost, and compliance. With the market forecast to expand materially over the next several years and with continued vendor consolidation, the decisions health systems make this year will determine their flexibility and negotiating power for the next contract cycle.
PW Consulting’s full Worldwide Acute Care EHR Market report provides the granular datasets, vendor matrices, and procurement instruments that institutional buyers need to convert strategy into executable programs. For a complete breakdown of regional, deployment, and hospital-type splits, the full quantitative model, and proprietary vendor assessments, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Care Electronic Health Recorder (EHR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com