

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 4.8% CAGR in Worldwide Inguinal Hernia Repair Mesh Market Through 2032, Fueling Synthetic Mesh Adoption

Worldwide Inguinal Hernia Repair Mesh Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest industry intelligence on the Worldwide Inguinal Hernia Repair Mesh market equips executive teams, product leaders, and investors with the strategic context needed to make high-consequence decisions in 2026. This briefing synthesizes the report’s directional findings, highlights the material commercial and regulatory forces reshaping the market, and profiles leading competitors — while intentionally withholding granular segment figures to preserve the report’s proprietary value and guide readers to the full analysis.
Worldwide Inguinal Hernia Repair Mesh Market
Why this report matters for 2026
- Actionable foresight: Healthcare providers, medtech companies, and private equity investors face a narrow decision window in 2026 to align portfolios with evolving reimbursement, labeling, and cost dynamics. Our analysis translates market momentum into specific strategic options — from portfolio prioritization and clinical evidence investments to supply-chain hedging and go-to-market sequencing.
- Risk-calibrated growth paths: The market is neither purely commoditized nor wholly insulated from disruption. We identify where premium differentiation (materials, fixation technology, biologic alternatives) can capture durable margin vs. where price and procurement pressures will dominate.
- Regulatory and reimbursement inflection points: Several near-term policy and coding updates alter the economics of product introductions and prophylactic use cases. We map scenarios that materially change return-on-investment timelines for new launches and label expansions.
Market trajectory — headline sizing and growth
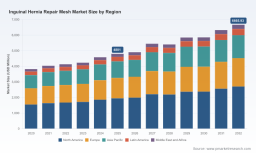
Using a consistent methodology across 2020–2025 (base year 2025) and projecting through 2032, the inguinal hernia repair mesh market demonstrates steady expansion. The market grew from approximately USD 3,820 million in 2020 to roughly USD 4,801 million in 2025. Under our baseline forecast, the market continues to expand through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 4.8%, reaching about USD 6,666 million by 2032.
Worldwide Inguinal Hernia Repair Mesh Market
These topline movements are driven by a mix of demographic pressure, evolving surgical practice (including differential adoption of minimally invasive approaches), technology substitution between synthetic, composite and biological solutions, and shifting procurement behavior among hospitals and ambulatory surgical settings. The moderate, consistent CAGR reflects a market that rewards incremental innovation and evidence-building rather than disruptive leaps.
Worldwide Inguinal Hernia Repair Mesh Market
Key market dynamics to factor into 2026 strategy
- Regulatory clarity and labeling standardization: In June 2025 the U.S. Food and Drug Administration issued draft guidance recommending standardized package labeling for hernia mesh devices. Expect greater transparency around clinical indications and material characteristics, raising the bar for packaging, instructions for use, and post-market surveillance commitments. This creates both a compliance cost and a competitive opportunity for manufacturers that can demonstrate clear, differentiated clinical benefits.
- Material input pressure: Medical-grade polypropylene — the mainstay polymer for most synthetic meshes — has seen pronounced price inflation in recent years. The supply-cost shock increases the importance of materials strategy: manufacturers must weigh reformulation and supplier diversification against passing costs to buyers or accepting margin compression.
- Reimbursement and coding changes: Updated coding and national average payment rates effective January 1, 2026 adjust procedure-level economics for hernia repair. Manufacturers and hospital leaders need to re-evaluate pricing, bundle strategies, and value demonstration to maintain access in fee-for-service and bundled-payment contexts.
- Consolidation and concentration: Market concentration metrics indicate meaningful share at the top end of the market, with the three largest firms controlling a substantial portion and the top five commanding an even larger share. This concentration favors incumbents with broad distribution, integrated surgical platforms, and deep clinical relationships, while creating acquisition and partnership opportunities for mid-tier players seeking scale.
- Litigation and legacy product risk: Historical litigation associated with certain mesh lines remains an operational consideration for acquirers and portfolio managers. Post-merger diligence must explicitly model legacy liability, recall risk, and the reputational impacts of past product histories.
Competitive landscape — positioning and strategic implications
The competitive field is anchored by legacy surgical-device leaders and specialized biomaterials firms. Each has distinct capabilities and strategic trade-offs that matter for 2026 planning:
- Becton Dickinson (BD) — BD’s portfolio includes established monofilament polypropylene meshes and a growing presence in bioresorbable reinforcement through Phasix P4HB technology. Recent milestones — notably the expanded prophylactic indication deployment in Europe and additional sizing options — illustrate a dual approach: defend core polypropylene franchises while cultivating differentiated, higher-margin alternatives for targeted clinical segments.
- Medtronic (Covidien) — With hydrophilic anatomical meshes and self-fixating options tailored for minimally invasive approaches, Medtronic is positioned to capture share where laparoscopic procedures are dominant. Their emphasis on surgeon ergonomics and procedure-specific designs aligns with hospital preference for devices that reduce operative time and variability.
- Ethicon (Johnson & Johnson MedTech) — Ethicon’s large, established portfolio of nonabsorbable and partially absorbable knitted meshes delivers scale advantages and clinical familiarity. The company’s broad surgical and training ecosystem creates stickiness in purchasing decisions, but it must continually justify premium pricing through evidence of reduced recurrence or complications.
- B. Braun (Aesculap) — Known for a range of lightweight polypropylene products, B. Braun leverages European surgeon relationships and a value-for-performance proposition. Their product breadth is an asset in tenders, but margins are sensitive to raw material cost swings and competitive pricing pressure.
- W. L. Gore & Associates — Gore’s ePTFE and other biomaterial offerings address adhesion-mitigation and unique reconstructive requirements. Their material differentiation supports premium positioning in complex cases, but scale limitations relative to the largest incumbents constrain global purchasing leverage.
- Getinge (Atrium Medical) — Atrium’s synthetic mesh heritage provides access to a broad installed base, though past litigation history around certain lines requires active reputation management and targeted clinical evidence work to restore confidence in some markets.
Strategic implications for competitors and new entrants include: accelerate real-world evidence that ties device choice to downstream cost savings; prioritize materials and supply-chain strategies that mitigate polypropylene volatility; and deploy differentiated go-to-market approaches (training, bundled value propositions, or focused specialty clinics) to bypass procurement headwinds.
What the report contains — practical deliverables
PW Consulting’s full report is designed as an operational playbook for 2026. Highlights include:
- Topline market sizing and validated forecasts (2020–2032) with scenario variants reflecting regulatory tightening, raw-material shocks, and accelerated adoption of biologic/resorbable meshes.
- Segment-level demand modeling (by product family, surgical approach, and end-user channel) that quantifies opportunity pools and payback timelines — note: detailed segment figures are available in the full report.
- Competitive landscaping with strategic profiles, capability maps, and acquisition/partnership fit matrices for the major vendors and selected challengers.
- Regulatory and reimbursement roadmaps, including an assessment of the June 2025 FDA draft guidance impact and the 2026 coding changes, with actionable recommendations for labeling, clinical study design, and payer engagement.
- Supply-chain and input-cost stress-testing that models polypropylene price trajectories, alternative material adoption rates, and implications for pricing, margin, and inventory strategy.
- Commercial playbooks for market entry, SKU rationalization, tender responses, and surgeon engagement programs that tie clinical outcomes to hospital economics.
- Risk register and mitigation guidance addressing litigation legacy, quality and complaint management, and recall contingency planning.
Executive recommendations for 2026
- Prioritize evidence generation for differentiated claims: Invest in targeted clinical studies and real-world data that demonstrate the value of novel meshes in reducing recurrence, chronic pain, or overall episode cost.
- Hedge material exposure: Negotiate multi-year supply agreements or secure alternative polymers to smooth cost volatility and preserve margin flexibility.
- Align pricing to procedure economics: Reassess list and net pricing against the updated reimbursement landscape and consider bundled offers that share risk with providers.
- Prepare for packaging and labeling upgrades: Build programs now to meet expected labeling standardization requirements and to communicate clinically meaningful differences to surgeons and procurement teams.
- Evaluate consolidation targets selectively: Use concentration metrics to identify acquisition targets that provide access to underserved geographies, complementary technologies, or white-space clinical segments.
Next steps — where to get the full intelligence
This briefing is a strategic preview intended to orient 2026 planning. PW Consulting’s full Worldwide Inguinal Hernia Repair Mesh Market report contains the granular segmentation, regional and product-level forecasts, and operational tools necessary to execute the recommendations above. For teams preparing budgets, M&A diligence, or clinical development plans in 2026, the full report is the operative source for the detailed inputs and model scenarios.
Contact PW Consulting to request the full report, bespoke briefing sessions, or a tailored scenario-run for your portfolio. Our analysts are available to walk through the models, validate assumptions against your internal data, and co-develop a pragmatic action plan for the coming fiscal year.
For detailed analysis of this topic, please visit the official page: Worldwide Inguinal Hernia Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com