

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Coolant Heaters Market to Surge to USD 9,799.45 Million by 2032 at 14.28% CAGR (2026–2032)

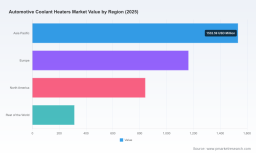
Worldwide Automotive Coolant Heaters Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As mobility electrification accelerates and emissions regulation tightens, the global automotive coolant heaters market is entering a phase of rapid expansion and structural transformation. Our new PW Consulting report — spanning historical performance (2020–2025) and forward projections through 2032 — positions the market as a high-growth, technology-led segment. The market is projected to grow from approximately USD 3.85 billion in 2025 to nearly USD 9.80 billion by 2032, representing a compound annual growth rate (CAGR) of 14.28% over the forecast window. For corporate leaders planning capital allocation, sourcing, or M&A in 2026, this report crystallizes the commercial levers and risk vectors that will define winners and laggards.
Worldwide Automotive Coolant Heaters Market
Why this matters for 2026 strategy
-
Timing of capacity and product investments: The next 18–36 months are decisive. Demand inflection driven by xEV platform ramp-ups and new regulatory cycles will reward firms that align R&D and manufacturing capacity with the 400V/800V architecture timelines now embedded in OEM roadmaps.
Worldwide Automotive Coolant Heaters Market -
Technology differentiation is a commercial moat: High-voltage coolant heater (HVCH) platforms, scalable PTC modules, and integration with heat-pump HVAC and battery-thermal management systems are becoming purchase criteria rather than optional features.
Worldwide Automotive Coolant Heaters Market -
Supply-chain resilience and certification readiness: Thermal components require early-stage integration testing (functional safety, EMC, system-level thermal models). Suppliers who can demonstrate end-to-end validation and certifications shorten OEM adoption cycles.
Market dynamics: demand drivers and structural shifts
Three interconnected forces are shaping the coolant heaters market:
-
Electrification and architecture evolution — As OEMs pursue full EVs, PHEVs and advanced hybrids, cooling/heating needs shift from engine-centric pre-heating to battery and cabin thermal management. This has elevated the strategic importance of electric and high-voltage coolant heaters, which support range, fast-charging efficiency and occupant comfort without increasing engine idling.
-
Regulatory pressure — Stricter emissions and idle-reduction mandates push fleets and OEMs toward technologies that improve cold-start efficiency across ICE and electrified platforms. In parallel, safety and equipment standards (e.g., those embedded in national motor vehicle regulations) are raising certification thresholds for heating subsystems.
-
Component-level innovation — PTC ceramics, modular HVCH platforms (3–9 kW power bands), and integration with heat-pump architectures are enabling manufacturers to offer compact, scalable solutions suitable for both 400V and 800V vehicle systems.
Competitive landscape and what it means for buyers
The market exhibits moderate concentration: while several global incumbents anchor OEM relationships, mid-sized and regional suppliers are closing capability gaps through targeted product portfolios and geographic cost advantages. The top three players hold a material portion of industry sales, and the top five account for a clear majority — a dynamic that benefits established suppliers with proven supply-chain reliability but creates space for focused challengers.
Key strategic profiles we evaluated:
-
Webasto (Stockdorf, Germany) — Deep OEM integrations across passenger and commercial segments. Strength: comprehensive thermal systems capability and experience with HVCH modules suitable for hybrid and electric platforms. Strategic implication: strong partner for system-level integration contracts and platform co-development.
-
BorgWarner (Auburn Hills, MI, USA) — Accelerating HVCH supply awards and visible contracts for both 400V and 800V architectures. Strength: robust engineering for battery thermal management and established Tier-1 contract execution. Strategic implication: a prime acquisition target for firms seeking rapid entry into HVCH for xEVs, and a partner of choice for OEMs standardizing on HVCH modules.
-
Valeo (Paris, France) — Specializes in HVCH solutions that integrate with heat-pump HVAC systems. Strength: compatibility-focused product design enabling multi-modal HVAC strategies. Strategic implication: attractive collaborator for OEMs pursuing premium cabin comfort with minimal energy penalty.
-
Eberspächer (Esslingen, Germany) — Broad product set including hydronic and electric coolant heaters for passenger and commercial vehicles. Strength: portfolio depth across vehicle classes supporting cross-segment synergies. Strategic implication: well-placed to serve global customers seeking a single supplier for diverse fleets.
-
Hotstart (Spokane, WA, USA) , Phillips & Temro (PTI) (Eden Prairie, MN, USA) , and Chinese manufacturers such as Hebei Nanfeng (NF) and VVKB (Victor Industries / Warmda) — These firms cover niches from heavy-duty engine block heating to high-voltage PTC modules for buses and EVs. Strengths: application-specific know-how and cost-competitive manufacturing footprints. Strategic implication: ideal targets for regional OEMs or global suppliers seeking manufacturing cost leverage or segment specialization.
Recent industry moves and their strategic implications
-
BorgWarner’s multi-contract awards for 400V and 800V HVCH technology underscore two trends: OEMs are standardizing on multi-voltage strategies, and suppliers with dual-voltage proficiency secure preferred-supplier status. Companies evaluating supplier selection in 2026 should prioritize demonstrated multi-voltage scalability and validated production readiness.
-
Across the supplier base, product roadmaps emphasize modular power scaling and integration with heat pumps — a signal that thermal component specifications will increasingly be driven by system architects rather than discrete component buyers.
-
Regulatory noise is converging with technical requirements: certifiable safety, EMC compliance, and materials traceability are table stakes for long-term contracts, particularly for suppliers targeting fleets and commercial vehicle OEMs.
What the PW Consulting report delivers (practical, decision-ready content)
Our report is designed to support 2026 strategic decisions across corporate functions — R&D prioritization, supply-chain contracting, M&A screening, product roadmap planning, and procurement. Highlights include:
-
Market sizing and demand models covering historical (2020–2025) and forecast (2026–2032) periods with scenario outputs tied to EV/HEV adoption curves.
-
Technology roadmaps comparing HVCH, PTC, resistive and hydronic heaters on power density, integration complexity, cost-to-manufacture, and certification timelines.
-
Supplier benchmarking and capability matrices that evaluate manufacturing footprint, engineering IP, production readiness for 400V/800V platforms, and program delivery track record.
-
Commercial playbooks: go-to-market options for suppliers (Tier-1 expansion, JV with thermal-system specialists, licensing strategies), and procurement negotiation levers for OEMs and fleets.
-
Regulatory and compliance checklists mapped to major markets, and a technical appendix on materials (PTC ceramics, resistive elements) and safety standards relevant to heating subsystems.
-
Risk and mitigation frameworks addressing raw-material volatility, supply-chain concentration, and product obsolescence in an evolving EV architecture landscape.
Actionable recommendations for 2026
-
For suppliers: accelerate investment in modular HVCH platforms that support both 400V and 800V systems; demonstrate cross-platform system validation to reduce OEM adoption friction.
-
For OEMs: specify thermal subsystem requirements at the platform level early in vehicle design cycles, and favor suppliers with validated safety and EMC test evidence to shorten time-to-production.
-
For investors and M&A teams: prioritize targets with proven multi-voltage capabilities, stable OEM contracts, and manufacturing scale — these attributes correlate strongly with near-term revenue uplift as xEV penetration rises.
-
For procurement and sourcing: build dual-sourcing strategies for critical subcomponents (e.g., PTC elements and control electronics) and include certification milestones tied to payment and delivery terms.
How to use this intelligence
PW Consulting’s analysis is intentionally structured as a decision-support toolkit rather than a purely descriptive study. Use the report to:
-
Stress-test product roadmaps against our scenario outputs for 2026–2032;
-
Prioritize engineering investments and staffing to meet the multi-voltage and system-integration requirements now common in procurement specifications;
-
Identify and shortlist acquisition or partnership targets based on capability matrices and CR-level consolidation dynamics;
-
Negotiate with suppliers from an informed position by leveraging our supplier benchmarks and candidate risk profiles.
Closing perspective — the strategic payoff
Our market projection — a roughly threefold expansion of total market value across the forecast horizon at a 14.28% CAGR — is not merely a growth number. It signals a commercial pivot: thermal management is shifting from a commoditized subsystem to a strategic differentiator that affects vehicle range, customer experience, and regulatory compliance. Companies that act in 2026 to align product portfolios, validate multi-voltage architectures, and shore up certified production capabilities will capture disproportionate value as the market scales.
PW Consulting’s full report contains the detailed segmentations, supplier scorecards, and model-level forecasts that corporate teams rely on to convert insight into contracts and product launches. For access to the full dataset, proprietary segment-level benchmarks, and supplier performance dashboards, please visit our report page and download the complete Worldwide Automotive Coolant Heaters Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Coolant Heaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com