

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Heated Wiper Fluid Market Poised for Robust Expansion — 6.5% CAGR Projected Through 2032

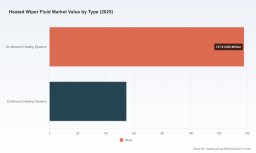
Worldwide Heated Wiper Fluid Market — Strategic Imperatives for 2026
Executive preview from PW Consulting’s latest market study (Base year: 2025)
PW Consulting’s newest Worldwide Heated Wiper Fluid Market report delivers a forward-looking, decision-ready analysis designed to inform boardroom strategy and commercial execution in 2026. Built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study models a global market that expanded from USD 142.15 Million in 2020 to USD 192.4 Million in 2025, and that we project will approach USD 299.01 Million by 2032 — a compound annual growth rate (CAGR) of 6.5% across the forecast window. These headline figures underscore steady, durable demand driven by OEM cold‑weather performance packages, aftermarket upgrade cycles and evolving regulatory and safety expectations.
Worldwide Heated Wiper Fluid Market
What the report delivers — pragmatic, actionable intelligence
- Robust market sizing & scenarios: Transparent top‑line market models for 2020–2032, plus three scenario pathways that stress-test adoption under differing technology, regulatory and raw‑material assumptions.
- Go‑to‑market playbooks: OEM and aftermarket channel strategies, commercial partners mapping, pricing levers and segmentation frameworks intended to accelerate adoption while preserving margin.
- Supply‑chain & manufacturing diagnostics: Detailed supplier mapping for heating elements, fluid formulators and assembly partners, including lead‑time sensitivity, single‑sourcing risks and CAPEX planning heuristics.
- Technology & component roadmap: Comparative assessment of on‑demand versus continuous heating architectures, heating element technologies (PTC and resistive), and integration vectors with wiper and washer subsystems.
- Regulatory & safety matrix: A compiled view of historical incidents, active regulatory petitions and regional standards that materially affect product design, testing protocols and warranty exposure.
- Competitive benchmarking: Tactical profiles of incumbent OEM suppliers, aftermarket specialists and component manufacturers, including recent product launches, channel footprints and partnership signals.
- Commercial and M&A playbook: Acquirer & partner scoring, valuation sensitivities, and example term-sheets that reflect market concentration dynamics and technology ownership.
- Practical appendices: Primary interview excerpts, patent landscape summary, raw material cost sensitivity model, and an editable financial model executives can adapt to corporate planning cycles.
Why this matters for 2026 corporate decision-making
2026 will be a pivot year for companies that want to convert emerging interest in heated wiper fluid systems into durable revenue streams without taking oversized safety or regulatory risks. The market is large enough to justify targeted investment yet concentrated enough that supply, technology and regulatory choices will determine winners and losers. PW Consulting’s study is built to be used as a playbook for decisions that must be executed this year:
Worldwide Heated Wiper Fluid Market
- Product roadmap alignment: Choose between on‑demand and continuous heating architectures based on integration complexity, thermal performance needs and product‑lifecycle economics. The report's comparative, component‑level analyses help prioritize one or two platform choices for rapid scale-up.
- Sourcing & supplier diversification: With PTC heating elements increasingly contested by EV thermal subsystems and seat heaters, supply constraints are a real near‑term risk. Our supplier maps and procurement stress tests enable procurement teams to institute dual‑sourcing and on‑shore/off‑shore hedges in 2026.
- Regulatory risk mitigation: Historical recalls and current regulatory attention mean safety engineering and compliance testing must be front‑loaded. The regulatory matrix combined with our incident root‑cause analysis supports robust specification upgrades and warranty provisions before mass deployment.
- Commercial channel sequencing: The aftermarket remains an important beachhead for volume, brand validation and consumer education. The report's go‑to‑market playbook outlines the optimal sequence: validated OEM integrations → prioritized aftermarket SKUs → targeted regional rollouts driven by climate and installation economics.
- M&A and partnership targeting: Given market concentration and the presence of established global players, inorganic options can accelerate capability build. Our M&A scoring identifies targets whose technology ownership or channel access materially change an acquirer’s go‑to‑market profile.
Competitive landscape — who to watch
Industry dynamics are shaped by a mix of established OEM suppliers, fluid formulators and aftermarket specialists. The market shows moderate concentration (CR3 ~42.15%; CR5 ~58.4%), meaning the top few vendors exert meaningful influence while space remains for agile entrants and niche specialists. Key companies profiled in the report include:
Worldwide Heated Wiper Fluid Market
- Valeo S.A. (France) — A leader with integrated heated wiper blade systems (AquaBlade) that bridge OEM and aftermarket channels; recent introduction of a heated AquaBlade aftermarket SKU underscores an OEM→aftermarket monetization play.
- Recochem Inc. (Canada) — Global fluid formulator supplying OEMs and aftermarket channels with temperature‑protected washer fluids; R&D capabilities focused on low‑temperature performance.
- CCI Corporation / Genuine Chemistry (Japan) — Longtime OEM supplier profile with broad exposure across passenger, light and heavy equipment applications; visible at major trade events signalling ongoing OEM demand.
- SPLASH Products / Factory Motor Parts (USA) — US‑based manufacturing and aftermarket distribution expertise, emphasizing winter formulations and channel responsiveness.
- Old World Industries (OWI, USA) — Known consumer brands and commerce channels that can scale seasonal promotions and bundle offerings.
- Kautex Textron (Germany) — Specialist in fluid management and in‑vehicle heater integration for OEMs; product engineering is a differentiator for vehicle‑level suppliers.
- Denso Corporation (Japan) — Thermal management and subsystem supplier whose component depth can enable integrated solutions in high‑volume platforms.
- AlphaTherm / Donmar (USA) — Aftermarket heater systems evolving from OEM technology; attractive partner for distributors.
- HydroBlast (Kleinn, USA) & China Hong Wipers (China) — Aftermarket specialists with focused heating solutions, representing two distinct commercialization strategies (premium US aftermarket vs low‑cost global sourcing).
Recent market signals highlighted in the study include product availability moves (Valeo’s heated AquaBlade in 2025), OEM patent activity (example: Ford’s 2023 patent for heated washer bottle systems) and trade show visibility (CCI/Genuine Chemistry at AAPEX 2025). These indicators reflect both OEM pipeline maturation and aftermarket commercialization momentum.
Key risks and structural constraints for 2026
- Safety & regulatory risk: Legacy recalls and active regulatory petitions have kept windshield washer systems in regulatory view. Recall history demonstrates how module-level design faults can produce outsized operational and reputational costs if not addressed through design controls and supplier QA.
- Raw-material & environmental constraints: Winter formulations commonly use methanol for low‑temperature protection. Methanol's toxicity, flammability and reclamation costs create operational and regulatory complexities for formulators and recyclers.
- Component competition: PTC element availability is constrained by competing demand from EV thermal management and other heated‑seat applications. Procurement strategies must account for potential bottlenecks and price volatility.
- Aftermarket safety liabilities: Retrofits and low‑cost installations raise failure and warranty exposure; robust installation protocols and aftermarket partner certification programs are essential to protect brand equity.
Scenario planning — how sensitivities change the 2026 playbook
Our modeling allows executives to test three realistic scenarios that materially affect near‑term investment choices:
- Base case (aligned with our headline forecast): Gradual technology adoption, steady OEM rollouts and balanced aftermarket growth — makes a phased investment in product platforms and selective CAPEX sensible.
- Constrained supply case: PTC availability tightness and raw‑material price spikes compress margins and delay launches — favors strategic supplier contracts, design changes to reduce PTC dependency, and selective outsourcing.
- Regulatory/recall shock case: A high‑visibility incident or accelerated regulatory mandates forces rapid redesigns and expanded testing — underscores the need for contingency reserves, accelerated validation, and insurance/indemnity planning.
Immediate actions we recommend for Q1–Q4 2026
- 90 days: Run a supplier risk heat‑map, lock preliminary dual‑source agreements for key heating elements, and commence a product safety audit against the regulatory matrix found in the report.
- 6–18 months: Pilot an OEM integration program and an aftermarket SKU bundle in two climatically appropriate regions to validate installation economics and warranty performance; build a launch playbook from pilot learnings.
- 18–36 months: Evaluate bolt‑on acquisitions for fluid formulation IP or heater module manufacturing to accelerate scale; activate tier‑1 partnerships to secure platform-specific roadmaps.
How PW Consulting’s report becomes a working tool in 2026
This is not a static intelligence product. The report is delivered with an editable financial model, scenario templates and a vendor due‑diligence checklist that corporate strategy, product and procurement teams can use to populate their 2026 operating plans. For boards and investment committees, the study supplies the due‑diligence baseline required to greenlight CAPEX or M&A with quantified downside protections.
Next steps
For executives evaluating entry, expansion or defensible scale in the heated wiper fluid arena in 2026, PW Consulting’s report gives you the context, the scenarios and the tactical frameworks to act with conviction. The public summary above highlights the strategic themes and headline market trajectory; our full report contains the proprietary segmentation, granular regional and application forecasts, supplier scorecards and downloadable financial models referenced here.
Request the full market study and proprietary datasets via the PW Consulting client portal. Our advisory team is available to brief leadership teams and to run a tailored two‑day strategy workshop that maps the report’s implications directly to your product, procurement and M&A plans for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Heated Wiper Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com