

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide HEA, HPA, HEMA & HPMA Market Poised for 5.28% CAGR as Global Demand Accelerates

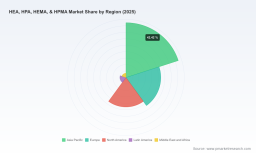
Worldwide HEA, HPA, HEMA, & HPMA Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s newest market study, published with base year 2025 and a forecast horizon of 2026–2032, provides a forward-looking, operationally focused view of the global HEA, HPA, HEMA & HPMA market. The study frames a market that grew steadily through the early 2020s and is projected to expand at a compound annual growth rate (CAGR) of 5.28% across the forecast period. Measured in USD (revenue unit: Million), total market value reached approximately 1,530 Million USD in 2025 and is forecast to approach 2,193 Million USD by 2032 — a trajectory that has direct implications for procurement, capacity planning, technology investment, and M&A strategies in 2026.
Worldwide HEA, HPA, HEMA, & HPMA Market
Why this report matters for 2026 corporate strategy
-
Timing matters: 2026 is the inflection point in which legacy demand patterns (coatings, adhesives, specialty resins, and medical grades) intersect with new supply and regulatory pressures. Our forecast horizon captures both near-term operational risks and medium-term strategic choices.
Worldwide HEA, HPA, HEMA, & HPMA Market -
Decision focus: executives need rapid, defensible inputs to set capex priorities, negotiate multi‑year off‑take agreements, and align R&D roadmaps for high‑value, specialty grades. The report turns macro trajectories into toolkits for those decisions.
Worldwide HEA, HPA, HEMA, & HPMA Market -
Margin protection: feedstock volatility, intermittent price spikes and production additions are already reshaping input cost dynamics. Our analysis translates these movements into scenario-based margin and cash‑flow impacts for industrial and specialty producers.
Key market signals shaping 2026
-
Price and feedstock volatility: acrylic and methacrylic acid markets showed significant swings in 2025 — a reminder that upstream feedstock behavior materially alters producer economics for HEA/HPA/HEMA/HPMA. The report models multiple feedstock paths and their asymmetric impacts on corporate P&L.
-
New capacity vs. demand balance: new capacity additions in 2024–2025 introduced downward price pressure in the latter half of 2025, compressing margins for commodity grades but widening opportunity in specialty, high‑purity segments.
-
Regulatory and compliance shocks: recent emissions-control requirements and evolving medical‑material scrutiny underscore the need to model both compliance capex and potential market restrictions, especially for device‑grade monomers.
-
Concentration and bargaining power: the market exhibits moderate concentration among global incumbents. Our concentration metrics and supplier maps help procurement teams prioritize strategic sourcing and contingency planning.
What PW Consulting’s report delivers — practical, operational intelligence
-
Market sizing and dynamics: an audited time series spanning 2020–2025, plus transparent forecast scenarios for 2026–2032, with core assumptions documented for executive review.
-
Supply‑chain mapping: plant-level capacity tracking, recent capex announcements, and import/export flow analysis that let supply planners assess single‑source risks and logistics constraints.
-
Price and margin scenarios: stress tests that combine feedstock price shocks, demand slippages, and capacity realizations to quantify downside exposure and upside leverage.
-
Regulatory and product risk assessment: compliance cost estimates, a regulatory event calendar, and medical‑grade risk mapping to guide both manufacturing location and product portfolio decisions.
-
Commercial playbooks: supplier scorecards, negotiation checklists for long‑term contracts, and criteria for selecting toll manufacturers or JV partners.
-
Strategic options and M&A roadmap: valuation reference points, integration risks, and prioritized target archetypes for bolt‑on acquisitions or technology partnerships.
-
Interactive deliverables: downloadable modelling files, customizable dashboards, and a decision matrix designed for cross‑functional strategy sessions.
Competitive landscape — where incumbents and challengers stand in 2026
The market is served by a global mix of integrated chemical majors, regional specialists, and a growing cohort of Chinese producers that have moved from niche supply into large‑scale production. Key global players covered in the report include Dow Inc. (Midland, Michigan, USA), BASF SE (Ludwigshafen, Germany), Mitsubishi Chemical Group Corporation (Tokyo, Japan), Nippon Shokubai Co., Ltd. (Osaka, Japan), Osaka Organic Chemical Industry Ltd. (Osaka, Japan), Evonik Industries AG (Essen, Germany), and Röhm GmbH (Darmstadt, Germany). A significant and expanding roster of Chinese producers — such as Wanhua Chemical Group and Dechem International — increasingly compete on scale and cost.
Our strategic assessment highlights the following competitive dynamics:
-
Scale and integration as a defensive moat: large, integrated players retain advantages in feedstock sourcing, global distribution, and downstream customer relationships — particularly where they can offer bundled resins, additives, and technical support.
-
Specialty differentiation: suppliers focusing on high‑purity, low‑skin‑sensitization grades, and device‑qualified monomers maintain pricing power. These include established Japanese and European specialty houses as well as smaller U.S. and European firms targeting medical and electronics markets.
-
Chinese capacity ramp: selective Chinese producers have announced significant capacity expansions. These moves alter regional balances and require import/export and logistics stress tests for buyers and sellers alike.
-
Market concentration: the top-tier producers capture a substantial share of global supply, creating opportunities for strategic partnerships but also the potential for supply‑side power in contract negotiations.
Recent corporate and sector developments you should model in 2026 plans
-
Capacity announcements by major Asian producers that shift near‑term supply dynamics and place downward pressure on commodity grades.
-
Commercial responses from incumbents — including price increases tied to energy and raw material cost pass‑throughs — which signal management intention to defend margins during feedstock surges.
-
Policy changes imposing new emissions and reporting requirements for synthetic organic chemical facilities, with temporary relief mechanisms that create staggered compliance timelines and short‑term uncertainty for plant operations.
Functional implications — how different teams should act in 2026
-
CEOs and corporate strategy: run at least two integrated scenarios (stress and upside) that couple feedstock volatility with capacity entry and regulatory cost curves. Use these to set capex thresholds for new facilities and to assess selective vertical integration.
-
Procurement and supply chain: diversify supplier panels, secure partial hedges on acrylic/methacrylic feedstocks where commercially viable, and build dual-sourcing clauses into multi‑year contracts to reduce single‑point failure risk.
-
R&D and product management: prioritize formulations that migrate customers to higher‑value, low‑sensitivity grades and accelerate small‑batch qualification for device/certified applications where barriers to entry remain high.
-
Investors and corporate finance: stress test valuation models with mid‑cycle feedstock shocks and regulatory cost windows; identify M&A targets that close technology or geographic gaps rather than purely increasing commodity tonnage.
-
Regulatory affairs and QA: flag medical‑grade monomers for continuous monitoring of biocompatibility literature and device‑level reviews; build contingency plans for extended qualification timelines.
Risk map — what can change the trajectory?
-
Feedstock shocks (propylene and acrylic/methacrylic acid) that ripple through contract pricing and spot markets.
-
Rapid capacity additions in low‑cost regions that depress commodity‑grade prices and compress margins for marginal producers.
-
Regulatory interventions that raise compliance costs or restrict product use in sensitive applications.
-
Technology shifts that substitute alternative chemistries or that materially reduce reliance on current monomer families in high‑volume applications.
How to use the full report (and why you’ll want it)
This preview is designed to help executives and functional leaders prioritize their 2026 questions. The full PW Consulting report provides the proprietary datasets, plant and supplier level maps, interactive scenario models, and the step‑by‑step playbooks that convert market intelligence into executable decisions. Because the strategic value lies in connecting segment‑level dynamics to contracting, capex and R&D choices, we intentionally reserve detailed split‑level tables and model inputs for the full report and accompanying dashboards.
For teams building budgets, negotiating supply agreements, or assessing acquisition targets in 2026, the combination of audited market sizing (2020–2025), clear forecast scenarios (2026–2032), and supplier‑level diagnostics will materially reduce uncertainty and shorten decision cycles.
Conclusion — a practical warning and an opportunity
The HEA, HPA, HEMA & HPMA market is moving from a period of steady expansion into one marked by competing forces: new capacity and feedstock swings that compress commodity margins, versus growing demand niches that reward high‑purity and regulatory‑qualified grades. Firms that treat 2026 as an operational planning year — aligning procurement, capex, and product strategy — will convert short‑term turbulence into durable competitive advantage. PW Consulting’s report equips teams with the scenarios, supplier intelligence, and commercial playbooks to do exactly that.
To access the full dataset, modular models, and supplier scorecards that underpin these insights, please visit the PW Consulting report page for Worldwide HEA, HPA, HEMA, & HPMA Market. The full deliverable is crafted to be a working toolkit for 2026 strategic decision‑making.
For detailed analysis of this topic, please visit the official page: Worldwide HEA, HPA, HEMA, & HPMA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com